
Hô Chi Minh-Ville étend ses zones de développement et renforce ses relations diplomatiques locales
Source: PR Newswire
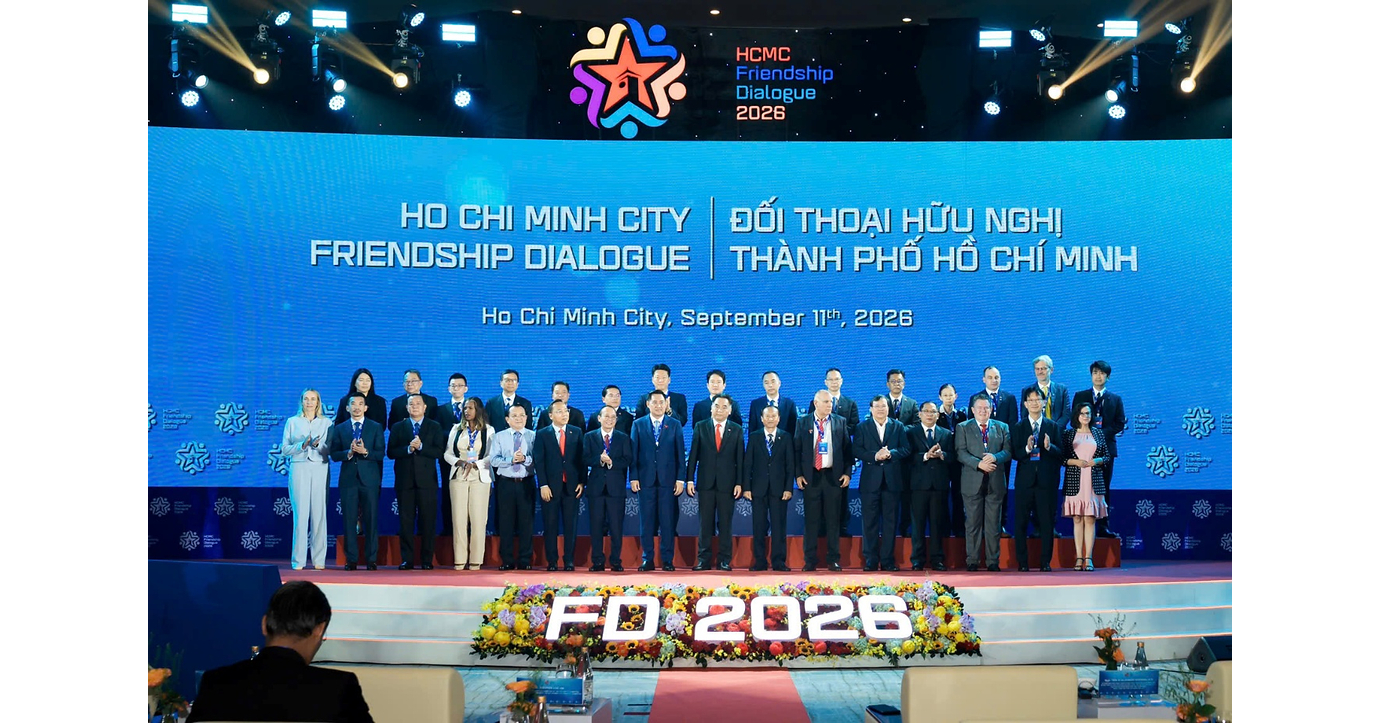
Ho Chi Minh City reported a nearly $60 billion economy in H1 2026, its highest level in a decade, accounting for roughly 25% of Vietnam's GDP and more than 30% of state budget revenue. Following its merger with Binh Duong and Ba Ria-Vung Tau, the expanded city now spans over 6,770 km² and more than 14 million residents, combining financial services, high-tech industry and deep-water port infrastructure. The city is pursuing multilateral port cooperation, green technology investment and supply-chain integration, supported by more than 20,000 active FDI projects and targets for regional GDP per capita of $14,000 by 2030 and $75,000 by 2045.
Analysis
This is not yet an earnings-relevant catalyst; it is a policy-intent signal whose investability depends on whether port coordination converts into funded dredging, rail/road links, customs digitization and terminal concessions. The near-term beneficiaries are more likely Vietnamese construction materials, industrial-park operators and banks with project-finance exposure than global shipping lines, whose earnings remain dictated by freight rates and fleet supply. A more efficient southern gateway could gradually divert incremental manufacturing exports from congested regional alternatives, marginally improving Vietnam’s relative FDI proposition versus Thailand and Indonesia.
The key second-order effect is land-value and utility-demand inflation around the industrial-port corridor. Industrial-park developers with permitted land banks and power/water access should gain pricing power; late-cycle developers without completed infrastructure may face higher acquisition costs and execution risk. ESG-oriented port standards can also raise capex and compliance costs for smaller logistics operators, favoring scaled terminal operators and Japanese/Korean supply-chain tenants that need auditable Scope 3 logistics.
For the next 1-3 months, treat announcements of concession awards, public-capex allocations, FDI commitments, and throughput data as confirmation rather than price catalysts. Over 6-18 months, the relevant macro watch is whether export growth and FDI disbursements accelerate without renewed power shortages, FX pressure, or land-clearance delays. The bullish narrative is falsified if project approvals fail to translate into budgeted spend, container throughput does not outgrow national export volumes, or Vietnamese industrial rents rise enough to erase the country’s labor-cost advantage.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No standalone trade on the press release. Create an alert for listed Vietnamese industrial-park and logistics names with confirmed land banks near the southern manufacturing corridor; require evidence of signed tenant commitments or approved infrastructure capex before entry.
- For broad EM exposure over 6-18 months, monitor a relative long Vietnam equity proxy / short Indonesia or Thailand manufacturing-sensitive exposure only after Vietnam FDI disbursement and export-growth data outperform for two consecutive months. Thesis is supply-chain share gain; exit on renewed VND stress or a material FDI slowdown.
- Avoid extrapolating the development narrative into global container-shipping longs. Maersk, Hapag-Lloyd and ZIM remain principally exposed to Red Sea routing, global demand and vessel oversupply; local port efficiency is insufficient to offset those drivers.
- Watch Japanese industrial automation and factory-equipment suppliers with Vietnam manufacturing exposure as a second-order beneficiary if high-tech tenant announcements emerge. Do not position until tenant identity, capex size and commissioning dates are disclosed.
More News
- Oil extends losses as Saudi Arabia reportedly offers ship-to-ship crude transfers after pipeline hit
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- 'Hostile act': Trump threatens EU with tariffs over Canada associate-membership proposal
- US military claims Strait of Hormuz remains open amid ongoing blockade
- Oil prices extend losses as fears of Middle East supply disruptions ease
- Congress passes sweeping US sanctions bill targeting Russia