
CATL rozpoczyna produkcję próbną ogniw akumulatorowych na Węgrzech
Source: PR Newswire
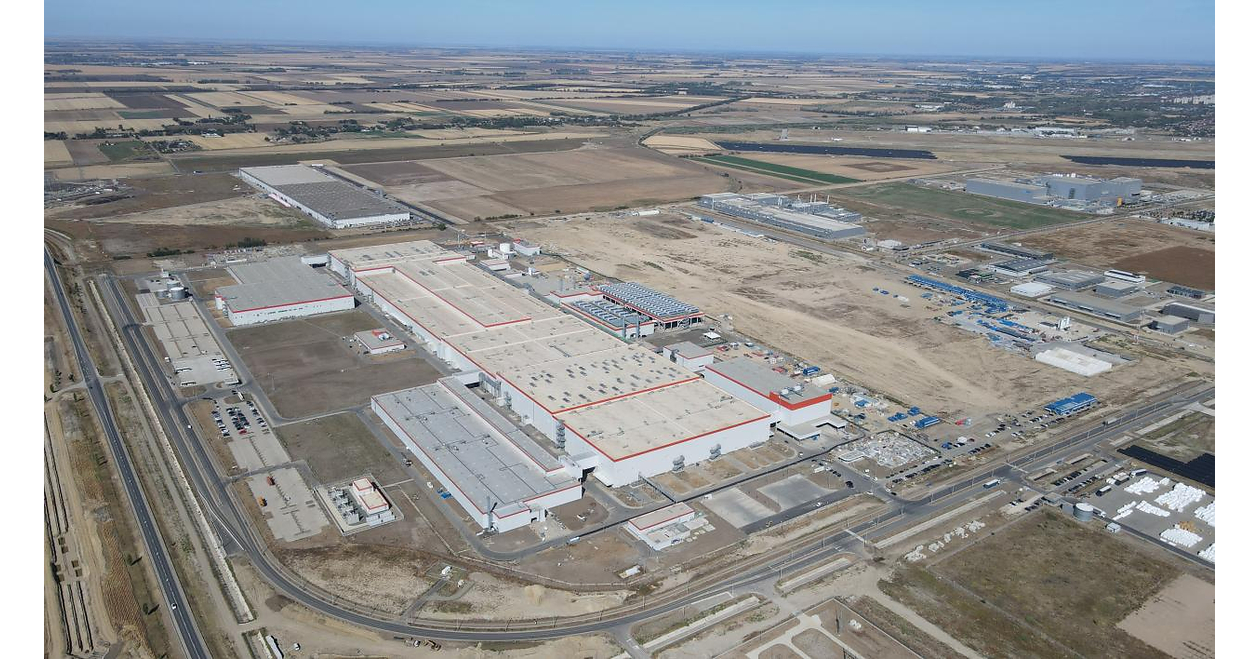
CATL began trial battery-cell production on two initial lines at its new Debrecen, Hungary facility on September 22, 2026, after obtaining occupancy and required environmental permits. The plant, which has already produced 537,000 battery modules since autumn 2024, is intended to supply leading European EV manufacturers and ultimately reach 100 GWh of capacity, making it CATL's largest production base outside China. The start-up follows remediation of prior compliance deficiencies and remains subject to ongoing environmental and workplace-safety monitoring.
Analysis
The key market implication is localized cell supply rather than incremental European EV demand. A fully scaled 100 GWh asset would be large enough to materially improve delivered-cell economics for Central European OEMs by reducing logistics, working-capital buffers and exposure to cross-border trade friction; BMW (BMW.DE), Mercedes-Benz (MBG.DE) and Volkswagen (VOW3.DE) are the most plausible beneficiaries through lower battery procurement risk. CATL's flexible-line claim also strengthens its negotiating leverage against European cell competitors LG Energy Solution (373220.KS), Samsung SDI (006400.KS) and Panasonic (6752.T), particularly if OEMs prioritize chemistry flexibility over domestic ownership.
The near-term financial signal remains weak: trial output on two lines is not evidence of commercial yield, qualification or profitable utilization. The relevant 1-3 month catalysts are customer qualification disclosures, ramp yields, environmental-monitoring results and any evidence that contracted volumes match installed capacity; a slow ramp would turn fixed costs into a margin drag and limit the presumed OEM benefit. European EV demand and OEM production schedules remain the binding variables over the next 6-18 months—regional capacity can amplify price competition if automakers do not absorb the output.
Consensus may overvalue the geopolitical insulation. Local manufacturing reduces logistical exposure, but it does not eliminate CATL's dependence on China-linked technology, inputs and potentially policy-sensitive ownership; any tightening of EU local-content, subsidy or foreign-investment rules could still impair customer adoption. Conversely, successful qualification would weaken the strategic rationale for high-cost European battery entrants, creating a more durable valuation headwind for pure-play regional cell makers than for diversified OEMs.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Maintain a 1-3 month watch on BMW.DE and MBG.DE; add only after disclosed cell qualification or EV production guidance confirms volumes. The upside is procurement-risk and margin-mix improvement, while a cut to 2027 EV production plans would falsify the thesis.
- Consider a 6-12 month relative-value basket: long BMW.DE / short 373220.KS, sized modestly. The trade expresses localized Chinese supply pressuring merchant-cell pricing while benefiting a proximate OEM; exit if LGES secures equivalent contracted European volumes or CATL ramp utilization remains below commercial levels.
- Avoid treating CATL (300750.SZ) as an immediate ramp trade. Set alerts for customer nominations, utilization data and any environmental enforcement action; trial production alone provides insufficient evidence to underwrite earnings accretion.
- For European battery-exposure hedging, monitor VOW3.DE and STLA for evidence of lower battery costs translating into price cuts rather than gross-margin retention. If OEM EV incentives accelerate while pricing deteriorates, use the development as a reason to prefer suppliers with contracted volumes over OEM equity beta.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- ‘I have a big decision to make’: Trump had a ‘good meeting’ with Iranian officials warning he may ‘annihilate the Islamic Republic’
- Bank of America says Brent crude oil could top $150 a barrel if Iran war disruptions persist
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features and More Sources for Document Search
- How to Evaluate AI Report Writers for Financial Analysis