
Luxor Is at the Heart of Egypt’s Medical Tourism Push
Source: Bloomberg
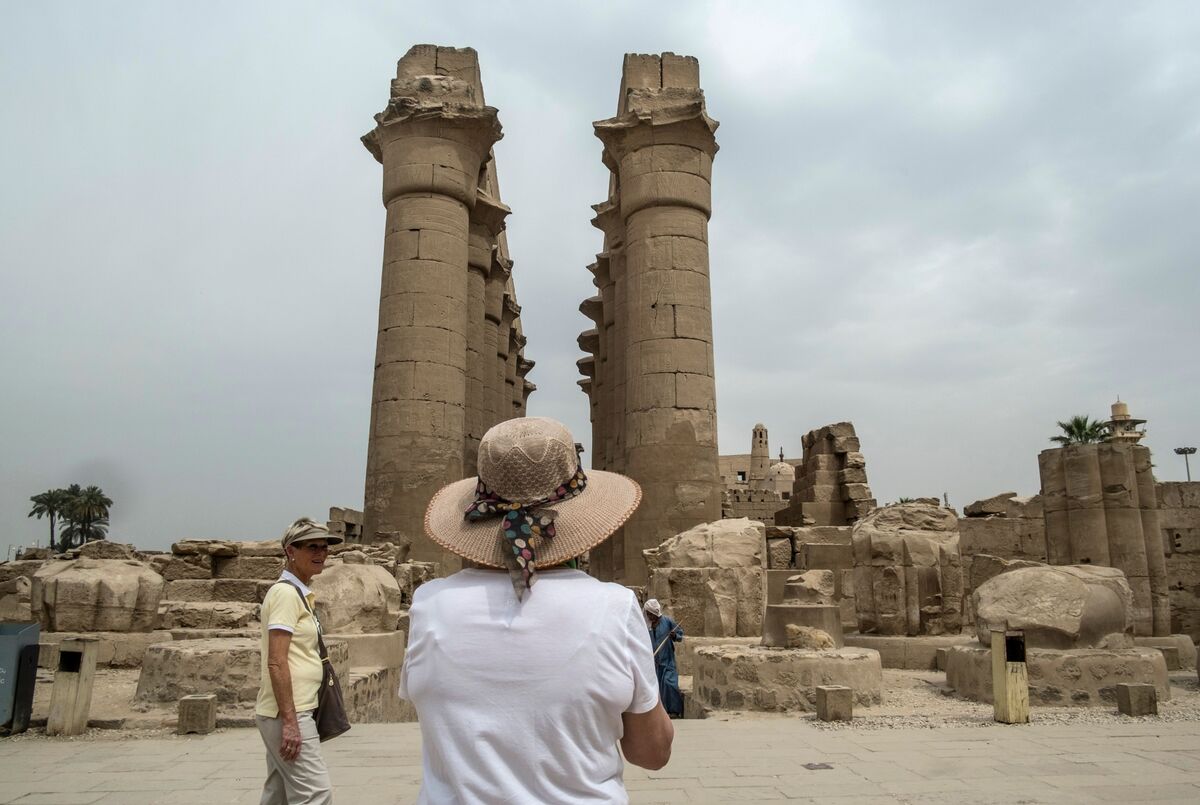
Egyptian authorities are seeking to revive Luxor as a medical-tourism destination and capture a larger share of the global healthcare tourism market, estimated at about $34 billion last year by Grand View Research. The initiative aims to compete with established regional providers including Turkey and the UAE across surgical procedures, dentistry and cosmetic services, leveraging Luxor's historical reputation for health-oriented travel.
Analysis
The investable implication is less about incremental tourist arrivals than Egypt’s ability to convert foreign-currency healthcare spending into a higher-margin, year-round travel category. If credible accreditation, visa processing and hospital capacity emerge, private providers such as Cleopatra Hospital Co. (CLHO EY) could gain a hard-currency revenue stream while Luxor hotel operators benefit from reduced seasonality and longer average stays. The constraint is that destination healthcare demand is reputation- and referral-driven; marketing alone will not close the quality, insurance-network and post-operative-care gap versus Turkey or the UAE.
Near term, this is not a standalone equity catalyst: the initiative has no disclosed capital commitment, capacity target, pricing framework or participating listed operators. Over 6-18 months, sustained medical-tourism inflows could modestly support Egypt’s external financing profile and hospitality RevPAR, but only if providers can retain physicians and import medical equipment despite FX constraints. A weaker Egyptian pound improves the price proposition for foreign patients, yet simultaneously raises imported-device and pharmaceutical costs, limiting hospital margin capture unless procedures are priced in dollars or euros.
The contrarian view is that Luxor’s tourism brand may be more useful as an add-on recovery destination than as a surgical hub. That favors bundled travel and specialty outpatient services over capital-intensive tertiary hospitals; without internationally recognized clinical outcomes and insurer reimbursement, the program risks becoming a low-return public marketing spend rather than a material private-sector earnings driver.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate directional trade. Treat CLHO EY and Egyptian hospitality exposure as watch-list names until authorities disclose participating facilities, foreign-currency pricing and independently verifiable patient-volume targets.
- Monitor CLHO EY quarterly for foreign-patient revenue, dollar-linked pricing, occupancy/utilization and imported-supply cost inflation. A sustained 5%+ revenue contribution from international patients with stable EBITDA margin would justify reassessing a 6-12 month long.
- For regional relative value, favor UAE-listed Burjeel Holdings (BURJEEL AD) over a speculative Egypt medical-tourism thesis if seeking exposure now: it has an established regional provider platform, while risk is multiple compression if patient volumes fail to translate into higher-acuity mix.
- Falsification trigger for any Egypt tourism-linked long: renewed FX shortages, restrictions on medical-device imports, or a material EGP depreciation without corresponding hard-currency procedure pricing; each would impair service quality and private-hospital margins within 1-3 quarters.
More News
- Caruso-Cabrera: The investing tailwinds for Latin America are the best in decades
- Budget airline king Bill Franke warms to first-class seats and premium upgrades
- Qatar Airways Bets on Fleet and Cargo Growth
- ‘We’ve been free-riding off Beijing in a weird way’ — Oil prices are high but could be much worse. Trump has China’s Xi to thank for that
- Wall Street's Bull Case for Bristol Myers Squibb Is Getting Louder
- Turkiye backs Saudi Arabia’s security amid escalating Houthi attacks: FM
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations
- Selecting an AI Research Platform for Institutional Investors