
This driverless-truck company could be a ‘long-term winner’ in a market Tesla plans to enter soon
Source: MarketWatch
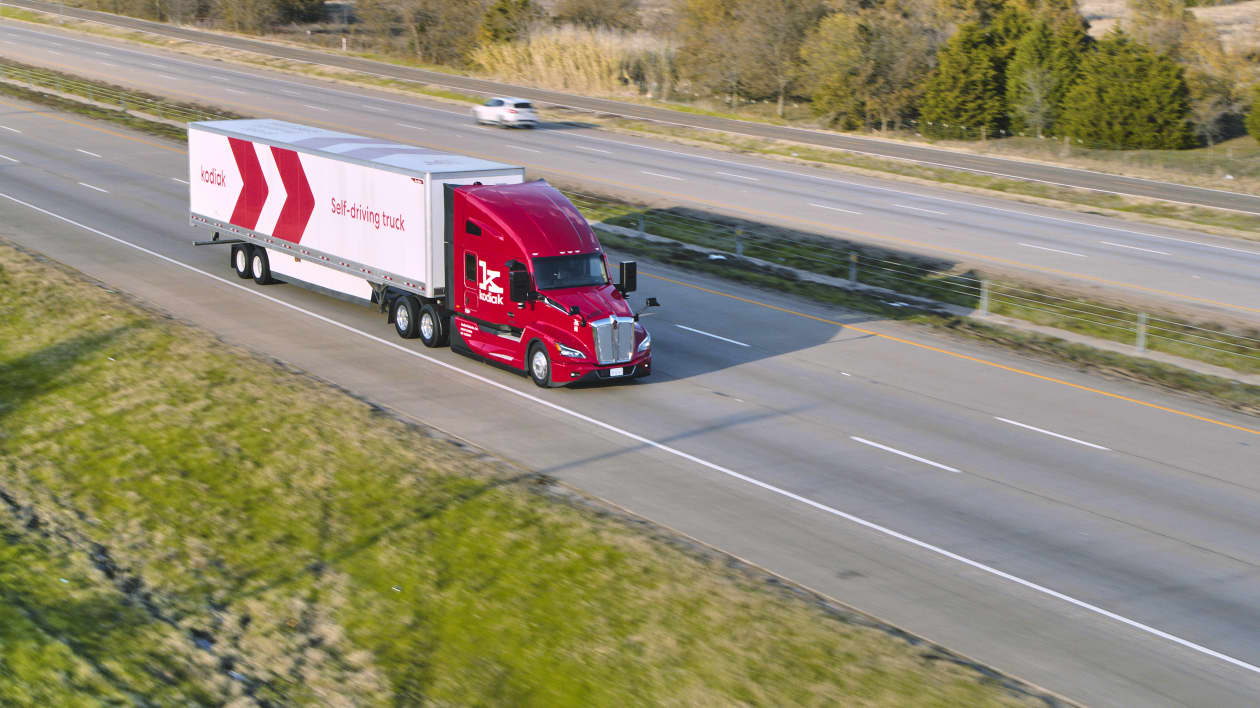
Oppenheimer’s Colin Rusch initiated coverage of Kodiak AI (KDK) with an Outperform rating, arguing the company could be a “long-term winner” in autonomous trucking. He estimates the market Tesla is entering could exceed $160B by 2035 amid a growing U.S. truck-driver shortfall. Kodiak AI shares are rebounding off a record low, signaling improving Wall Street sentiment even as prior investor dismissal lingers.
Analysis
This is primarily a sentiment event, not yet a fundamental inflection. The market is still pricing autonomous trucking as a binary science project, so a coverage upgrade can lift a tiny name like KDK, but the equity only deserves durability if it starts showing repeatable fleet economics: lower cost per mile, high utilization, and a path to funding without serial dilution. In that sense, the real winners are likely the first large fleets and shippers that can arbitrage driver scarcity before the vendors do; the losers are incumbent long-haul carriers and brokers if autonomous capacity compresses linehaul pricing before they can reprice contracts.
Tesla’s planned entry is the bigger second-order effect. It raises the category’s legitimacy, but it also caps KDK’s multiple because a platform with a much larger balance sheet can subsidize deployment, bundle software, and drive down customer acquisition costs. Over 1-3 months, the key catalysts are not analyst calls but proof points: signed pilots converting to multi-year contracts, disclosed safety metrics, and any capital raise. If those don’t show up, today’s rally is likely just a short-covering move.
The contrarian view is that the market is probably overestimating how quickly autonomy moves from hub-to-hub demos to network-scale adoption. That transition is measured in years, not quarters, and the path likely favors narrow geographies and premium freight first. The thesis breaks if Tesla delays entry, if KDK cannot fund its runway without punitive dilution, or if a meaningful fleet customer refuses to renew after a trial. If KDK does secure a top-tier fleet commitment before the next earnings print, the setup changes materially; otherwise the stock remains a trading vehicle, not an investment case.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- Avoid chasing KDK after the analyst-led bounce; treat it as a trading name until there is a signed multi-year fleet contract or a clear path to non-dilutive funding. Highest risk is a financing overhang within the next 1-2 quarters.
- For a cleaner 6-18 month expression of autonomous-trucking upside, prefer a small TSLA call-spread position over KDK common; Tesla has balance-sheet optionality and broader commercial distribution if it enters the category.
- If KDK rallies further on no new commercial proof, consider a tactical short or put-spread against the move into the next earnings/capital-markets window; the key downside catalyst is dilution, not technology failure.
- Watch freight-sensitive names for second-order beneficiaries: JBT/CHRW-style logistics and shipper proxies could gain if autonomous linehaul eventually lowers cost per mile, but this is a multi-quarter/annual story rather than an immediate trade.
- Set a falsifier on KDK: if the company does not announce at least one material fleet expansion or meaningful reduction in burn by the next reporting cycle, the long thesis should be downgraded to avoid value-trap exposure.
More News
- Tesla’s big AI gamble puts its EV business under a microscope
- Retension Pharmaceuticals prices IPO at $12 per share on Nasdaq
- Trump gives top US science awards to Elon Musk and other tech executives
- Paul Graham says Amazon's AI-agent ban opens the door to a new rival
- SpaceX Is Worth About $800 Billion More Than Tesla on Less Than a Quarter of Its Sales
- Why is T-Mobile stock tumbling today?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance
- Can Hedge Funds Use ChatGPT? A Control Framework