
Oceania Cruises® Floats Out Oceania Sonata™, Marking Major Construction Milestone for First Ship in New Sonata Class
Source: PR Newswire
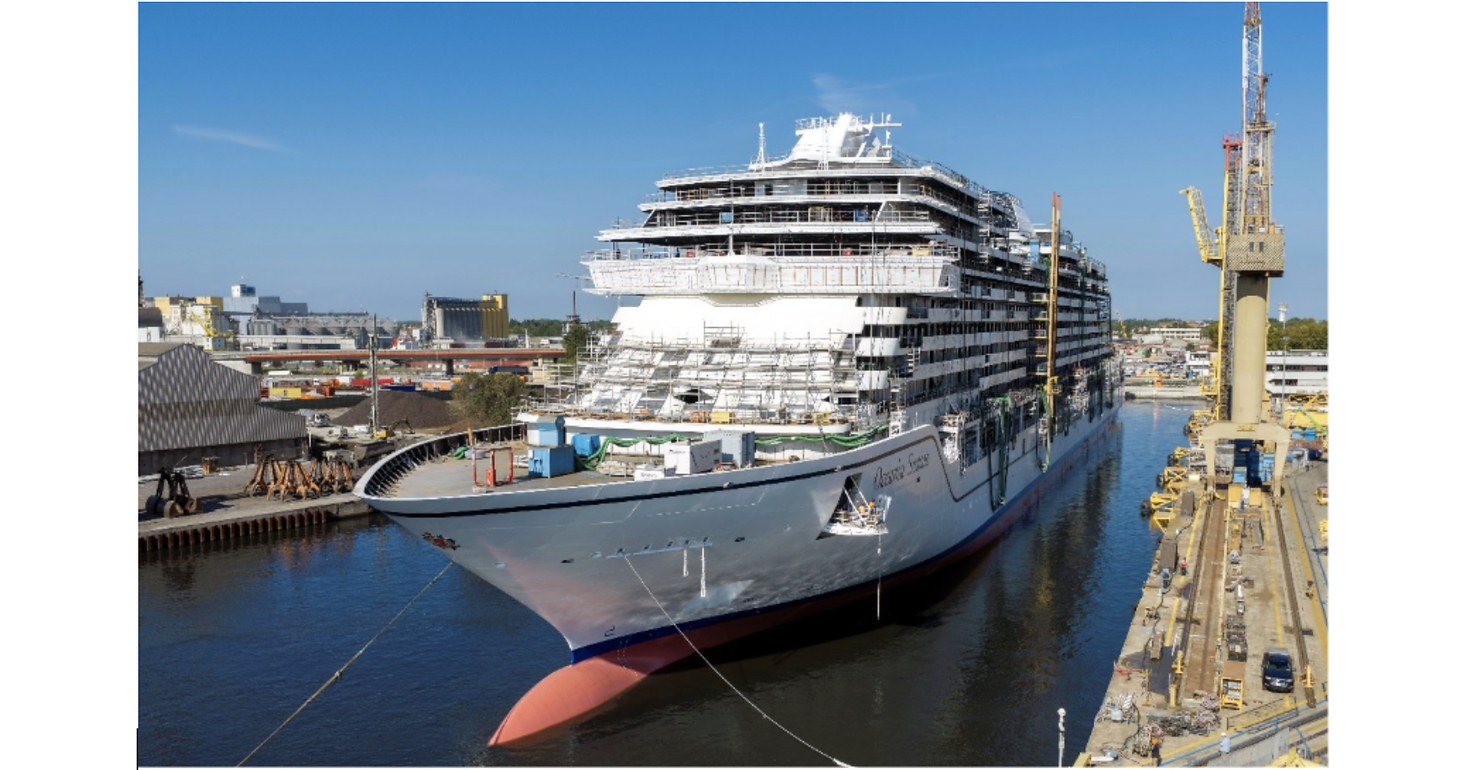
Oceania Cruises floated out its new flagship Oceania Sonata at Fincantieri’s shipyard, advancing construction ahead of an August 2027 debut. The ~86,000 gross ton ship will launch as the first of the Sonata Class, with 695 rooms/suites and about 30% more tonnage than Oceania Allura while adding only 90 guest accommodations. The company also disclosed a rollout of five Sonata Class deliveries (2027, 2029, 2032, 2035, 2037) and new dining and suite concepts, supporting an upbeat forward-looking brand capex cycle.
Analysis
The signal here is less about one ship and more about whether NCLH is still comfortable funding a long-duration premiumization strategy. Incremental capacity that adds relatively few additional berths to a much larger hull is a tell that management is aiming for yield, not volume; that matters because luxury cruise economics are driven more by per-passenger pricing and onboard spend than by occupancy alone. The second-order benefit is to NCLH’s brand mix versus mass-market cruise peers: if Oceania keeps deepening its suite-heavy offering, it should support a higher implied terminal multiple for the luxury segment even if the core fleet is unchanged in the near term.
Near-term EPS impact is basically nil; the real catalyst path runs through booking trends, pricing, and how the market interprets NCLH’s capex burden over the next 1-3 quarters. The risk is that investors extrapolate a strong long-dated order book into current demand, when the actual constraint is leverage and free cash flow discipline if consumer spending softens. A recession or travel-downshift would not hit this specific ship until well later, but it would matter if the market starts discounting future utilization or forcing discounting in the luxury channel.
Contrarian view: the consensus may see ‘confidence’ here, but ship additions are also future supply. If the broader cruise industry stays aggressive on berth growth, pricing power could normalize in 2028-2030 and compress the very premium that luxury brands trade on. That makes this a useful confirmation of strategy, but not necessarily a buy signal on its own without corroboration from booking and yield data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- Prefer a modest long NCLH / short CCL pair over an outright long: NCLH has the cleaner premium-mix story and better long-dated yield support, while CCL remains more exposed to price-sensitive demand; use a 3-6 month horizon and cover if NCLH underperforms CCL after the next booking update.
- Do not chase NCLH solely on this announcement; wait for quarterly commentary on net yield, occupancy, and leverage before adding risk. The article is supportive, but the earnings impact is deferred by years, not quarters.
- If looking for an options expression, consider a small NCLH call spread into the next earnings release only if management reaffirms booking strength and free-cash-flow guidance; otherwise the implied move likely outweighs the news value.
- Set a watch item on cruise-sector supply growth and consumer-spend indicators: if booking lead times shorten or discounts widen, the premiumization thesis for NCLH weakens quickly and the trade should be cut.
More News
- US forces disable ship ‘attempting to run’ Iran blockade in Gulf of Oman
- Attack on Saudi airport kills 12 people and wounds more than 300—the deadliest strike in any Gulf Arab country since the start of the Iran war
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Ship captains and crews transiting the Strait of Hormuz make so much danger pay that they’re ‘almost being viewed as mercenaries’