
Electronic Storage Corporation Announces iSCSI Support for the LaserVault ViTL Virtual Tape Library for IBM i
Source: PRWeb
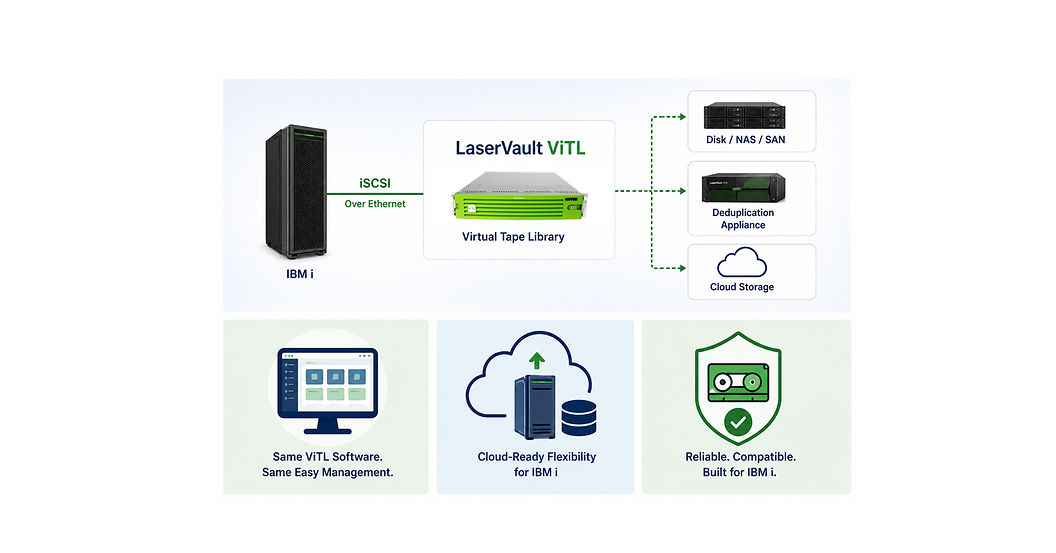
LaserVault launched iSCSI connectivity for its ViTL virtual tape library, enabling IBM i systems to use standard Ethernet rather than specialized Fibre Channel or SAS hardware across on-premises, cloud, and hybrid deployments. Initial testing delivered roughly 380-400 MB/s on a single 10GbE connection and about 600 MB/s aggregate throughput with two simultaneous virtual tape drives. The feature can coexist with Fibre Channel and preserves existing IBM i backup and recovery workflows, but the announcement is a niche product update with limited broader market impact.
Analysis
This is not a material IBM earnings catalyst: LaserVault is a private niche vendor, and the addressable installed base is mature. The relevant read-through is incremental reduction in deployment friction for IBM i workloads, which can modestly improve retention and modernization economics rather than create meaningful new Power Systems demand. The more important second-order effect is that Ethernet-based backup can lower the cost of hybrid disaster-recovery architectures, reducing the incentive for smaller IBM i customers to undertake disruptive platform migrations.
Competitive pressure falls primarily on Fibre Channel/SAS attachment and specialized backup-hardware vendors at the low end of the IBM i market, but the revenue pool is too small to support a broad storage-equipment short. Standard Ethernet also shifts more of the value stack toward server, virtualization and cloud-storage capacity; however, the stated throughput is configuration-dependent and does not establish a differentiated performance moat versus incumbent virtual-tape offerings. Near term, this is a sales-enablement feature, not evidence of a demand inflection.
For IBM, the investable catalyst remains whether easier hybrid backup correlates with Power Systems refreshes, software attach, or managed-services growth over the next 1-3 quarters. A constructive signal would be commentary on IBM i renewal rates, Power infrastructure revenue stabilization, or increased hybrid-cloud bookings from midmarket customers. The thesis is falsified if the feature is offered without pricing power, customer references, or any improvement in IBM's infrastructure trajectory; absent those data, the likely equity impact is immaterial.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No standalone IBM trade on this release; treat it as a low-signal product-enablement datapoint rather than a revenue catalyst.
- Maintain IBM only within a broader hybrid-infrastructure or AI-services thesis; reassess after the next two earnings reports for Power Systems growth, infrastructure software attach and IBM i retention commentary.
- Set a watch alert for independently disclosed LaserVault customer wins, pricing changes, or IBM channel partnerships. A disclosed enterprise migration avoided or Power refresh tied to the capability would improve the read-through; absent such evidence, do not underwrite incremental IBM revenue.
- Avoid shorting storage/networking peers on this news: any substitution away from specialized connectivity is likely fragmented, slow-moving and too small to overcome company-specific demand drivers.
More News
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- Asian stocks rise as oil retreat eases inflation fears, BOJ in focus
- California AG Bonta on Paramount-Warner Bros., Meta and AI
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”
- Jensen Huang says Nvidia will sell twice as many chips next year
- Waymo to launch robotaxis in Singapore, its first Southeast Asia market, by 2028