
DAVID WEEKLEY HOMES NAMES NEW CFO AND ADDS CMO TO LEADERSHIP TEAM
Source: PR Newswire
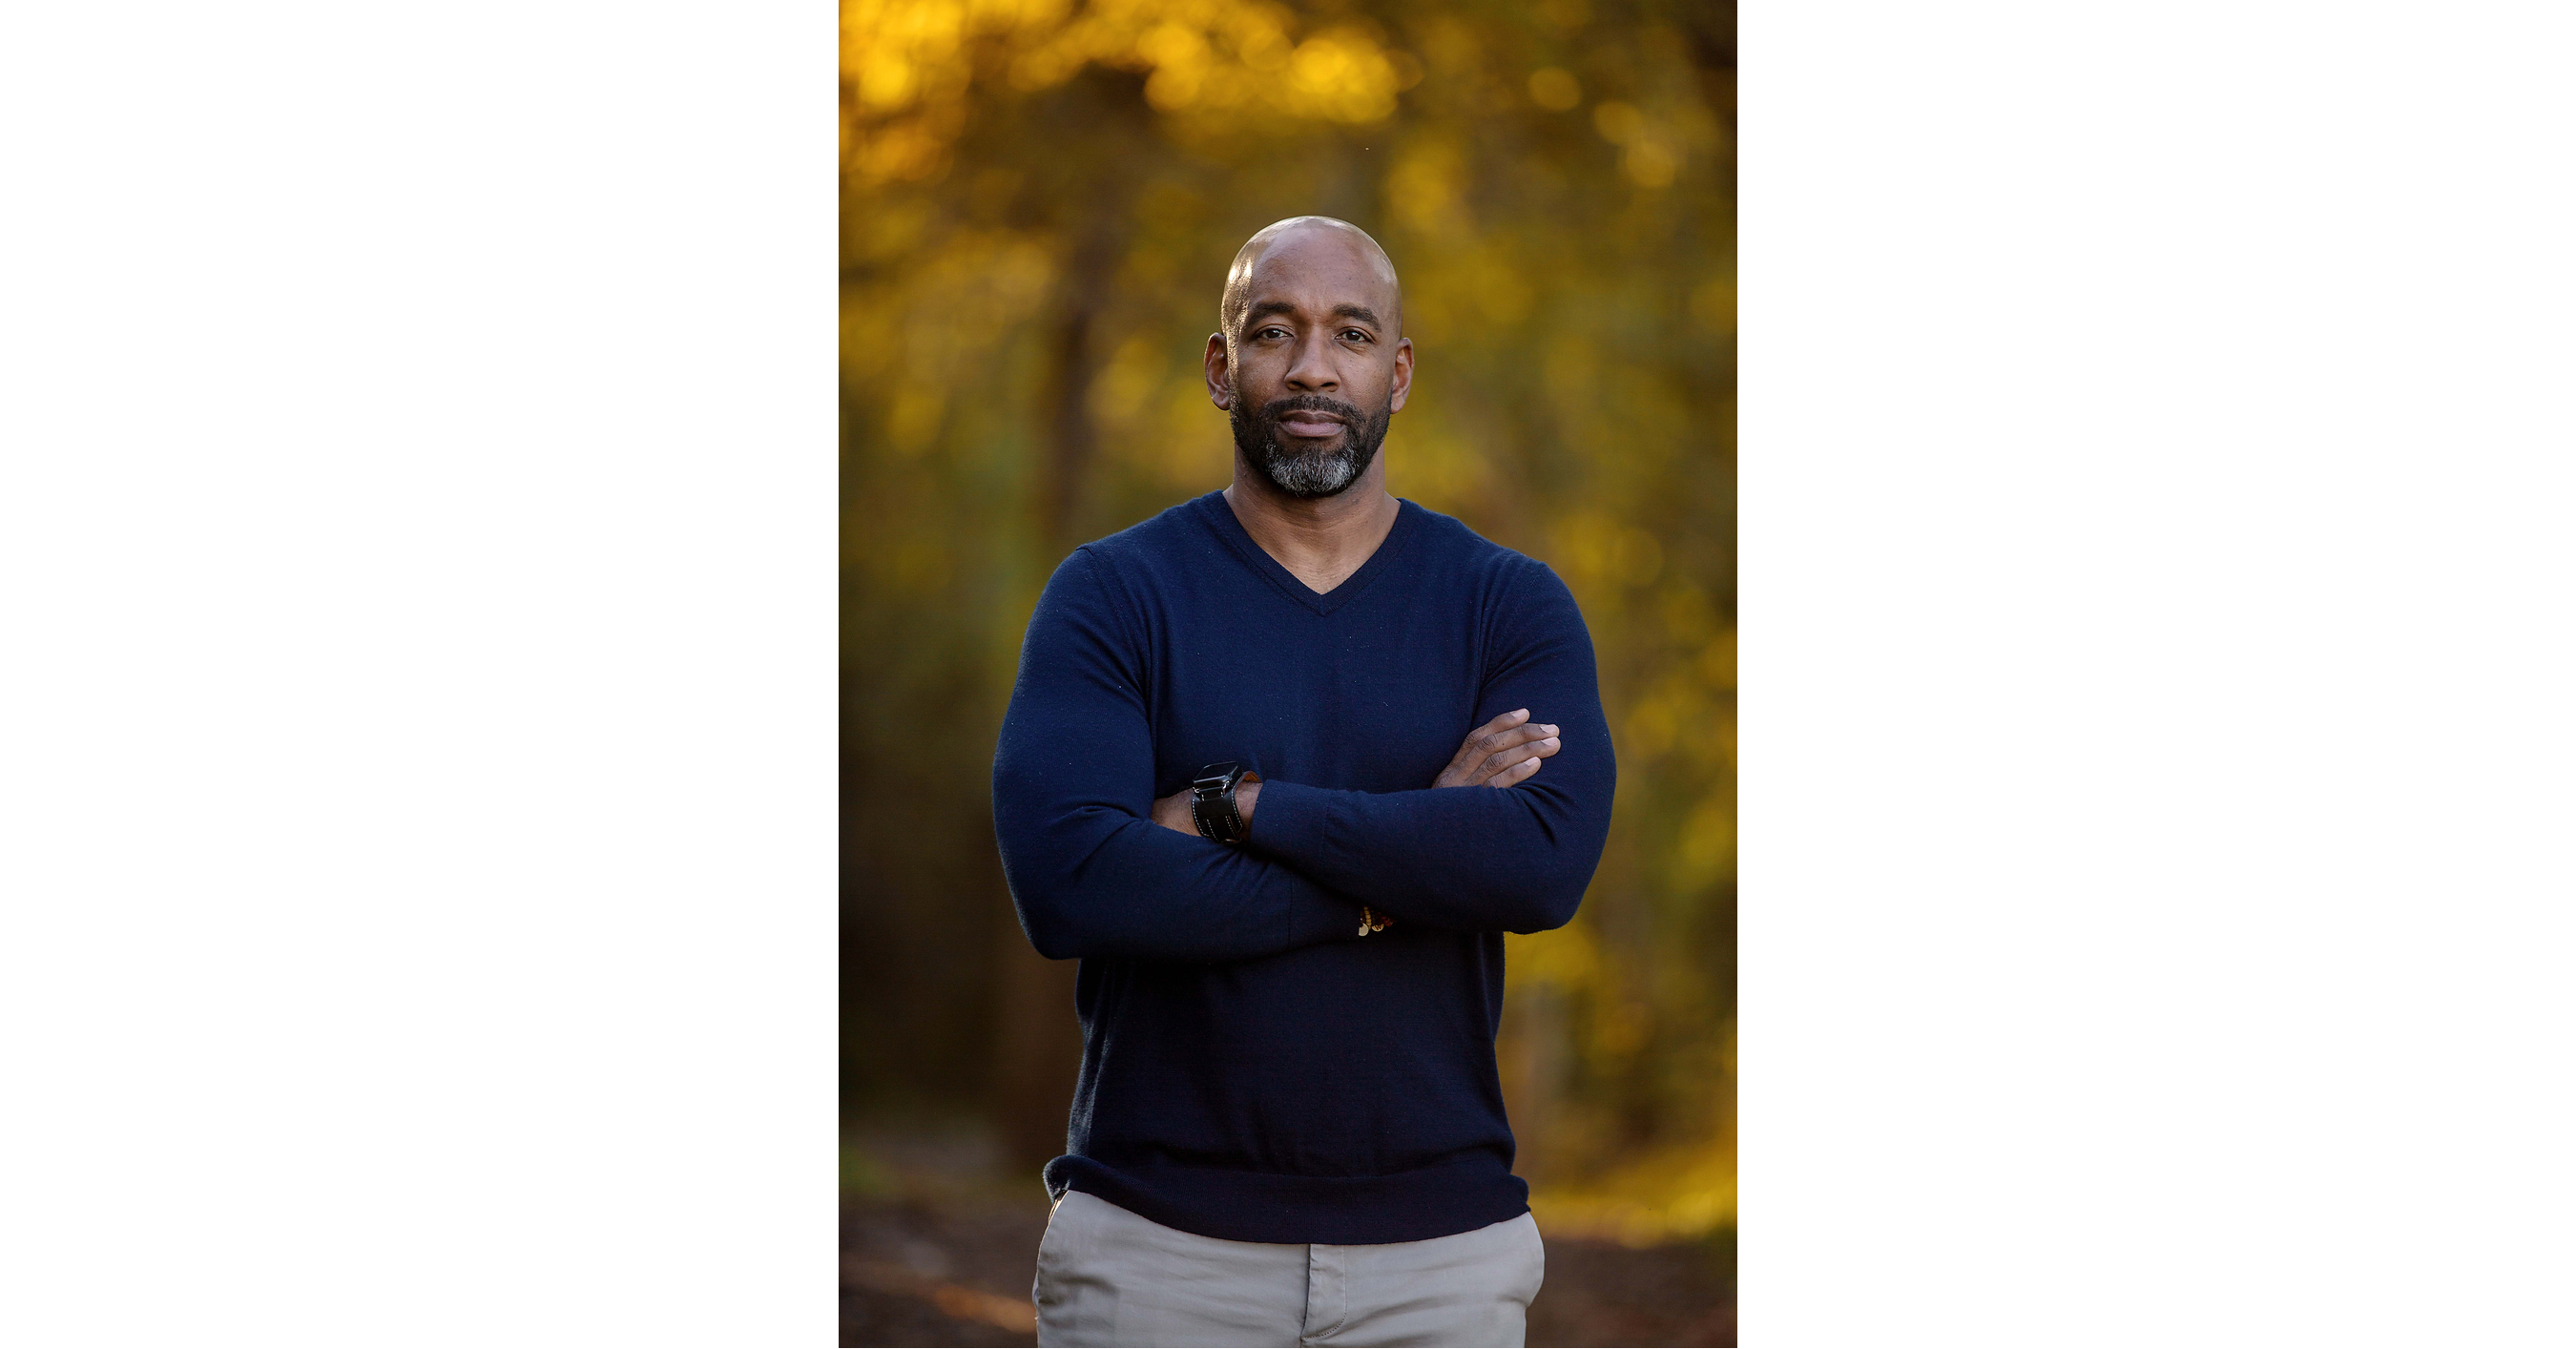
David Weekley Homes added Adam Zylman as Chief Financial Officer and Julian Duncan as its first Chief Marketing Officer, bringing private equity/investment banking experience and major-brand marketing backgrounds (Houston Rockets, Nike, Under Armour). The company also announced long-time CFO/CIO Heather Humphrey will retire after 33 years, with a transition supported through advisory involvement. Overall, this is a leadership and strategy-refresh news item with limited immediate implications for earnings or market prices.
Analysis
This is a low-signal governance/operating hire for a private builder, not a near-term catalyst for listed housing equities. The only real market mechanism is that Weekley appears to be importing brand-building and capital-allocation talent, which suggests the premium end of new-home demand is getting more competitive on customer experience, not just land availability. If that playbook works, it can quietly pressure public builders to spend more on sales, incentives, and CRM to defend absorption, with the most exposed names being the ones already leaning on discounting to keep pace.
The second-order winner is likely the highest-quality, most disciplined operator in the public cohort rather than the obvious marketing-heavy names; NVR should be better positioned if the industry shifts toward execution and conversion efficiency. The losers are lower-flexibility builders where SG&A leverage is already stretched, because a modest pickup in customer-acquisition spend can flow straight to margin. That said, this is a months-to-quarters story, not a days-to-weeks trade, and it is easily overwhelmed by mortgage-rate moves, which remain the dominant driver of order velocity.
Contrarian view: the market will overread the executive bios as signaling a meaningful inflection in Weekley’s growth. In housing, branding is usually a second-order tool; a 25-50 bps move in rates or a change in incentive intensity will matter far more than a new CMO. The thesis is falsified if public builders continue to show stable conversion and no SG&A inflation over the next 1-2 earnings cycles, or if lower rates restore demand enough to make brand spend irrelevant.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.08
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in NKE/UAA or homebuilders from this item alone; treat the announcement as informational, not actionable, until next-quarter builder commentary confirms higher customer-acquisition spend.
- Set a watch item on DHI, LEN, and TOL upcoming earnings for SG&A as a % of revenue and incentive trends; if sales expense rises without order growth, consider a 3-6 month short XHB expression.
- Relative-value idea: long NVR / short XHB on a 1-3 month horizon if mortgage rates stay range-bound and public builders start leaning harder on incentives; risk/reward is favorable because NVR is least likely to need incremental marketing to defend margins.
- If you want a cleaner catalyst trade, wait for evidence of margin pressure first, then short LEN or TOL into the next print; stop out if orders accelerate or 30-year mortgage rates fall decisively below the current range.
More News
- Nike's India campus is a long-term growth bet amid turnaround
- Tesla's Roadster reveal, Apple and Meta team up, Nike's India push and more in Morning Squawk
- Nike Walked Away From Foot Locker. It Never Got That Shelf Space Back.
- Jordan is driving Nike's resale volume growth: buy NKE stock?
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Best AI Stock Research Tools for Professional Investors
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More