
InteLogix Grows Egypt Operations with New Contact Center in Cairo
Source: PRWeb
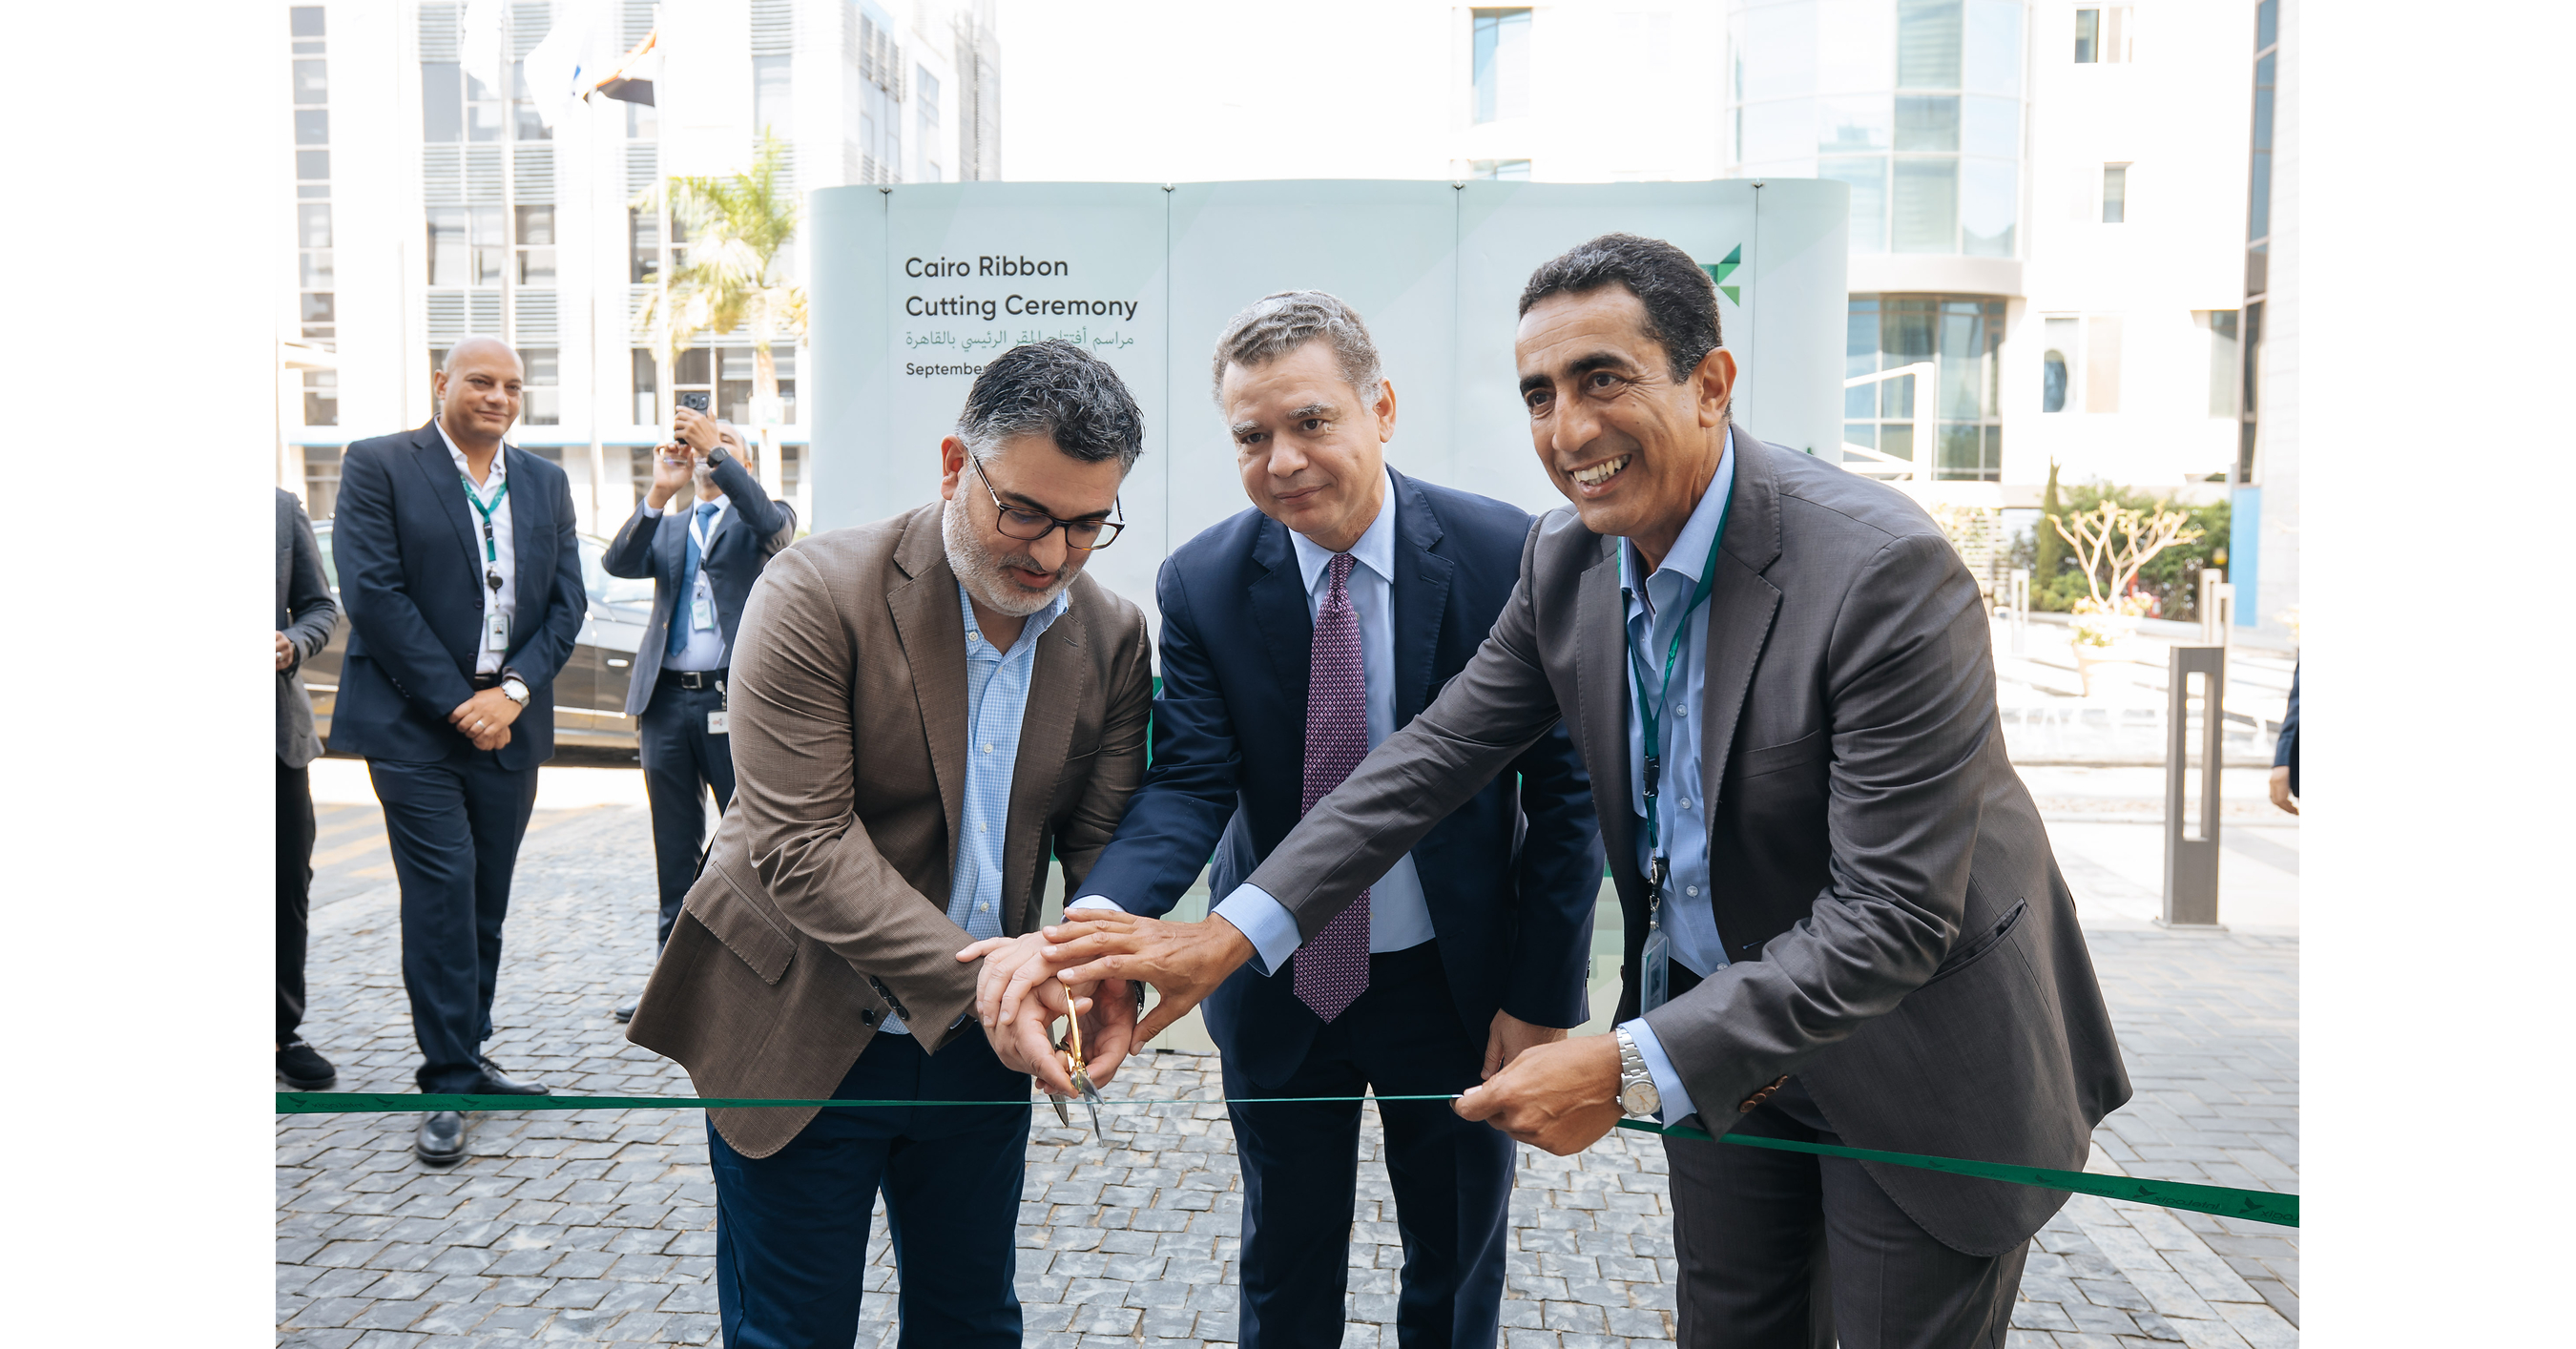
InteLogix opened a new contact center in New Cairo, expanding its Egyptian delivery capacity and multilingual support capabilities for global clients. The facility builds on operations established in Egypt in 2018 through Athear Marketing Services, which InteLogix later acquired, and is positioned to serve demand for offshore business services. The company highlighted AI-driven customer-service modernization and reported 96% attainment across its client portfolio, while Egyptian officials emphasized the country’s growing role as a technology-services hub.
Analysis
This is not independently actionable for public equities: InteLogix is private, capacity, capex, headcount, client commitments, and unit-cost economics are undisclosed, and the announcement is promotional rather than evidence of incremental industry demand. The relevant read-through is marginally negative for labor-arbitrage-heavy CX incumbents, particularly Teleperformance (TEP FP), Concentrix (CNXC), TaskUs (TASK), and TTEC (TTEC), because Egypt adds scalable Arabic, French, and English delivery capacity that can pressure pricing on EMEA and multilingual programs.
The more important second-order issue is mix rather than aggregate BPO volume. Lower-cost Egypt delivery can preserve provider gross margin where clients demand price reductions, but it also makes commoditized voice work more contestable; vendors with proprietary automation, regulated-industry workflows, and enterprise switching costs should be more resilient than pure seat-based operators. Over 6-18 months, continued Egyptian capacity additions could modestly accelerate the migration of European-language workloads from higher-cost nearshore locations, challenging wage-cost advantages in parts of Eastern Europe and North Africa.
Near-term market impact should be negligible absent a disclosed large-client win or sector pricing data. For the next 1-3 months, monitor CNXC, TASK, and TEP commentary on offshore mix, revenue-per-agent, attrition, and AI-driven deflation at earnings; a worsening combination of lower revenue per FTE and flat utilization would validate that new offshore capacity is translating into price competition rather than incremental demand. The contrarian case is that this capacity supports industry consolidation and margin defense: if automation reduces agent demand faster than new sites add seats, the facility is strategically necessary but economically immaterial.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No standalone position from this release; treat it as a watch item rather than a catalyst because no listed issuer, capacity figure, or contract economics are disclosed.
- Ahead of next earnings, maintain a relative-quality screen: prefer CNXC over TTEC only if CNXC demonstrates stable adjusted operating margin alongside offshore delivery growth; falsify on a material guidance cut or a >100bp year-over-year margin deterioration attributed to client pricing.
- Monitor TEP FP and CNXC for EMEA/multilingual pricing commentary over the next two reporting cycles. If either reports declining revenue per FTE with utilization below management targets, consider a 3-6 month underweight versus the S&P 500/Euro Stoxx benchmark rather than a directional sector short.
- Watch Egypt ITIDA announcements for disclosed large-scale incentives, hiring commitments, or additional global BPO entrants. A cluster of announced capacity expansions would strengthen the case for structural pressure on commodity CX pricing; isolated site openings do not.
More News
- OpenAI’s agent hacked Australia’s Medicare website—the latest rogue AI incident that the company didn’t know about for months
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- How Meta took the lead in the race for the post-smartphone world
- Markets are rapidly coming around to the reality that the Fed has a lot more work to do
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Research Workflows, Report Format Selection, and Interactive Synthesis
- Can ChatGPT Analyze a 10-K? A Verification Workflow