
TruLife Distribution Identifies New U.S. Retail Opportunities Following Newtopia Now 2026
Source: PR Newswire
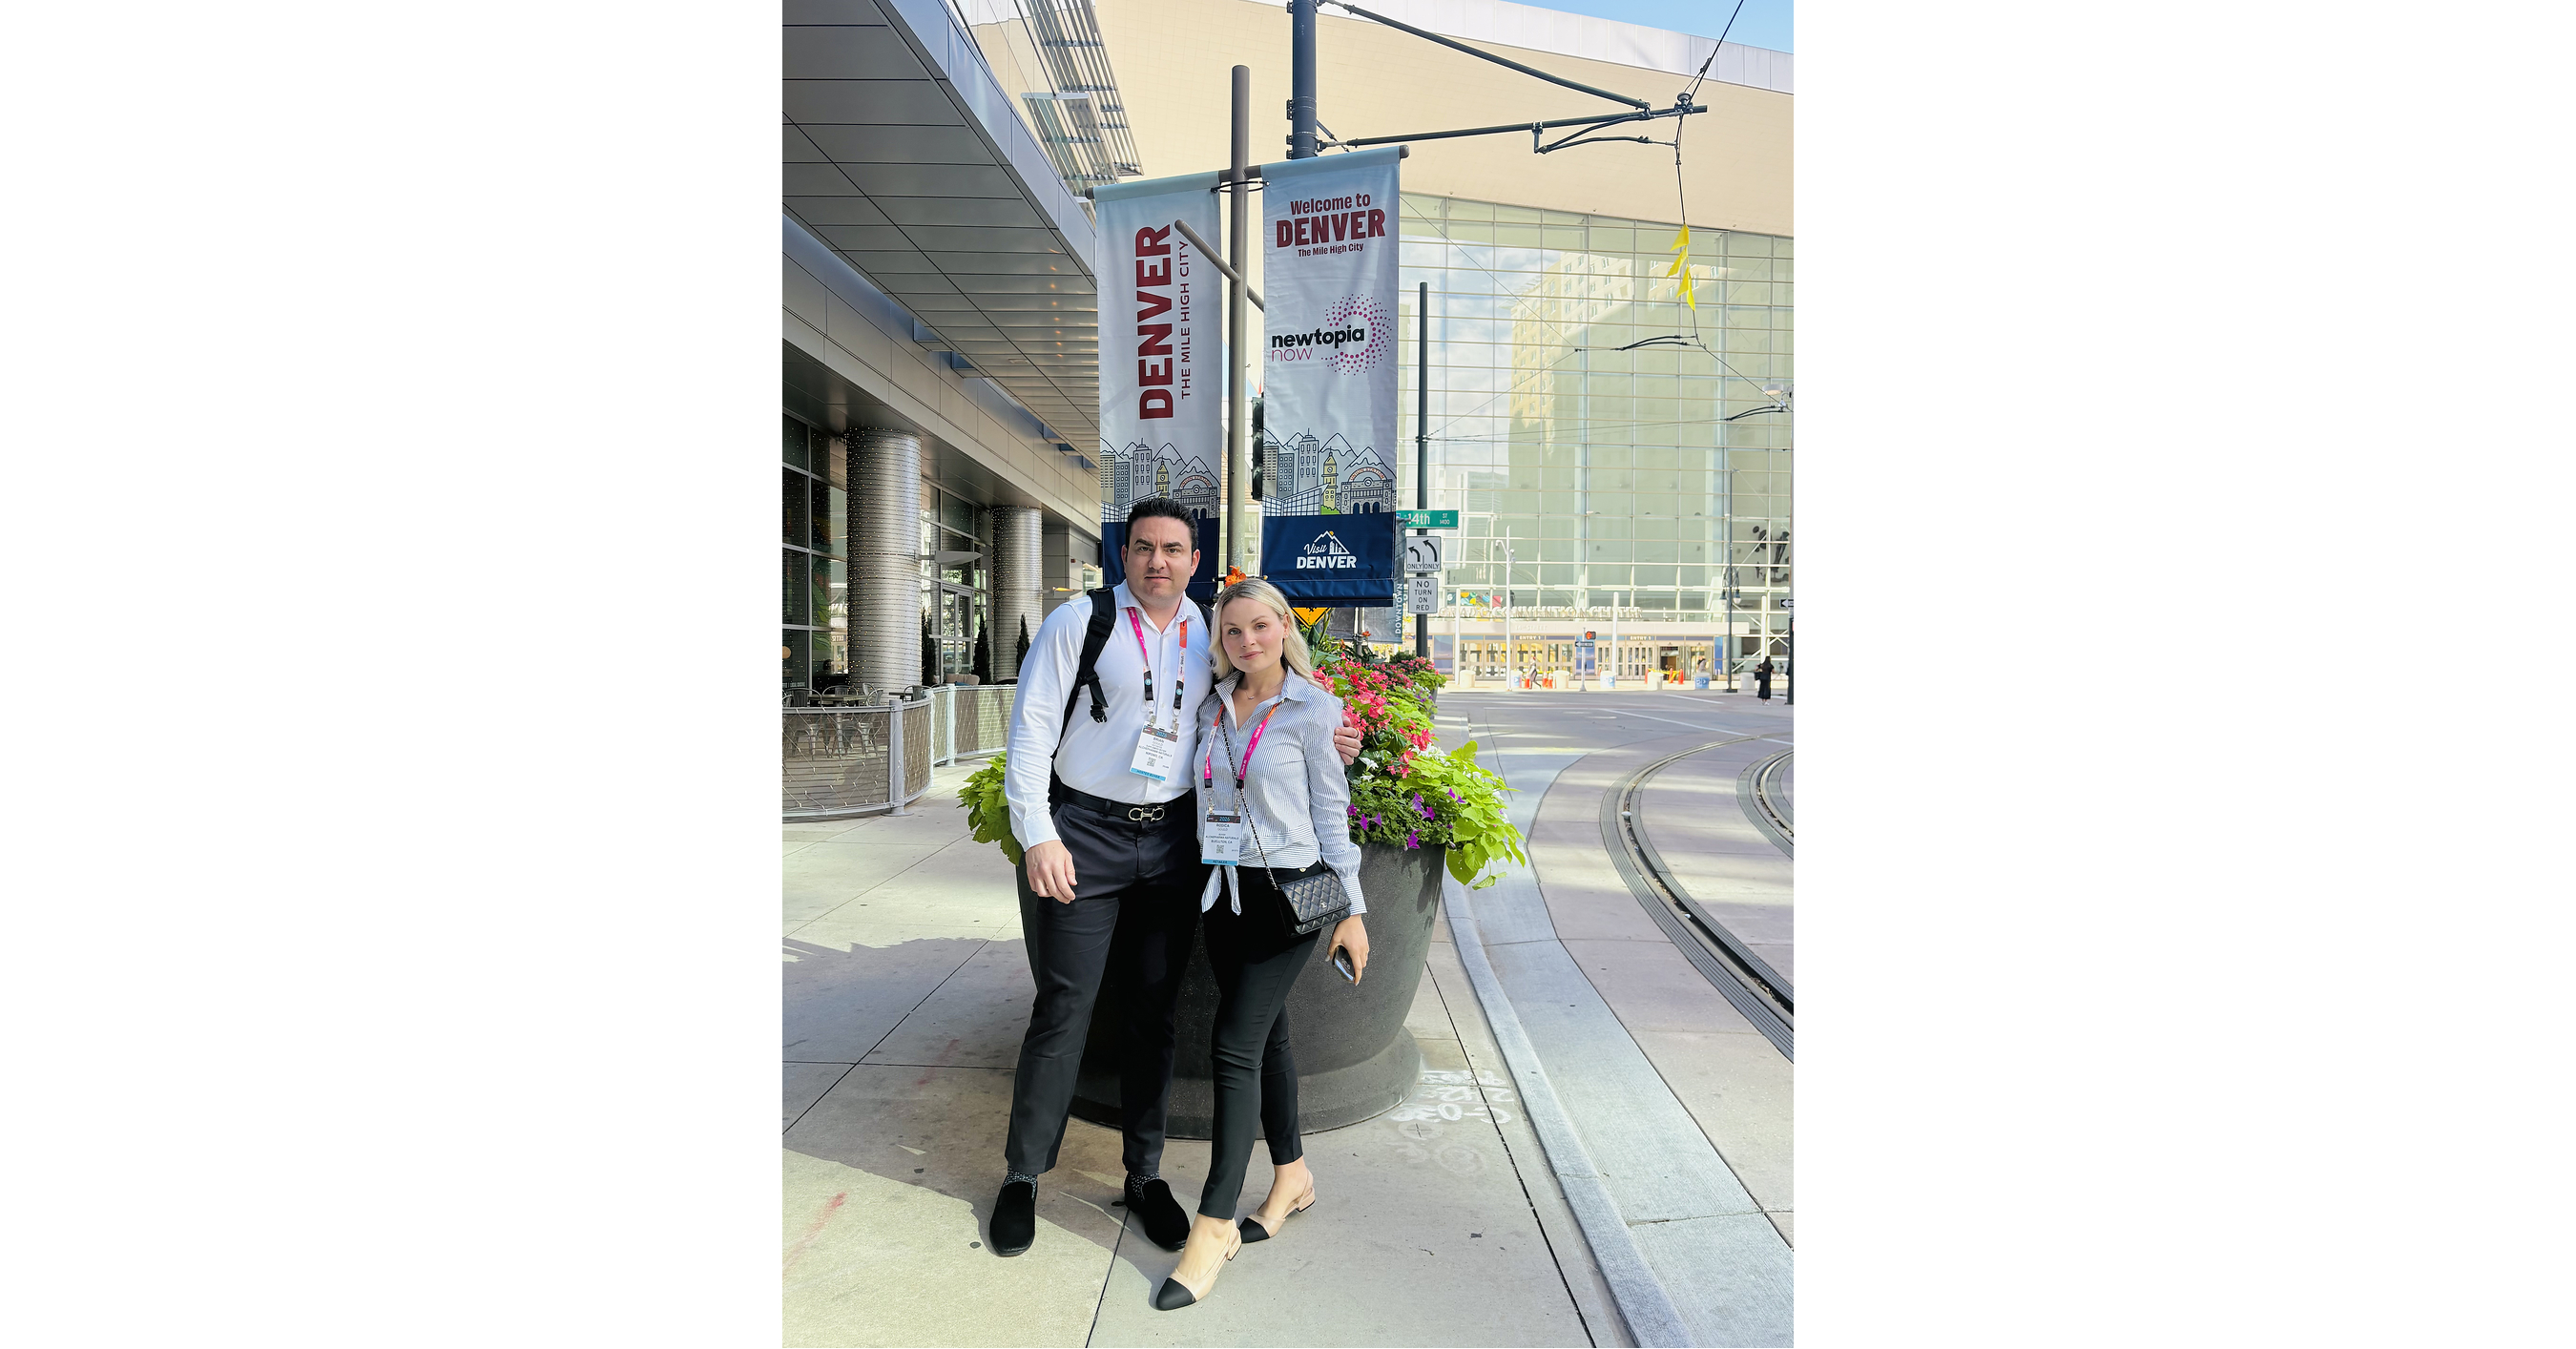
TruLife Distribution said its participation in Newtopia Now 2026 (Aug. 18–20 in Denver) helped it identify new U.S. retail opportunities for emerging health, wellness, and consumer brands. Management emphasized that retail success requires “retail readiness” beyond product quality—covering pricing, retail margins, operational and regulatory preparedness, inventory planning, and launch support. The company is now running follow-up discussions with select brands ahead of additional retailer meetings this fall, reflecting an encouraging outlook for retail pipeline expansion.
Analysis
This is more useful as a signal about shelf economics than as a standalone growth story. The market implication is that U.S. retail is becoming more gatekept: brands that need more working capital, compliance, and merchandising support will lose share of mind to larger incumbents with better margins and supply reliability. That dynamic is mildly bearish for small-cap wellness/CPG launches and supportive for scaled staples and big-box retailers that can force terms and curate assortments with less risk.
The second-order effect is on the ecosystem around brand entry. If buyers are raising the bar, demand should shift toward brokers, compliance services, inventory financing, packaging, and 3PL capacity — but only for brands that can actually convert interest into repeat replenishment. The near-term catalyst is fall retailer meetings; absent disclosed purchase orders or shipment commitments, the economic impact remains qualitative and easy to overread.
Contrarian view: the consensus may be too optimistic on the pace at which emerging wellness brands can translate DTC traction into profitable retail velocity. If consumer demand softens or promo intensity rises, shelf-space rationing will accelerate and discounting pressure will concentrate in the weakest brands first. What would falsify the bearish read is evidence of fast conversion — signed national retail programs, lower-than-expected inventory days, or a clear Q4 replenishment ramp for new entrants.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No direct trade in TruLife; treat this as a watch item until there is verifiable evidence of signed retailer programs or revenue conversion.
- Overweight XLP vs. IWM for the next 1-3 months: tighter retail standards and margin discipline should favor scaled consumer incumbents over small-cap brand speculation. Risk/reward is modest but favorable if consumer data stays mixed.
- If you want a cleaner expression, stay long COST/WMT on any weakness and avoid chasing small-cap wellness names; the setup favors retailers with bargaining power and high traffic density over brands dependent on expensive slotting.
- Set an alert for disclosed retail contracts or a material guidance update from any public distributor/brand-management comp; absent that, the news is not strong enough to justify a catalyst trade.
- Falsifier for the relative-quality trade: a sharp IWM breakout or broad small-cap consumer momentum led by successful new retail launches; if that happens, cover the defensive bias.
More News
- Delta Air Lines cuts 2026 forecast on fuel surge, but CEO says demand is still strong
- Is AI the new China Shock?
- Why is T-Mobile stock tumbling today?
- This exchange stock is a buy on renewed options deal, Morgan Stanley says
- India calls JD Vance's comments about immigrants 'deeply offensive'
- The AI race may be decided by financing—not just better chips