
Ensera launches alliance network with SHL Medical, Stevanato Group, Ypsomed, Argonaut and American Injectables
Source: PR Newswire
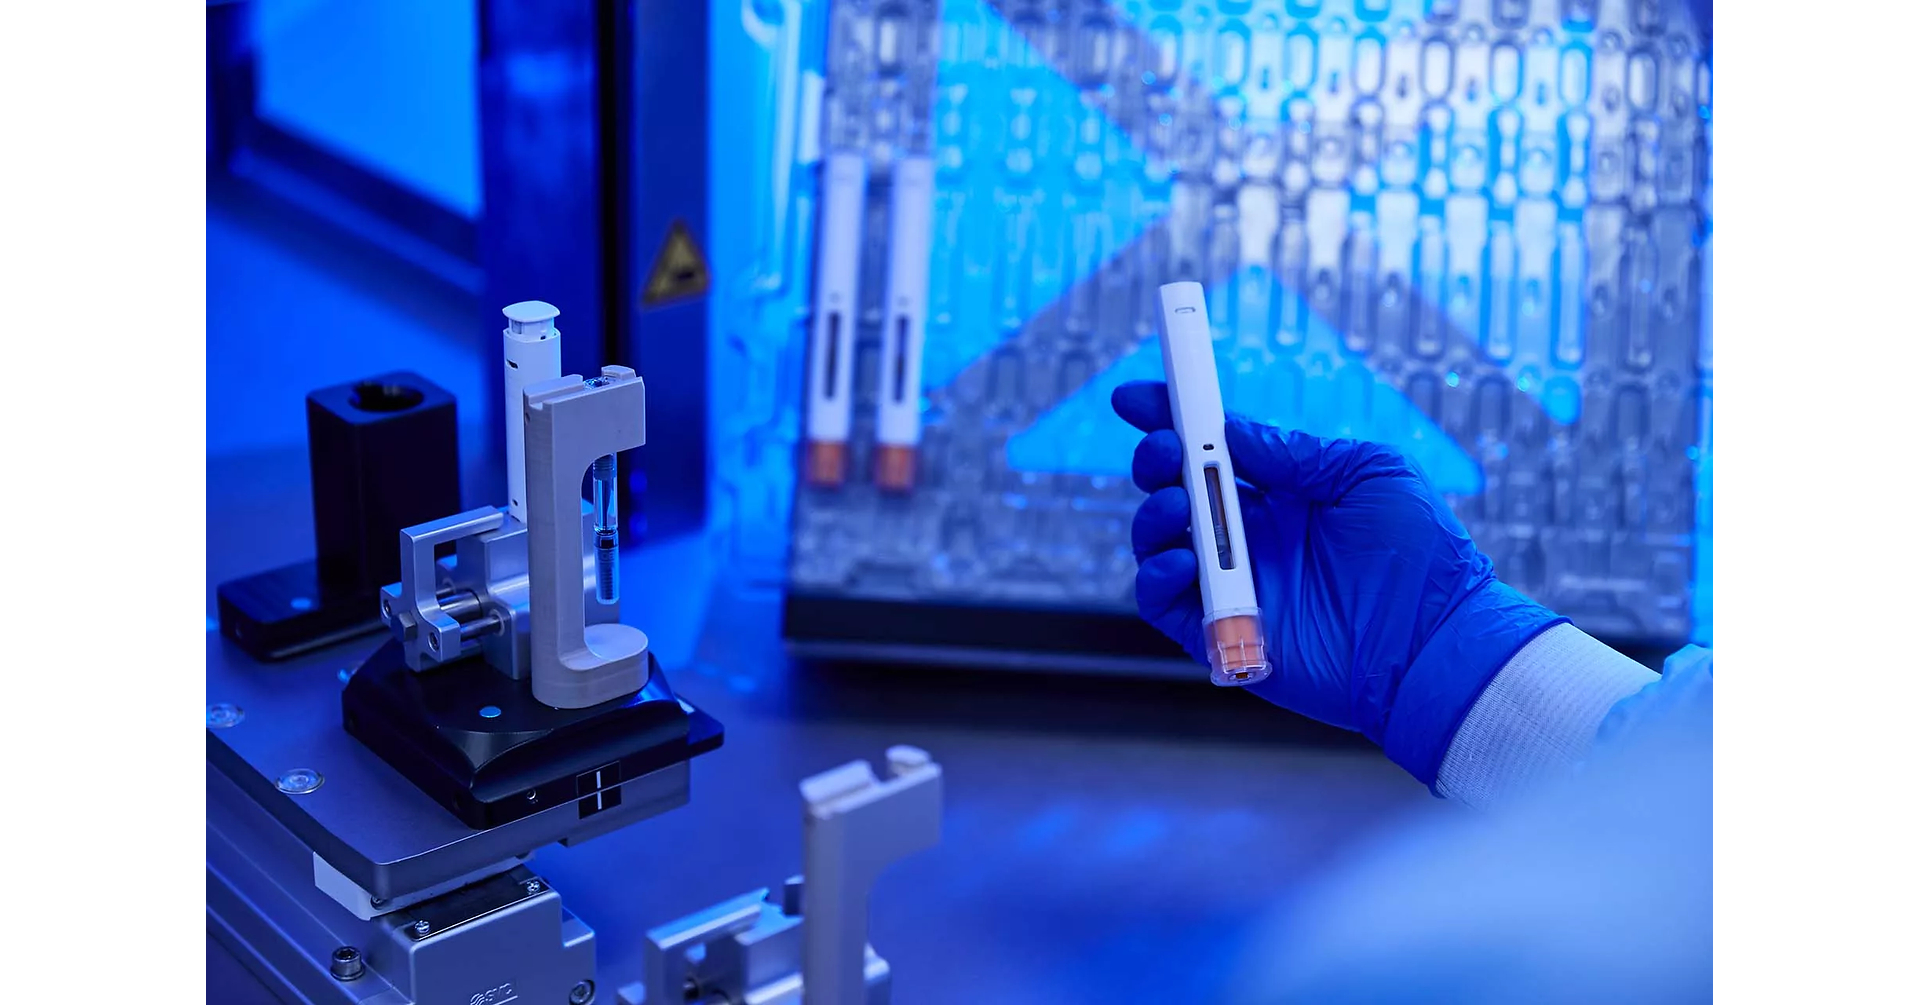
Ensera launched the non-exclusive Ensera Alliance Network, linking injector-platform providers SHL Medical, Stevanato Group and Ypsomed with fill-finish specialists Argonaut Manufacturing Services and American Injectables. The network aims to reduce supplier handoff complexity across drug-device combination product commercialization, including device platforms, fill-finish, final assembly and packaging. Ensera plans to add partners over time, but no financial terms, revenue impact or customer commitments were disclosed.
Analysis
The economic significance for STVN and YPSN is not the alliance itself but whether it improves conversion of injector design wins into recurring commercial component and consumable volumes. Combination-product launch delays are costly for pharma customers, so a coordinated validation and tech-transfer pathway can raise platform stickiness and reduce the risk that a program switches device suppliers late in development. For STVN, the more relevant read-through is potential pull-through for high-value drug-delivery systems and fill-finish content; for YPSN, it supports its installed-base model, where device adoption can create durable recurring consumables demand.
The non-exclusive structure sharply limits immediate revenue inference: this is primarily a commercial-access and execution signal, not evidence of committed capacity, minimum-volume contracts, or pricing power. Ensera's low-to-medium volume orientation may skew the opportunity toward clinical-to-early-commercial programs rather than near-term blockbuster scale, making its effect on either public company's FY27 estimates likely immaterial absent disclosed customer awards. A second-order risk is that improved interoperability lowers supplier-switching friction, potentially increasing competition among injector platforms rather than entrenching incumbents.
Over 6-18 months, injectable biologic and GLP-1 pipeline growth should reward suppliers that can offer validated, scalable device-plus-fill-finish solutions, but the critical constraint is sterile-fill capacity and regulatory execution, not network branding. Watch STVN order intake/backlog conversion, Biopharma Solutions utilization and margin; for YPSN, diabetes-care delivery growth, customer concentration, and any expansion in third-party pharma platform wins. The thesis is falsified if commercial wins do not translate into disclosed volume commitments or if device-platform pricing/margins weaken despite higher program activity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- No standalone event trade on the announcement; treat it as a watch item because there are no disclosed volumes, economics, exclusivity, or capacity commitments.
- Maintain a 6-18 month relative preference for STVN over diversified life-science tools only if quarterly backlog conversion and Biopharma Solutions utilization improve; the upside comes from operating leverage on higher-value drug-delivery and fill-finish mix, while the stop condition is two consecutive quarters of weak order conversion or margin dilution.
- Monitor YPSN for disclosed third-party pharmaceutical platform awards over the next 1-3 quarters; initiate or add only after evidence of commercial-volume commitments, since alliance participation alone does not establish incremental recurring consumables revenue.
- Use a relative-value framework rather than outright exposure: long STVN versus short a broad medtech ETF such as IHI after confirmed drug-delivery order acceleration, with risk capped by closing if STVN's order intake underperforms IHI-sector growth for two reporting periods.
More News
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
- Markets slip on dollar pressure, but this IT stock is up 10% today