
Bitmine Immersion Technologies (BMNR) maakt bekend dat het 5,98 miljoen ETH-tokens in bezit heeft en dat het totale bezit aan cryptovaluta en contanten 17,1 miljard USD bedraagt.
Source: PR Newswire
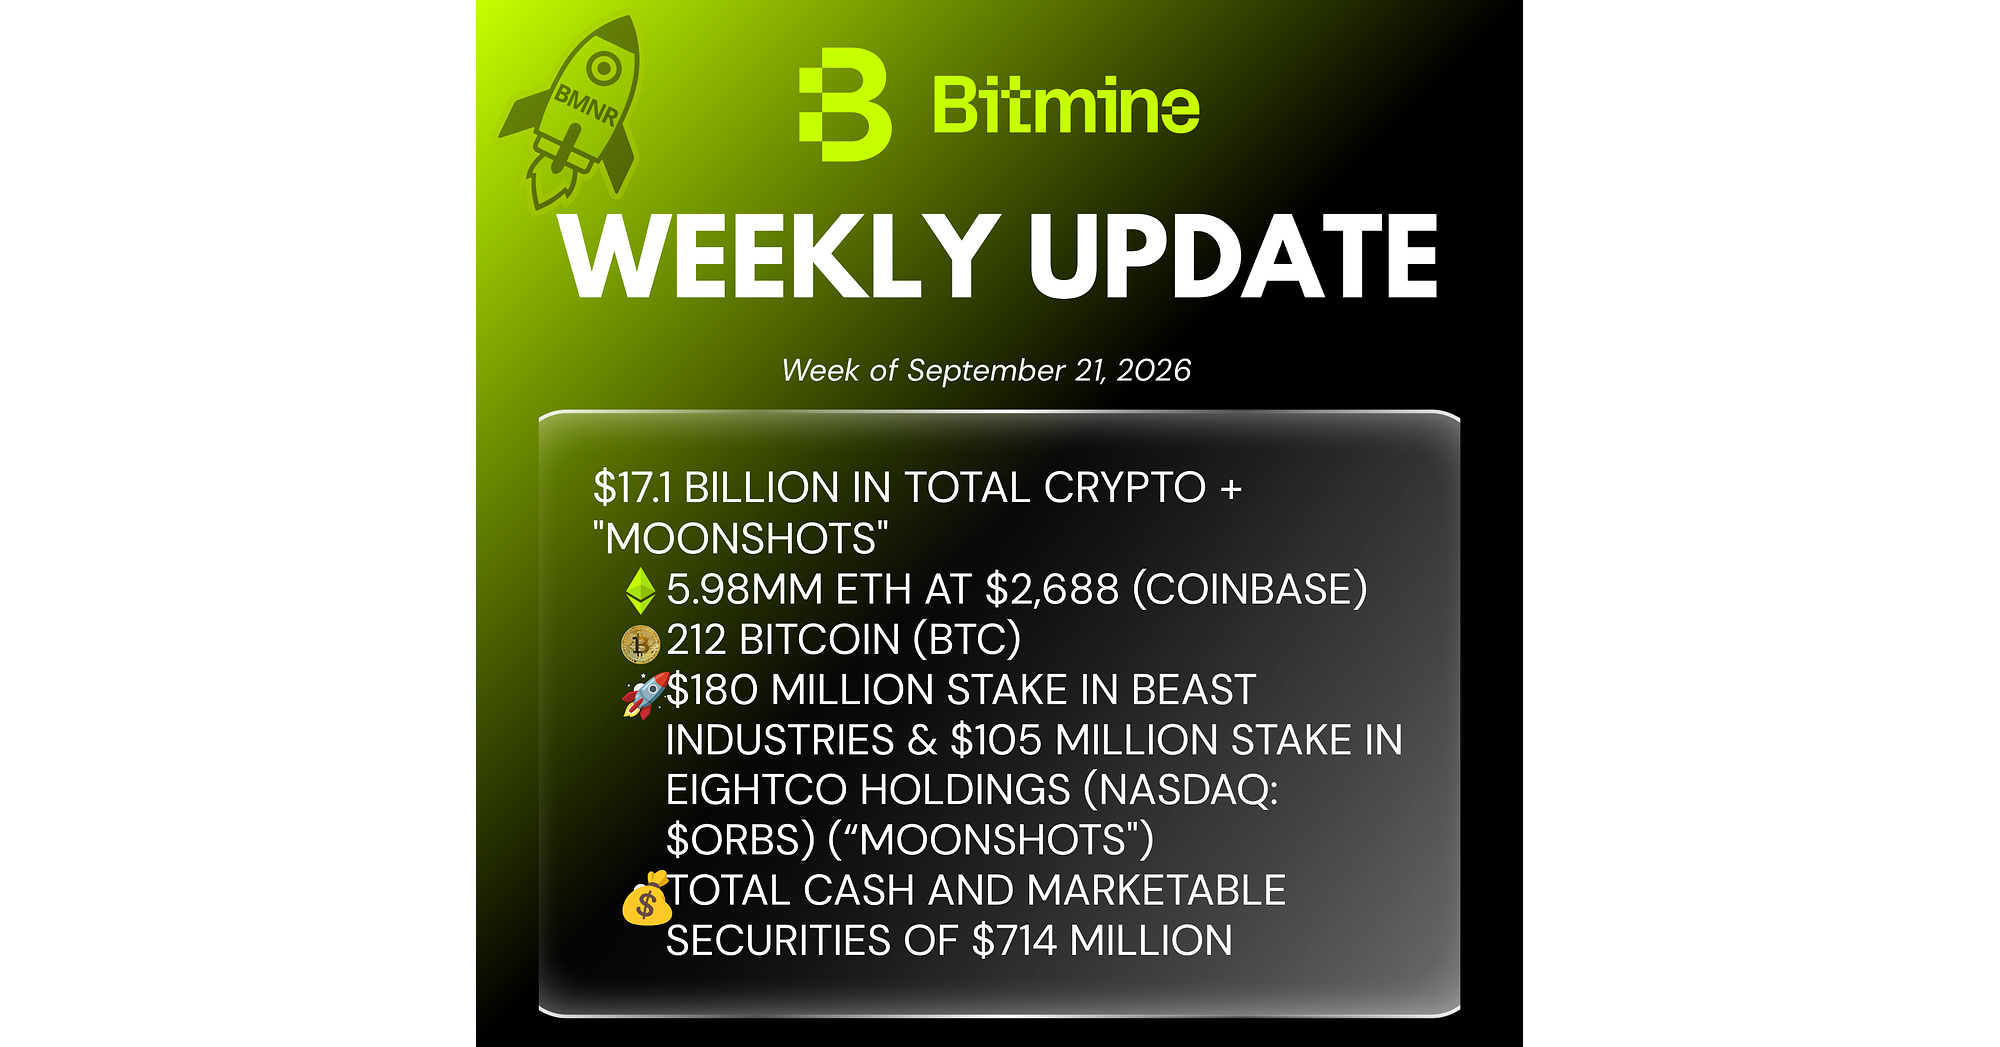
Bitmine reported $17.1 billion in crypto assets, cash, marketable securities and moonshot investments, including 5.98 million ETH worth roughly $16.1 billion and representing 4.9% of Ethereum's 122.1 million-token supply. The company acquired 27,562 ETH during the past week and has staked 5.07 million ETH, or 85% of its holdings, with estimated annualized staking income of $357 million currently and up to $421 million at full scale. Management expects crypto's Q3 strength to extend into Q4, citing ETH's 6,519bp outperformance versus the S&P 500 and anticipated increased institutional crypto allocations.
Analysis
BMNR is increasingly a levered closed-end ETH vehicle rather than an operating-infrastructure equity: its valuation should be governed by the premium/discount to marked NAV, the cost of capital used to fund further accumulation, and ETH beta. The critical reflexive risk is that a persistent equity premium enables accretive issuance and additional token buying, while any discount closes that issuance channel and turns the strategy into a forced balance-sheet de-risking story. With most assets staked, reported NAV is not equivalent to immediately deployable liquidity; validator exits, custody concentration and market depth matter disproportionately in a stress scenario.
The stated staking run-rate should not be capitalized as stable operating earnings. Yield is denominated in ETH, varies with network activity and validator economics, and remains exposed to slashing, protocol changes and execution risk; a lower ETH price simultaneously reduces dollar income and investor willingness to assign a yield multiple. The company’s scale also creates a second-order governance/regulatory risk: a concentrated public-company holder near a psychologically important supply threshold may attract scrutiny even without protocol control, potentially widening BMNR’s NAV discount versus spot ETH and more diversified crypto proxies such as COIN and GLXY.
Near term, the September 30 public appearance is primarily a retail-flow catalyst, not a fundamental one; high turnover makes a sell-the-event outcome plausible if no independently verifiable funding, staking-client, or NAV-per-share disclosure follows. Over 1-3 months, the decisive data are fully diluted share count, ATM/convert issuance terms, cash burn, realized—not annualized seven-day—staking yield, and whether BMNR’s premium to NAV survives ETH volatility. The contrarian view is that the scarcity narrative is already well understood: incremental purchases may be value-destructive to common holders if funded below NAV, while ORBS exposure should receive little look-through credit absent contractual, audited evidence of economic linkage to OpenAI.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Do not chase BMNR on the release alone. Build a NAV monitor using ETH holdings, cash/securities, quoted moonshot positions, debt/preferred claims and fully diluted shares; only consider a tactical long if BMNR trades at a discount to conservatively haircutted NAV and ETH holds above its 20-day trend for 5 trading days.
- Preferred expression for a bullish ETH view: long spot ETH or a liquid ETH vehicle versus BMNR, unless BMNR’s premium to conservative NAV is below 10-15%. This avoids dilution and execution risk while retaining the underlying macro exposure; invalidate if BMNR reports sustained third-party staking revenue and recurring external MAVAN client economics sufficient to justify a services multiple.
- If BMNR trades at a >35-40% premium to conservative NAV after the September 30 catalyst, consider a 1-3 month relative-value pair: short BMNR / long ETH, sized beta-neutral. Primary risk is continued premium-funded issuance creating reflexive demand; stop on a further 20 percentage-point premium expansion or confirmed large institutional capital commitment at a premium.
- Treat ORBS as an event-driven watch item rather than an OpenAI proxy. Require audited disclosure of the ownership chain, liquidity restrictions and valuation methodology before assigning material value; absent that evidence, haircut the position heavily in BMNR NAV work.
More News
- U.S. regulators rush to write crypto rulebook after Clarity Act stalls in Senate
- Bitcoin surges past $85k as Strategy buys more coins
- ‘We believe in college’: inside Andreessen Horowitz’s $42m unaccredited academy that will charge Harvard prices without degrees
- Microsoft and Coinbase probe leads to arrest of crooks behind ‘EvilTokens’, a DIY phishing network powered by AI
- Quantum computing stocks vs. crypto stocks: a value comparison
- Strategy's Stock Has Soared 40% in the Past Month as It's Buying Bitcoins Again
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings