
Sherwin-Williams Celebrates Grand Opening of Expanded Statesville Manufacturing Facility
Source: PR Newswire
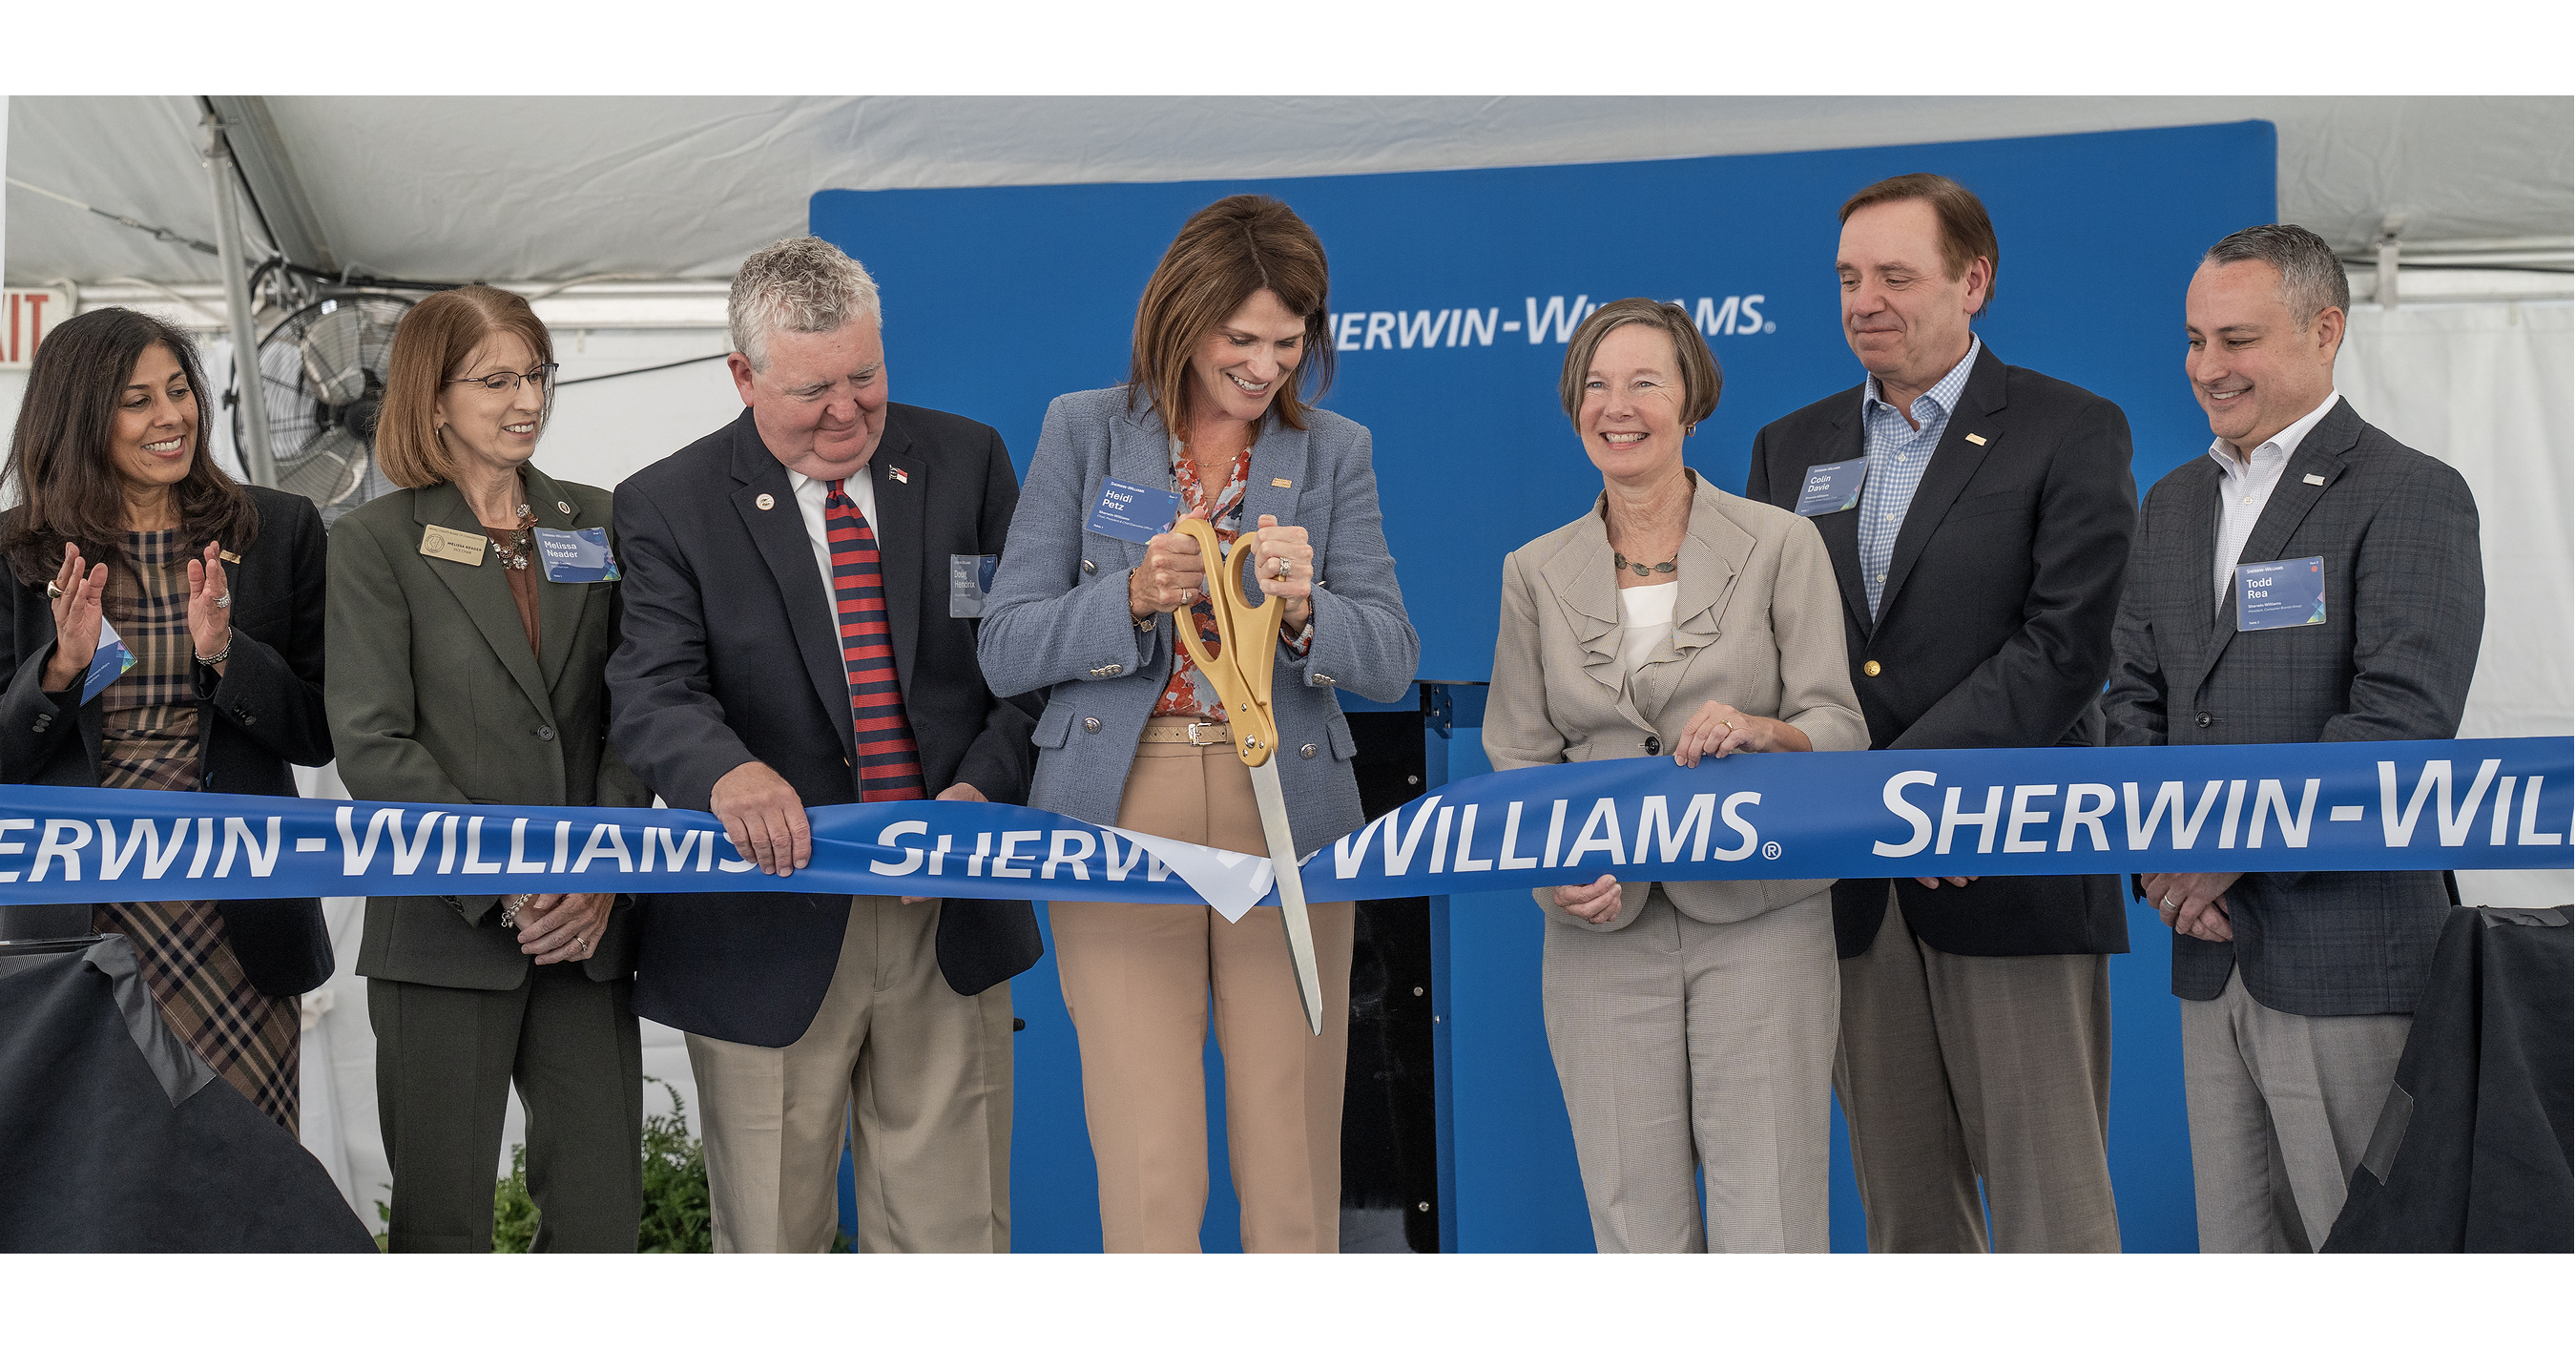
Sherwin-Williams opened its expanded Statesville, North Carolina architectural paint and coatings facility, now its largest manufacturing plant in North America. The nearly 50,000-square-foot upgrade adds production capacity, automation, four rail spurs and logistics infrastructure to improve material handling and supply-chain responsiveness. The investment, supported by state and local incentives, is intended to meet growing customer demand and support long-term growth, though no capital-spending or capacity figures were disclosed.
Analysis
This is incrementally favorable to SHW’s cost-to-serve and working-capital profile, but not yet a forecast-changing event. The economic value comes from reducing stock-outs and expedited freight during seasonal demand peaks, while higher automation and rail utilization can modestly lower conversion and inbound logistics costs; the benefit should emerge over 2-4 quarters only if volume growth absorbs fixed capacity. In a soft residential-repair environment, the same investment could dilute plant utilization and defer margin accretion.
SHW’s company-owned distribution model makes service reliability a competitive weapon versus PPG and MAS, particularly with professional painters for whom job-site availability matters more than modest product-price differences. The second-order effect is likely greater share retention in the contractor channel rather than a near-term revenue step-up; competitors may respond through promotional pricing, limiting industry gross-margin expansion. The relevant 6-18 month question is whether improved regional inventory turns allow SHW to grow sales faster than end-market paint demand without expanding receivables or inventory intensity.
Consensus may over-credit any announced automation project as pure margin upside. New capacity normally carries ramp costs, depreciation and commissioning risk before savings are visible, and paint demand remains exposed to existing-home turnover, remodeling activity and commercial construction. There is no standalone trade catalyst absent evidence in quarterly results that sales growth, gross margin and inventory turns are improving simultaneously.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- Maintain, rather than add to, SHW on this announcement; reassess after the next two earnings reports for evidence of volume-led sales growth and at least 50-100 bps of sustained gross-margin improvement versus prior guidance.
- Use any broad coatings-sector weakness to build SHW only if management confirms that inventory days are stable-to-down while capacity ramps; this would validate that the investment is improving throughput rather than creating underutilization. Falsifier: rising inventories or incremental margin compression despite stable raw-material costs.
- Monitor a relative-value setup: long SHW / short PPG if SHW’s Americas Group comparable sales and operating margin begin outperforming PPG for two consecutive quarters. The thesis is channel-service share capture; exit if PPG closes the organic-growth gap or SHW’s store/plant cost base drives margin deleverage.
- Watch housing turnover, professional contractor demand, and key resin/TiO2 input costs over the next 1-3 months; weaker renovation demand or renewed input inflation would delay realization of logistics savings and argues against treating this as an earnings catalyst.
More News
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- Greer urges G20 to back Trump tariff agenda, takes aim at China
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Why is Nidec stock plunging today?
- Why is Kioxia stock rallying today?