
University of Michigan Credit Union Announces Partnership with Michigan Wolverines Wide Receiver Andrew Marsh
Source: PR Newswire
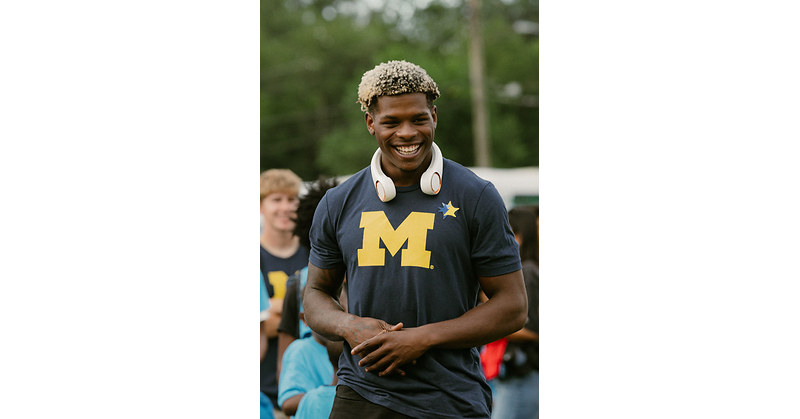
University of Michigan Credit Union (UMCU) announced a community- and financial-education partnership with Michigan wide receiver Andrew Marsh for the 2026/27 season. The credit union will feature Marsh through branch appearances and programs like “Behind the Uniform,” and also deployed an “ATM3” custom mobile fan/youth engagement experience earlier this year. While the announcement supports member engagement for UMCU (nearly 123,000 members, ~$1.4B in assets), it is not expected to materially move broader markets.
Analysis
This reads as a micro-cap marketing/retention move, not an earnings event. For a depository with roughly $1.4B of assets, the spend is immaterial; the only economic question is whether localized athlete-led engagement lowers customer acquisition cost for first accounts and eventually improves cross-sell into auto loans, cards, and youth deposits. If it works, the benefit accrues over 6-18 months through lower funding costs and stickier relationships, not in the next quarter.
The second-order read-through is competitive: community banks and credit unions are fighting a tougher battle for Gen Z and campus-adjacent households, so the response function is more creative sponsorships, higher deposit promos, or better digital onboarding. That is modestly negative for higher-cost-funded lenders and legacy branch-heavy players, but the impact is diffuse and likely lost in quarterly noise. There is no obvious public-equity catalyst here unless a broader set of regionals starts reporting measurable member growth or lower churn from similar programs.
Contrarian view: the market often overestimates NIL-style partnerships as scalable growth engines. Most of the value is brand affinity and data capture, while the monetization path is slow and hard to isolate from normal seasonality. The thesis is falsified if peer banks/credit unions can show incremental new-member wins, deposit balances, or loan originations directly tied to these activations over the next 1-3 quarters; absent that, this stays a publicity event rather than an investable signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No direct trade in public equities; this is not enough to move XLF/KRE or any listed name today. Treat as a watch item only, with a 1-3 quarter horizon for any measurable deposit-acquisition read-through.
- If you want a proxy, monitor KRE vs XLF for signs that smaller depository institutions are absorbing higher customer-acquisition costs without deposit growth. Only act if regional-bank earnings show deposit beta improvement or promo-rate pressure easing.
- Set an alert for any public bank or credit union disclosure that ties athlete/community sponsorships to new-account growth or loan originations. If the linkage appears, it supports a long KRE / short XLF-relative value expression over 3-6 months.
- Do not extrapolate this to MRSH; the name overlap is coincidental and there is no evident fundamental read-through to Marsh & McLennan or other listed insurers/brokers.
More News
- VW Wants to Take On Wrangler and Bronco on Their US Home Turf
- Here are the stocks reporting next week that have a history of earnings beats and big share gains
- Marsh McLennan shares jump as earnings and revenue beat forecasts
- Stocks making the biggest moves midday: CoreWeave, Salesforce, Rocket Lab, Kimberly-Clark & more
- Morning Bid: Coreweave unravels
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt