
CleanBoss Highlights Three-Year Growth at Consensus Great Brands Show
Source: PR Newswire
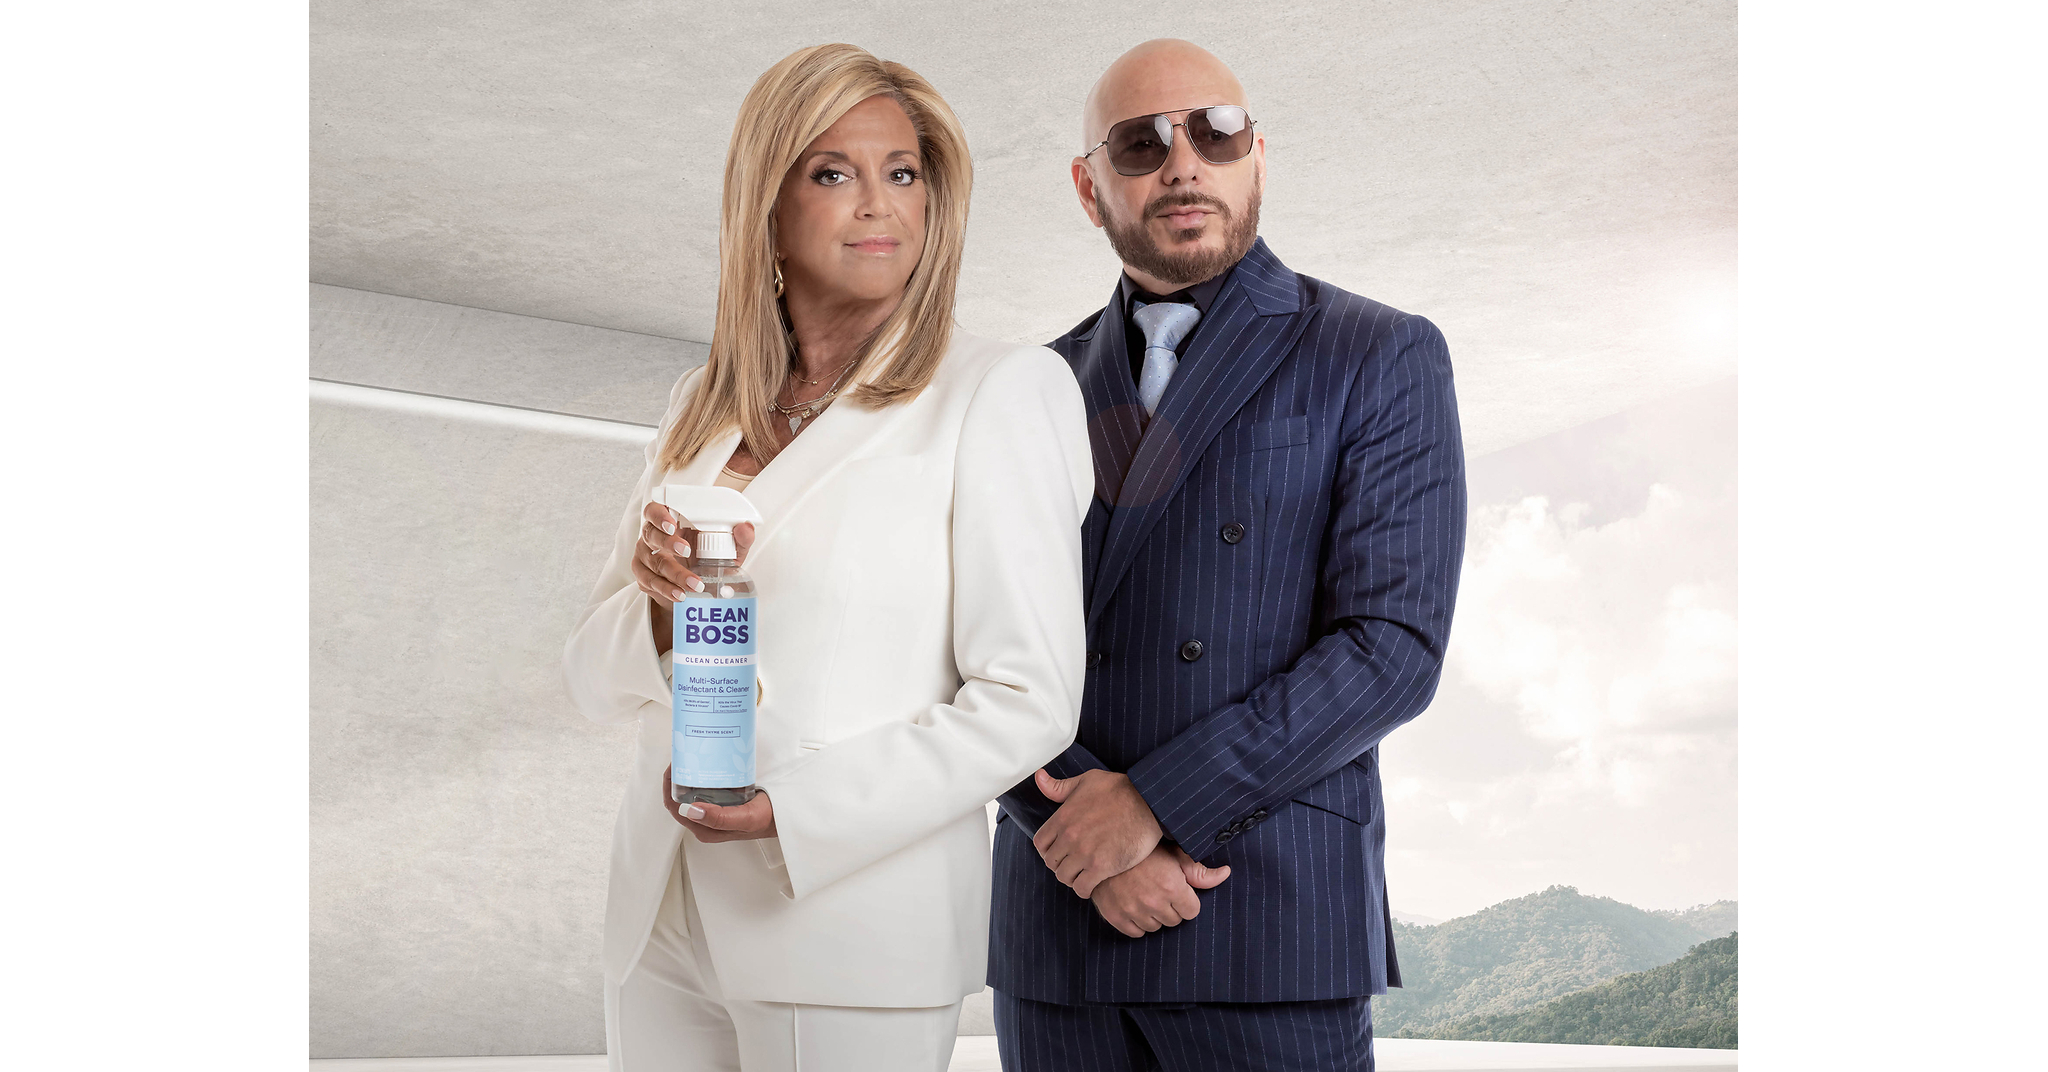
CleanBoss reported 253% annual revenue growth over the preceding three years and presented its multichannel consumer and professional business at the 2026 Consensus Great Brands Show. The company, backed by Consello Capital since an investment announced in November 2025, says it is focused on expanding access and developing products through 2027. Its products are sold through Walmart, Amazon, HSN and QVC, while CleanBoss Pro serves institutional customers including LaGuardia Airport, Howard University and the Smithsonian's National Zoo.
Analysis
The investable signal is weak: this is brand-building, not evidence of a material earnings inflection for the named public retailers or home-shopping channel. CleanBoss is private, and the release provides no revenue base, gross margin, cash generation, repeat-purchase data, or investment terms. The reported three-year growth rate therefore cannot establish scale or quality of growth.
The upside case is that TV and celebrity-led product education lowers customer-acquisition friction, while retail and institutional distribution broaden reach. But adding channels and categories can also dilute margins through promotions, retailer economics, inventory requirements, and fulfillment complexity. Established competitors—including Procter & Gamble, Clorox, and Ecolab—have scale and shelf/distribution advantages; CleanBoss would need demonstrated repeat rates and product-level economics to displace them. Green positioning alone is not a moat, and disinfectant efficacy/label claims warrant verification against applicable product registrations and independent test details.
Near term, expect little fundamental read-through to AMZN, WMT, or QVCAQ absent evidence of meaningful sales contribution. Over 1–3 months, watch for retailer expansion, disclosed sell-through, and repeat-purchase or commercial contract data. The 6–18 month question is whether CleanBoss can grow without trading away margin. The contrarian risk is that headline growth and celebrity reach mask a small base and costly channel mix; conversely, verified repeat sales and profitable institutional reorders would make the platform more credible than a typical launch-driven consumer brand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No trade in AMZN, WMT, or QVCAQ on this announcement: the release establishes no material revenue or earnings exposure for any mapped company.
- Treat CleanBoss as a private-market watch item, not a public-equity proxy. Before underwriting growth, seek absolute revenue by channel, gross margin, cash burn, customer-acquisition cost, repeat rate, and the terms of Consello Capital’s investment.
- Monitor the next 1–3 months for independently verifiable retail sell-through, additional distribution, and repeat commercial orders; confirm the scope of product testing and any required disinfectant registrations rather than relying on promotional claims.
- Reassess the thesis over 6–18 months if the company discloses profitable repeat purchasing or scaled institutional contracts. The growth thesis weakens if expansion depends on persistent promotions, inventory builds, or celebrity-led launches without reorder evidence.
More News
- Skydance shares plunge after company distributes nearly 471 million warrants
- Microsoft's wild ride: Stock hits new record after a year of ups and downs
- ‘The way work gets done is changing across every industry’: Kroger cites AI efficiency push as it cuts 3,000 corporate jobs
- Microsoft Just Unveiled a Brand-New AI Chip. Could It Be the "Nvidia Killer" Everyone's Been Looking For?
- Citizens reiterates Meta stock rating on Instagram engagement growth
- DeepL CEO on Voice AI Growth and Competition
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Independent Research Firms: A Publishing System
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More