
Bakery China Autumn 2026 Reports 50% Growth in International Buyers; Chengdu to Host 2027 Edition
Source: PR Newswire
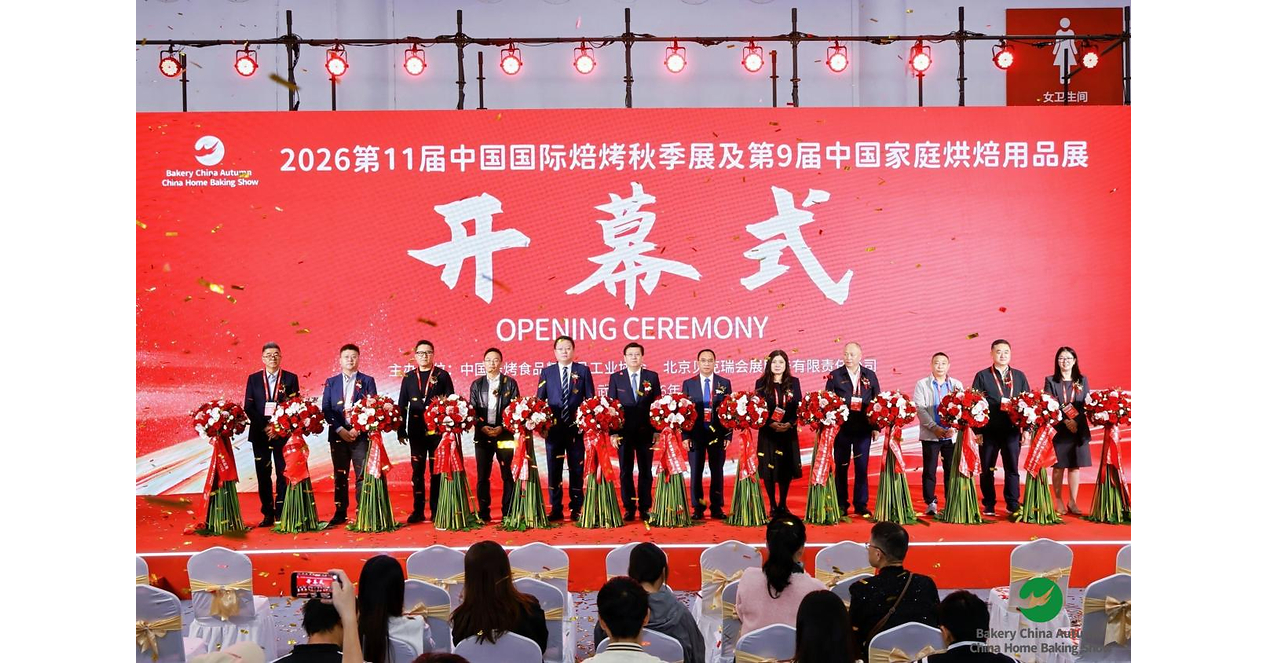
Bakery China Autumn 2026 drew 100,000 visits from 65 countries and regions, with international buyer numbers up 50%. The event showcased retail and supply-chain initiatives, and organizers named Chengdu as host city for the 2027 autumn edition. The article also outlined planned 2027 exhibitions, including a Shanghai event expected to cover 330,000 square meters and attract nearly 400,000 professional visits.
Analysis
The signal is better read as channel experimentation than proof of a demand inflection. A 50% increase in international buyers is potentially useful for exporters and ingredient/equipment suppliers, but without the prior-period base, unique-buyer counts, order conversion, or repeat-purchase data, it does not establish revenue growth. The more investable mechanism is operational: retailers’ interest in short-shelf-life formats can pull demand toward cold-chain capacity, packaging, production automation, and formulation services, while raising shrink and execution risk for operators expanding fresh assortments.
Near term (days): limited fundamental read-through; treat the release as promotional, not independently verified company guidance. Over 1–3 months, look for disclosed contracts, channel additions, and supplier order commentary. Over 6–18 months, sustained store conversion and industrial production could benefit capable upstream suppliers, but may also intensify price competition and pressure smaller bakeries unable to manage waste or secure reliable distribution. Chengdu hosting the 2027 autumn event is a regional-access catalyst, not by itself an earnings catalyst.
Contrarian point: buyer growth may reflect a low base or event participation rather than incremental purchasing power. The white paper and matchmaking activity are not evidence of realized sales. No mapped public companies or transaction data are supplied, so a security-level trade is not justified. Thesis weakens if subsequent industry commentary shows no order conversion or if retailers report rising fresh-food shrink and closures.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Key Decisions for Investors
- No immediate position: do not trade the buyer-growth percentage alone; it lacks a disclosed comparison base and evidence of orders.
- Set a 1–3 month watch on Chinese bakery and fresh-snack suppliers, cold-chain logistics, packaging, and food-processing equipment. Upgrade only if companies independently disclose new customers, utilization gains, or repeat orders attributable to these channels.
- For any future long exposure to upstream suppliers, pair it against fresh-snack operators only if evidence shows channel growth is accruing to suppliers while retailer shrink or operating costs worsen; otherwise the relative-value thesis is unproven.
- Falsification checks: no follow-through in supplier order commentary, weak store-conversion economics, or reported deterioration in fresh-food waste and margins would invalidate the structural-growth read-through.
More News
- Binance co-CEO Richard Teng says hackers used fake job interviews, AI tool to steal $6.3 billion in crypto 108511116
- AMD stock jumps 7% on earnings as data center revenue nearly doubles
- Marvell Technology could plunge on latest multibillion-dollar acquisition
- Disney Plans Thousands of Layoffs Companywide
- 5 things to watch on Election Day as Democrats push for control of Congress
- AMD rides data center riches to ‘largest and most profitable’ quarter in history