
Ternium: Reducing CapEx And Increasing FCF Support 7% Dividend Yield Projections
Source: seekingalpha.com
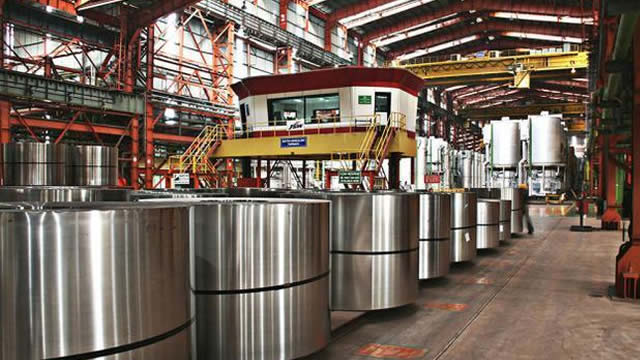
Ternium is rated Buy with a DCF-derived fair value of $65.52, implying 14.5% upside. The $4B Pesqueria project is expected to increase steel capacity and cost competitiveness, lifting EBITDA by 5–10% during 2028–2030. Declining CapEx could push free-cash-flow yield above 15% and support a sustainable 6–7% dividend yield.
Analysis
TX screens as a capital-cycle inflection rather than a near-term steel-beta trade. The market is likely to discount much of the eventual capacity benefit until commissioning risk, ramp yields and incremental Mexican demand are visible; that creates a 12-24 month valuation gap if management delivers milestones without further budget escalation. The more important rerating mechanism is a shift from peak-investment cash absorption to distributable cash flow, which could narrow TX's discount to North American peers such as STLD and NUE despite its greater Latin American macro exposure.
The key second-order beneficiary is Mexico's industrial/nearshoring supply chain: automotive, appliance and infrastructure demand can support local coil realizations and reduce exposure to imported steel. Conversely, added regional supply could pressure spreads for Mexican importers and smaller domestic producers, while any USMCA tariff dispute, Mexican energy constraint, or Chinese steel diversion into Latin America would compress the expected margin uplift. Steel prices remain the dominant 1-3 month driver; the project matters primarily on a 2027-30 horizon.
Consensus may be over-crediting the stated free-cash-flow yield before verifying maintenance capex, working-capital normalization and dividend policy through the ramp. A sustainable yield deserves a premium only if net cash is preserved and capital returns are not subordinated to further expansion. Thesis is falsified by material project-delay/cost-overrun disclosure, a sustained decline in regional HRC spreads, or a reduction in capital-return guidance.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Accumulate TX on weakness below approximately $58/share, targeting $65-66 over 12-18 months as capex rollover becomes visible; use a $51 stop or reduce if the project budget rises materially, offering roughly 2:1 upside/downside before dividends.
- Prefer a relative-value position: long TX / short CLF over 6-12 months. TX has a clearer path to lower capital intensity and a less levered balance sheet profile, while CLF remains more exposed to US spot-steel volatility and automotive-volume risk; close if the spread underperforms by 15% or US HRC pricing materially reaccelerates.
- Do not underwrite the full dividend thesis until the next two reporting periods confirm operating cash flow conversion, maintenance-versus-growth capex disclosure, and unchanged payout intentions. Treat any guidance upgrade tied solely to commodity pricing rather than project execution as a trading catalyst, not a structural rerating signal.
- Set alerts for Mexican HRC/import-price spreads and USMCA trade-policy headlines. Evidence of Chinese import displacement or new tariff uncertainty should prompt a reduction in TX exposure before project economics are embedded in estimates.
More News
- Oil falls on report Asia will import highest volume of crude since start of Iran war
- Trump evalúa prohibir exportaciones de diésel de EE.UU.
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet
- Gold steadies after selloff as oil, strong U.S. data lift Fed hike bets
- Meta's standoff with Amazon over Muse could be a sign of things to come
- A US Diesel Export Ban Would Be a Calamity for the Market