
Pinterest Offers An Ad Moat At A Ridiculously Cheap Price
Source: seekingalpha.com
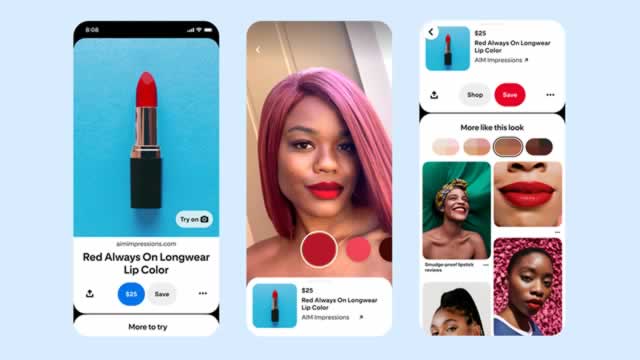
Pinterest is characterized as deeply undervalued at a 9.3x forward P/E despite forecast revenue growth of 15.1%, a 79.5% gross margin, and an ad business supported by high purchase-intent users. Recent performance included 18% year-over-year revenue growth, 11% MAU growth, higher ARPU, and expanding EBITDA margins. AI enhancements and the company’s advertising moat are cited as factors supporting a bullish valuation case rather than a value-trap narrative.
Analysis
The key underwriting question is whether PINS can sustain ARPU growth faster than user growth without materially increasing traffic-acquisition costs. Its commercial-intent audience should make incremental ad inventory more valuable than broad upper-funnel social inventory, particularly if AI-driven targeting improves conversion measurement; that would support EBITDA-margin expansion and a rerating toward higher-quality digital-ad peers rather than merely earnings growth. The relevant competitive read-through is modestly negative for SNAP and potentially for smaller performance-marketing channels if advertisers reallocate budgets toward measurable discovery commerce.
Near term, the stock needs evidence that monetization is broad-based across geographies rather than dependent on pricing gains in North America. Over the next 1-3 months, ad-industry checks, holiday-budget commentary and any incremental disclosure on conversion performance are likely catalysts; a beat with raised margin guidance would challenge the market's apparent assumption that growth requires elevated investment. Over 6-18 months, the upside case depends on international ARPU convergence and durable AI productivity, while the principal downside is a digital-ad slowdown that exposes the company as a lower-scale platform with limited ability to offset weak demand through cost actions.
The contrarian risk is that the low headline earnings multiple embeds stock-based compensation, capitalized technology spending, and an execution discount that is not resolved by one strong quarter. A multiple rerating is unlikely unless management demonstrates recurring operating leverage and sustained advertiser-retention gains. Falsify the constructive thesis on a material deceleration in revenue growth, sequential EBITDA-margin contraction unrelated to seasonality, or guidance implying AI investment is consuming rather than expanding incremental margins.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Initiate a 3-6 month long PINS position on weakness ahead of the next earnings print; target a rerating toward 12-14x forward earnings if revenue growth remains mid-teens or better and EBITDA margin expands. Risk/reward is attractive only if position sizing assumes a 15-20% drawdown on a digital-ad demand miss.
- Express relative-value exposure via long PINS / short SNAP over the next two earnings cycles. The thesis is that conversion-oriented advertiser demand and operating leverage should compound more favorably at PINS; exit if SNAP's revenue-growth differential closes materially or PINS reports ARPU deceleration.
- Use a defined-risk bullish call spread only after confirming that consensus estimates have not already moved materially higher following channel checks; the missing input is implied volatility versus PINS's historical post-earnings move. If implied volatility is elevated, prefer cash equity or the pair trade over outright calls.
- Monitor management disclosure on international ARPU, advertiser retention and incremental AI-related operating expense. Treat any guidance cut in these metrics as a signal to reduce exposure rather than averaging down, since it would weaken both the earnings and multiple-expansion legs of the thesis.
More News
- Cantor Fitzgerald reiterates Nvidia stock rating on AI demand growth
- Trump launches midterms campaign blitz amid record low approval ratings
- Nvidia Faces Questions Over China AI Chip Smuggling Cases
- Europe’s winter energy crunch may already be underway. Two U.S. stocks that may benefit
- Fed’s Cook sees AI buildup as top inflation risk for 2027
- The September jobs report will be released Friday. Here's what to expect