
Global Lupus Nephritis Market to Reach USD 4.08 Billion by 2034 at 8.5% CAGR as Rising Disease Burden and Breakthroughs in Targeted Therapies Accelerate Market Expansion, Says Maximize Market Research
Source: PR Newswire
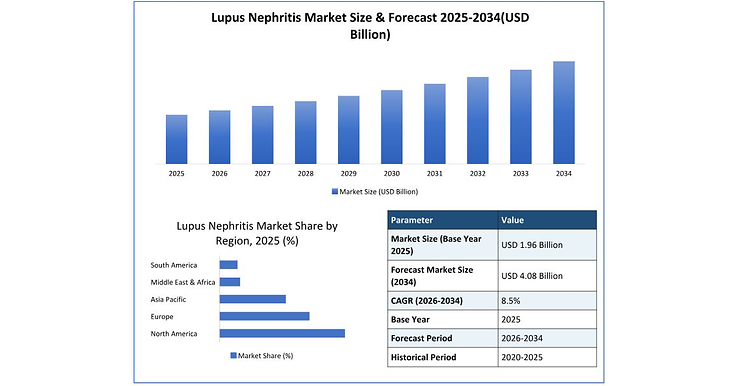
Maximize Market Research projects the global lupus nephritis market to grow at an 8.5% CAGR from $1.96 billion in 2025 to $4.08 billion by 2034. Growth is expected to be driven by rising SLE-related kidney disease awareness, earlier diagnosis, and expanding use of targeted and biologic therapies, with North America leading and Asia-Pacific offering stronger incremental growth. High therapy costs, long treatment durations, safety concerns, and variable patient responses remain key constraints.
Analysis
This is not a material earnings driver for diversified pharma; the relevant investable question is whether lupus nephritis becomes a durable specialty-drug profit pool rather than a broad immunology growth theme. GSK and AUPH have the highest direct sensitivity through established disease-specific franchises, but the long-term economics favor therapies that can demonstrate steroid sparing, durable renal-response superiority, and lower monitoring burden. Those endpoints support earlier-line use and combination regimens, expanding treated duration and net price rather than merely shifting share.
AUPH is the more operationally levered vehicle, but its valuation depends on the persistence of voclosporin demand and the degree to which newer biologic or cell-therapy approaches displace calcineurin-inhibitor-based combinations. GSK's franchise has better diversification and reimbursement infrastructure, while BMY, IMVT, KYTX and CART-cell developers offer higher-beta optionality if B-cell depletion or reset strategies generate convincing renal outcomes; near-term, however, these programs are likely to add trial cost before revenue. Large-cap references such as PFE, MRK and AZN should not be assigned meaningful upside absent named assets, trial enrollment, or regulatory milestones.
Consensus may over-credit a top-down market-growth estimate that lacks patient, pricing, and treatment-duration assumptions. The important structural constraint is payer utilization management: premium therapies will need to reduce dialysis progression, hospitalizations, or chronic steroid toxicity to unlock broad access. Over the next 6-18 months, comparative renal-response durability and safety—not market-size reports—will determine whether the category rerates.
The immediate signal is insufficient for a sector-wide trade. Monitor GSK and AUPH prescription trends, gross-to-net pressure, and formulary positioning over the next two quarterly prints; a loss of persistence or an unfavorable safety signal would compress specialty-franchise multiples quickly, while durable uptake would disproportionately benefit AUPH.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No event-driven trade on this research release; its low-information content is unlikely to alter consensus estimates for diversified pharma over days to 3 months.
- Maintain or initiate a 6-12 month relative long GSK / short equal-dollar PFE basket: GSK has more directly monetizable lupus exposure, while PFE's immunology pipeline linkage is less clearly tied to renal lupus. Reassess if GSK reports decelerating specialty demand or material net-price erosion.
- Keep AUPH on a catalyst watch rather than add on the report: consider a long only after the next earnings release confirms prescription growth, persistence, and stable gross-to-net. Upside comes from sustained franchise durability; downside is disproportionate if competitive data or formulary changes challenge voclosporin's role.
- For high-risk biotech exposure, track IMVT and KYTX clinical updates for renal-specific durable response, steroid reduction, infection rates, and kidney-function preservation. Do not underwrite revenue from broad lupus market growth alone; absent those data, the appropriate position is an alert, not a recommendation.
More News
- Halozyme Therapeutics completes $1.5 billion convertible notes offering
- Dozens of people sue GLP-1 drug companies over alleged vision loss
- Vertex stock price target maintained at $641 by H.C. Wainwright
- Roche obesity drug shows 15.5% weight loss in diabetes trial
- Why is Celldex Therapeutics stock sliding today?
- Vertex reports positive Phase 2b results for kidney disease drug