
TCL CSOT Showcases New Innovations and Insights into the Future of Displays at DIC EXPO 2026
Source: PR Newswire
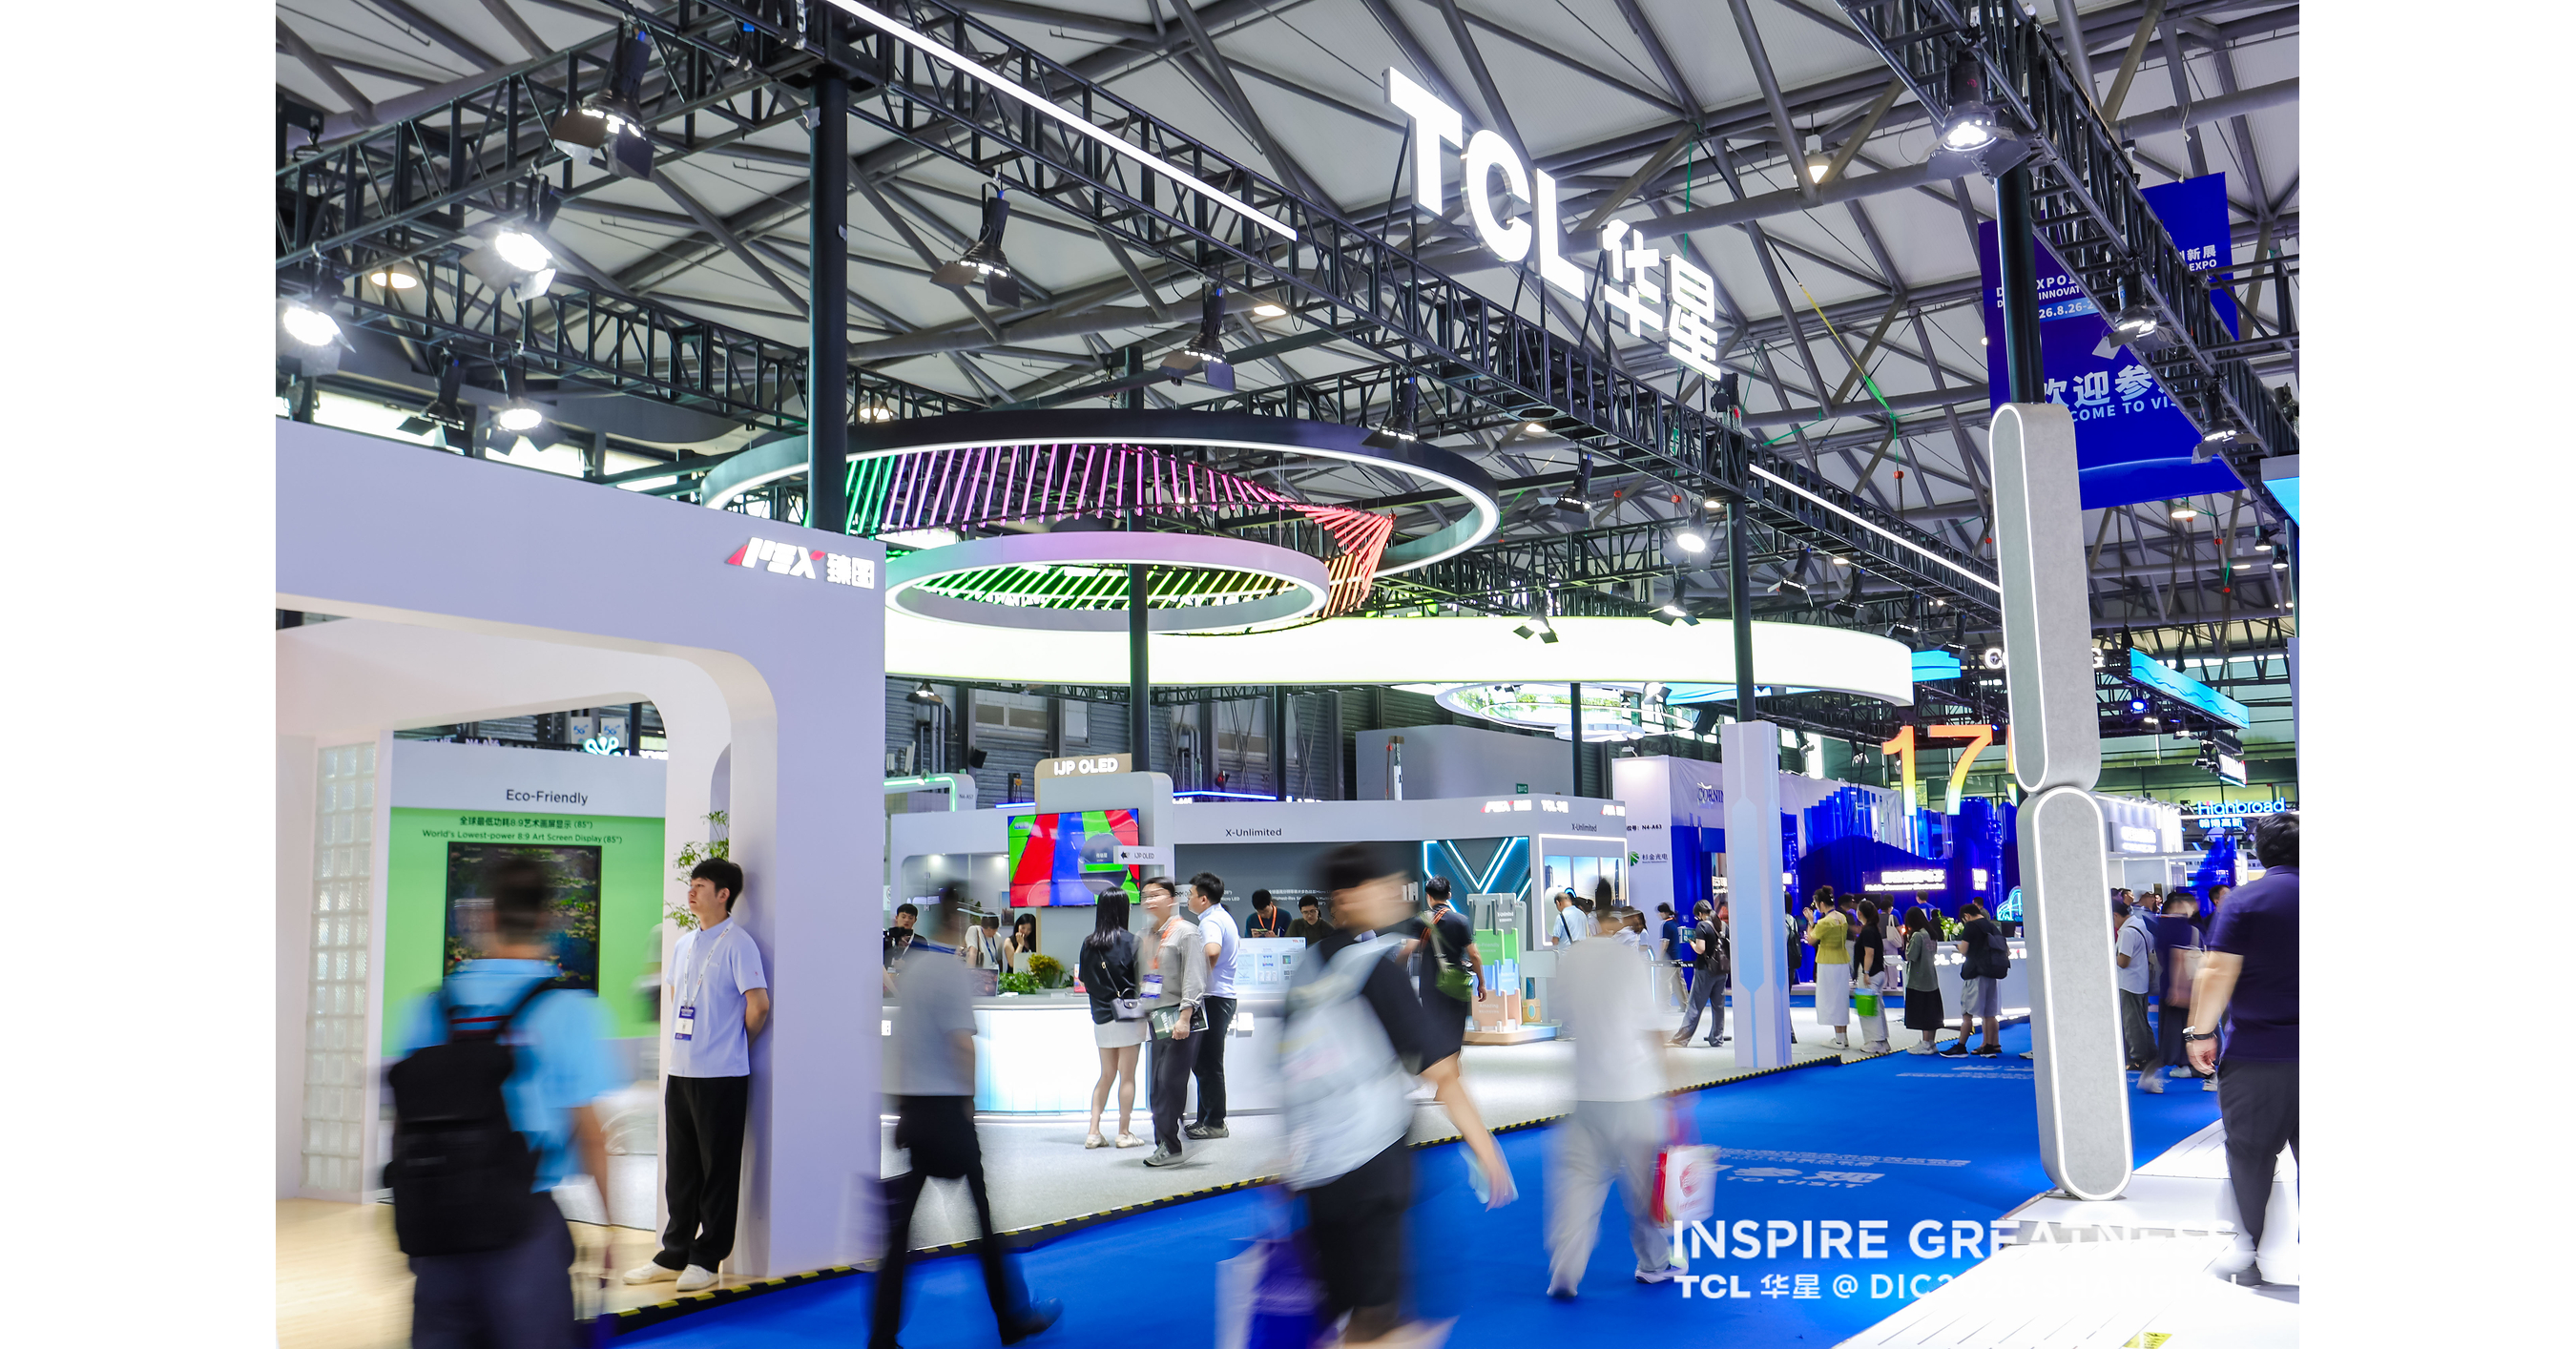
TCL CSOT showcased next-generation display tech at DIC EXPO 2026, highlighting AI-driven R&D via its proprietary model X-Intelligence and ongoing IJP OLED commercialization. The company cited global display industry growth from $123B (2022) to $156B (2030) and said IJP OLED is already in mass production for professional displays, with consumer laptop/monitor validation underway. Specific product claims included a 30% reduction in EL power for its lowest-power PLP OLED tablet display and a foldable portable 28-inch IJP OLED monitor.
Analysis
This is more a competitive-signal event than an investable revenue catalyst. The real implication is that lower-capex, higher-yield OLED manufacturing could let Chinese panel makers press into notebooks/monitors faster, which is bearish for incumbent LCD formats and mildly negative for any supplier whose economics depend on expensive tooling rather than unit volume. If the process claim is real, the first-order winner is the OLED adoption stack; the second-order loser is pricing power at legacy display makers, especially where customers can dual-source and force concessions.
For public equities, the cleanest beneficiary is Universal Display (OLED): its royalty base expands if OLED penetrates larger addressable categories, and its economics are less exposed to lower material intensity than the market may assume. Applied Materials (AMAT) is a more ambiguous hedge: if IJP OLED reduces capex per line, equipment spend per added panel falls, but that is only meaningful if the technology scales beyond demos. GM is too far downstream for this to matter near term; any auto-display benefit is 12-18 months out and likely immaterial to consensus.
Contrarian view: the market may be overreacting to a showcase narrative. Consumer notebook/monitor OLED still lives or dies on yield, burn-in durability, and OEM qualification, not expo-stage specifications. The near-term catalyst is not the announcement itself but whether TCL can surface named design wins within 1-2 quarters; absent that, this stays an R&D story and fades into the noise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- Long OLED on a pullback only if we see confirmed notebook/monitor design wins from TCL or peers within 1-2 quarters; otherwise stay flat. Risk/reward is attractive on a 6-12 month OLED penetration thesis, but invalidated quickly if consumer qualification stalls.
- Do not chase GM, AERA, or WWRL on this headline; there is no credible earnings-path linkage. Treat any move as non-fundamental and fade it unless automotive display content shows up in guidance.
- Watch AMAT as a relative short only if multiple panel makers start advertising lower-capex IJP OLED lines in the next 1-3 months; without that evidence, the bearish equipment read-through is too speculative.
- Set an alert for OLED and panel-sector multiples if notebook/monitor OLED ASPs soften or mix improvement fails to appear by the next earnings cycle; that would falsify the adoption-acceleration thesis.
More News
- VW Wants to Take On Wrangler and Bronco on Their US Home Turf
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Faraday Copper completes acquisition of BHP’s San Manuel project
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom