
Kibar Americas Celebrates Grand Opening of Fairmont Aluminum Manufacturing Facility
Source: PR Newswire
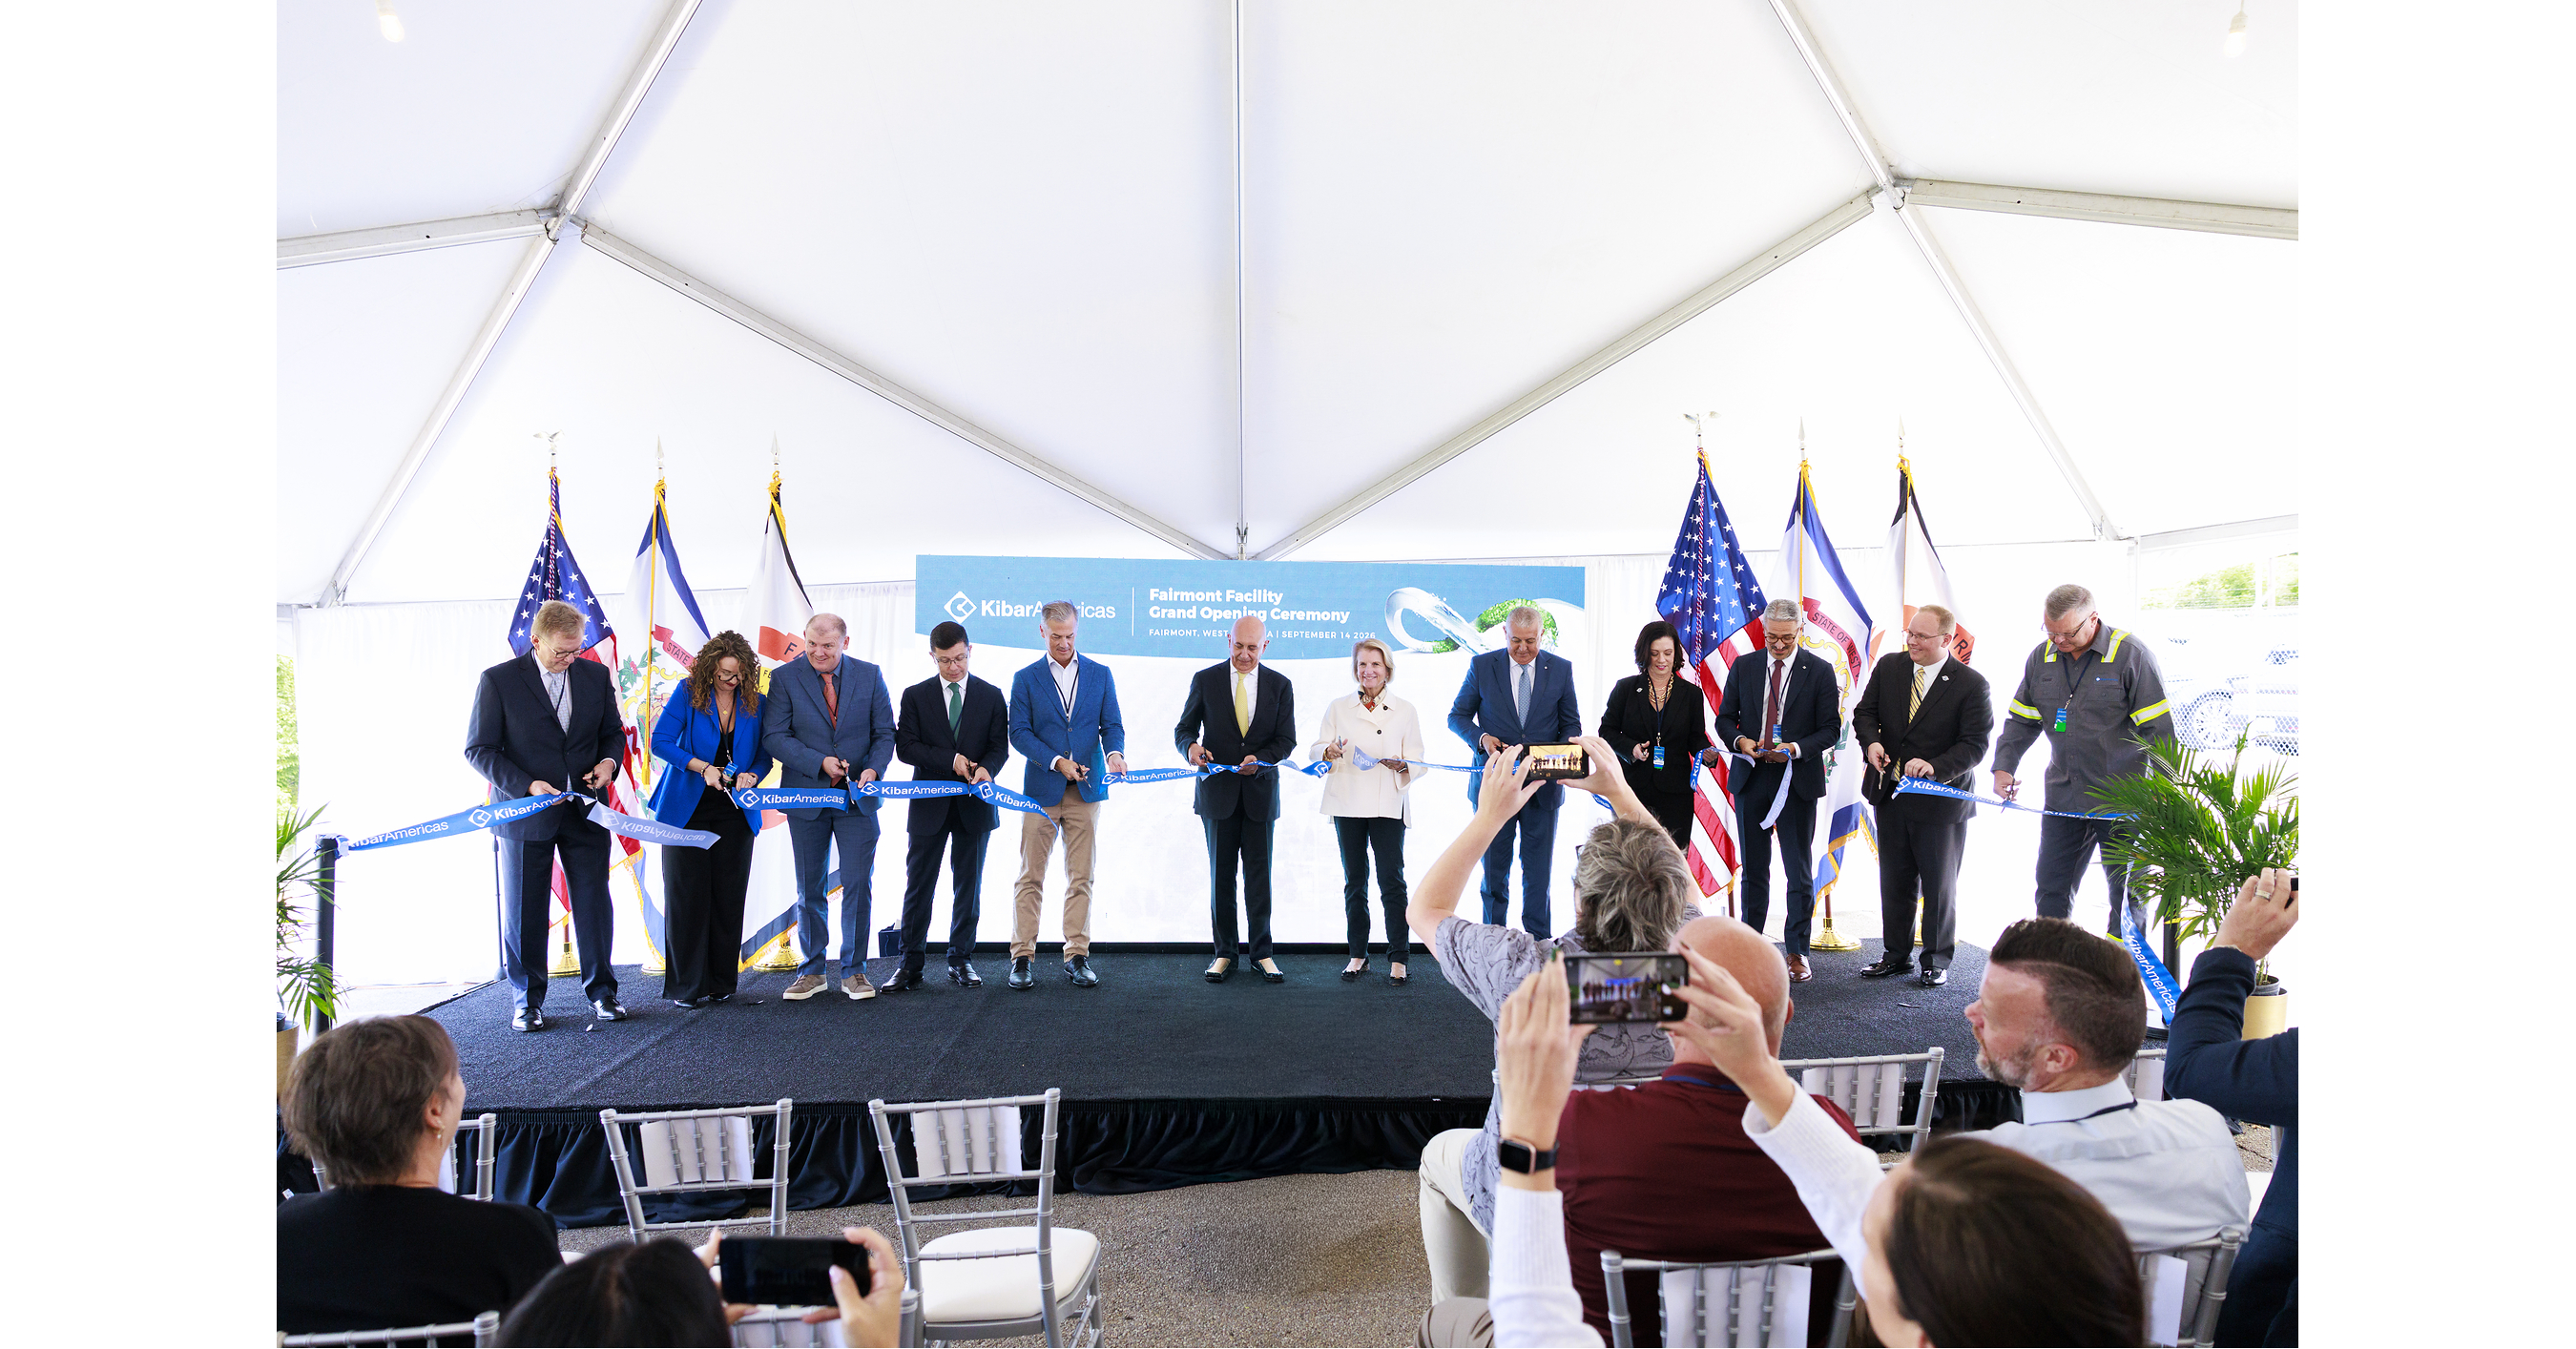
Kibar Americas opened and began production at its Fairmont, West Virginia aluminum manufacturing facility, acquired earlier in 2026. The plant will supply aluminum products to HVAC, packaging, automotive and industrial customers, adding U.S. production capacity to the company's commercial and distribution operations. Management described the investment as a cornerstone of its North American growth strategy and plans further expansion, though no capital-spending, capacity or financial targets were disclosed.
Analysis
This is not yet a listed-equity catalyst, but it modestly increases North American conversion capacity in flat-rolled aluminum/foil at a time when buyers are prioritizing domestic supply security. The likely commercial pressure falls on incumbent foil and specialty rolled-product suppliers rather than primary aluminum producers: local output can reduce freight, inventory buffers, and lead-time premiums, limiting pricing power for regional converters if Kibar ramps successfully. Near-term financial impact is unlikely to register in broad aluminum benchmarks because facility capacity, product mix, customer awards, and qualification status are undisclosed.
The non-obvious read-through is to downstream qualification cycles. HVAC-fin stock, packaging foil, and auto heat-exchanger customers typically require 6-18 months to qualify new material sources; therefore, the opening itself should not be assumed to displace incumbent volumes immediately. If the plant targets import-substituted foil, it may benefit from trade-policy protection and customers' desire to diversify away from offshore supply, but execution risk is high: scrap sourcing, rolling yields, energy costs, and utilization determine whether the facility is a durable low-cost entrant or merely incremental capacity in a cyclical market.
For public markets, watch Aluminum Corporation of China (ACH) and Century Aluminum (CENX) only as indirect aluminum-price exposures, not direct beneficiaries. The cleaner competitive read-through is to packaging and HVAC material buyers: incremental local supply could marginally ease input availability, but aluminum price and Midwest-premium moves remain far more important than this single asset. No immediate trade is warranted absent capacity and customer-contract disclosure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No directional position on this announcement; set an event alert for disclosed annual tonnage, committed customer volumes, and product qualification milestones over the next 6-12 months.
- Monitor the U.S. Midwest aluminum premium and foil import/trade-case developments; a sustained premium decline alongside successful ramp evidence would be modestly negative for domestic rolled-product pricing and positive for aluminum-consuming HVAC/packaging manufacturers.
- For CENX, treat any perceived bullish read-through as suspect: the thesis is falsified as a direct beneficiary unless Kibar discloses meaningful domestic primary-metal offtake. CENX remains driven primarily by LME aluminum, Midwest premium, power costs, and its smelter operating profile.
- If Kibar announces large contracted automotive or HVAC volumes, evaluate a relative-value short in exposed specialty-rolling peers versus a long in diversified aluminum consumers; require evidence of capacity scale and pricing before initiating, since qualification lead times defer volume impact.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- Oil prices dip as U.S. inventory build offsets M.East supply jitters
- Iran war has cost Pentagon $38 billion and depleted missile stockpiles, CBO says
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say