
point.me Launches Gateway, An All-In-One Platform That Puts Award Travel Booking Inside Banks And Loyalty Programs
Source: PR Newswire
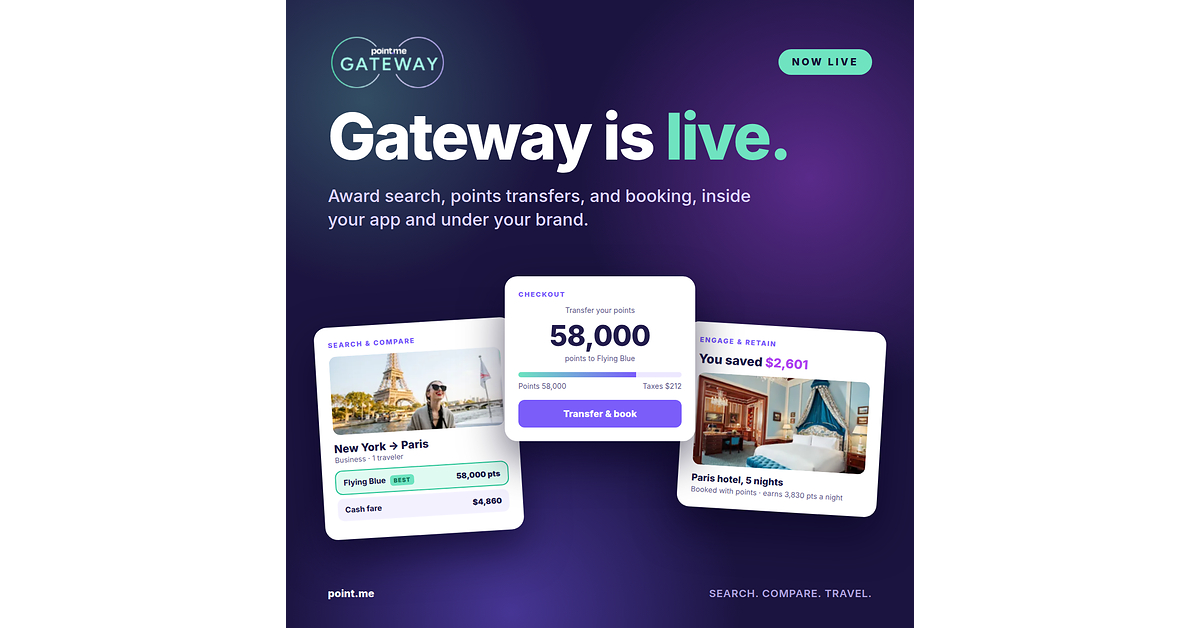
point.me launched Gateway, a white-label platform enabling banks, fintechs and loyalty programs to embed real-time award travel search, points-versus-cash comparison, transfers and booking within their own apps or websites. The company says partners can deploy the service in as little as 60 days, targeting a large friction point in loyalty redemption: more than 80% of U.S. consumers have never transferred a point. Gateway launches with B2Bpay on the financial-services side and expands point.me's Flying Blue relationship, potentially increasing the perceived value and use of card and loyalty currencies.
Analysis
This is strategically positive for AXP and Air France-KLM (AF) only if embedded redemption meaningfully improves card spend retention or directs incremental transfer volume into Flying Blue. The more immediate economic effect is likely a higher redemption rate, which can be mixed for issuers: improved perceived rewards value supports acquisition and interchange-rich spend, but faster burn accelerates the recognition of loyalty-program liability and raises the cost of reward fulfillment. The key metric is incremental spend per active cardholder relative to incremental redemption expense—not adoption claims or portal launch timing.
Airlines with transferable-currency partnerships can gain high-yield award demand without paying customer-acquisition costs, but this also makes award inventory more transparent and reduces their ability to monetize complexity. AF could benefit if its dynamic award pricing captures newly informed demand; conversely, airlines with constrained premium-cabin inventory may see customer dissatisfaction rather than loyalty uplift. Hotel programs and card issuers with weaker proprietary travel portals face the greatest competitive pressure, as a neutral comparison layer makes opaque redemption economics harder to defend.
There is no near-term public-equity trade on the announcement alone: point.me is private, partner scale and commercial terms are undisclosed, and the cited public-company relationships do not establish revenue materiality. Over 6-18 months, the more relevant read-through is whether major issuers outsource redemption UX rather than build internally; that would modestly pressure travel-portal differentiation at large banks while favoring issuers with broad transfer networks. A contrarian view is that easier comparison could encourage consumers to retain points for high-value transfers rather than redeem through issuer portals, weakening issuer breakage economics despite higher engagement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- Maintain AXP as a watch-list beneficiary, not a launch-driven long. Reassess after the next two earnings cycles if management discloses higher Membership Rewards redemption, stable rewards expense as a percentage of billed business, and improving card retention; a rise in rewards expense without spend acceleration falsifies the positive thesis.
- Monitor AF quarterly loyalty and unit-revenue disclosures for evidence that partner-sourced award bookings are additive rather than displacing paid demand. A sustained increase in award-seat dilution or premium-cabin yield pressure would turn the loyalty-distribution thesis negative.
- For bank-sector relative value, screen C, JPM, COF and DFS for travel-and-rewards expense acceleration versus card purchase-volume growth over the next 1-3 quarters. Do not position until a measurable divergence emerges; the likely risk is multiple compression for issuers whose loyalty liability grows faster than interchange revenue.
- Treat DASH, GOOG and META as non-actionable mentions: no disclosed contractual, revenue, or product linkage makes this insufficient to alter estimates or positioning.
More News
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- AI’s biggest players promise to police themselves at the White House
- Google unveils latest AI model, but Wall Street wants a breakout personal agent
- Exclusive-Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- World’s first enhanced geothermal power plant completed in just 23 months
- How Muse could be coming next for Apple's golden goose