
Regent Seven Seas Cruises® Expands Motorsport Lab Collaboration with Exclusive 2027 European Land Programs
Source: PRWeb
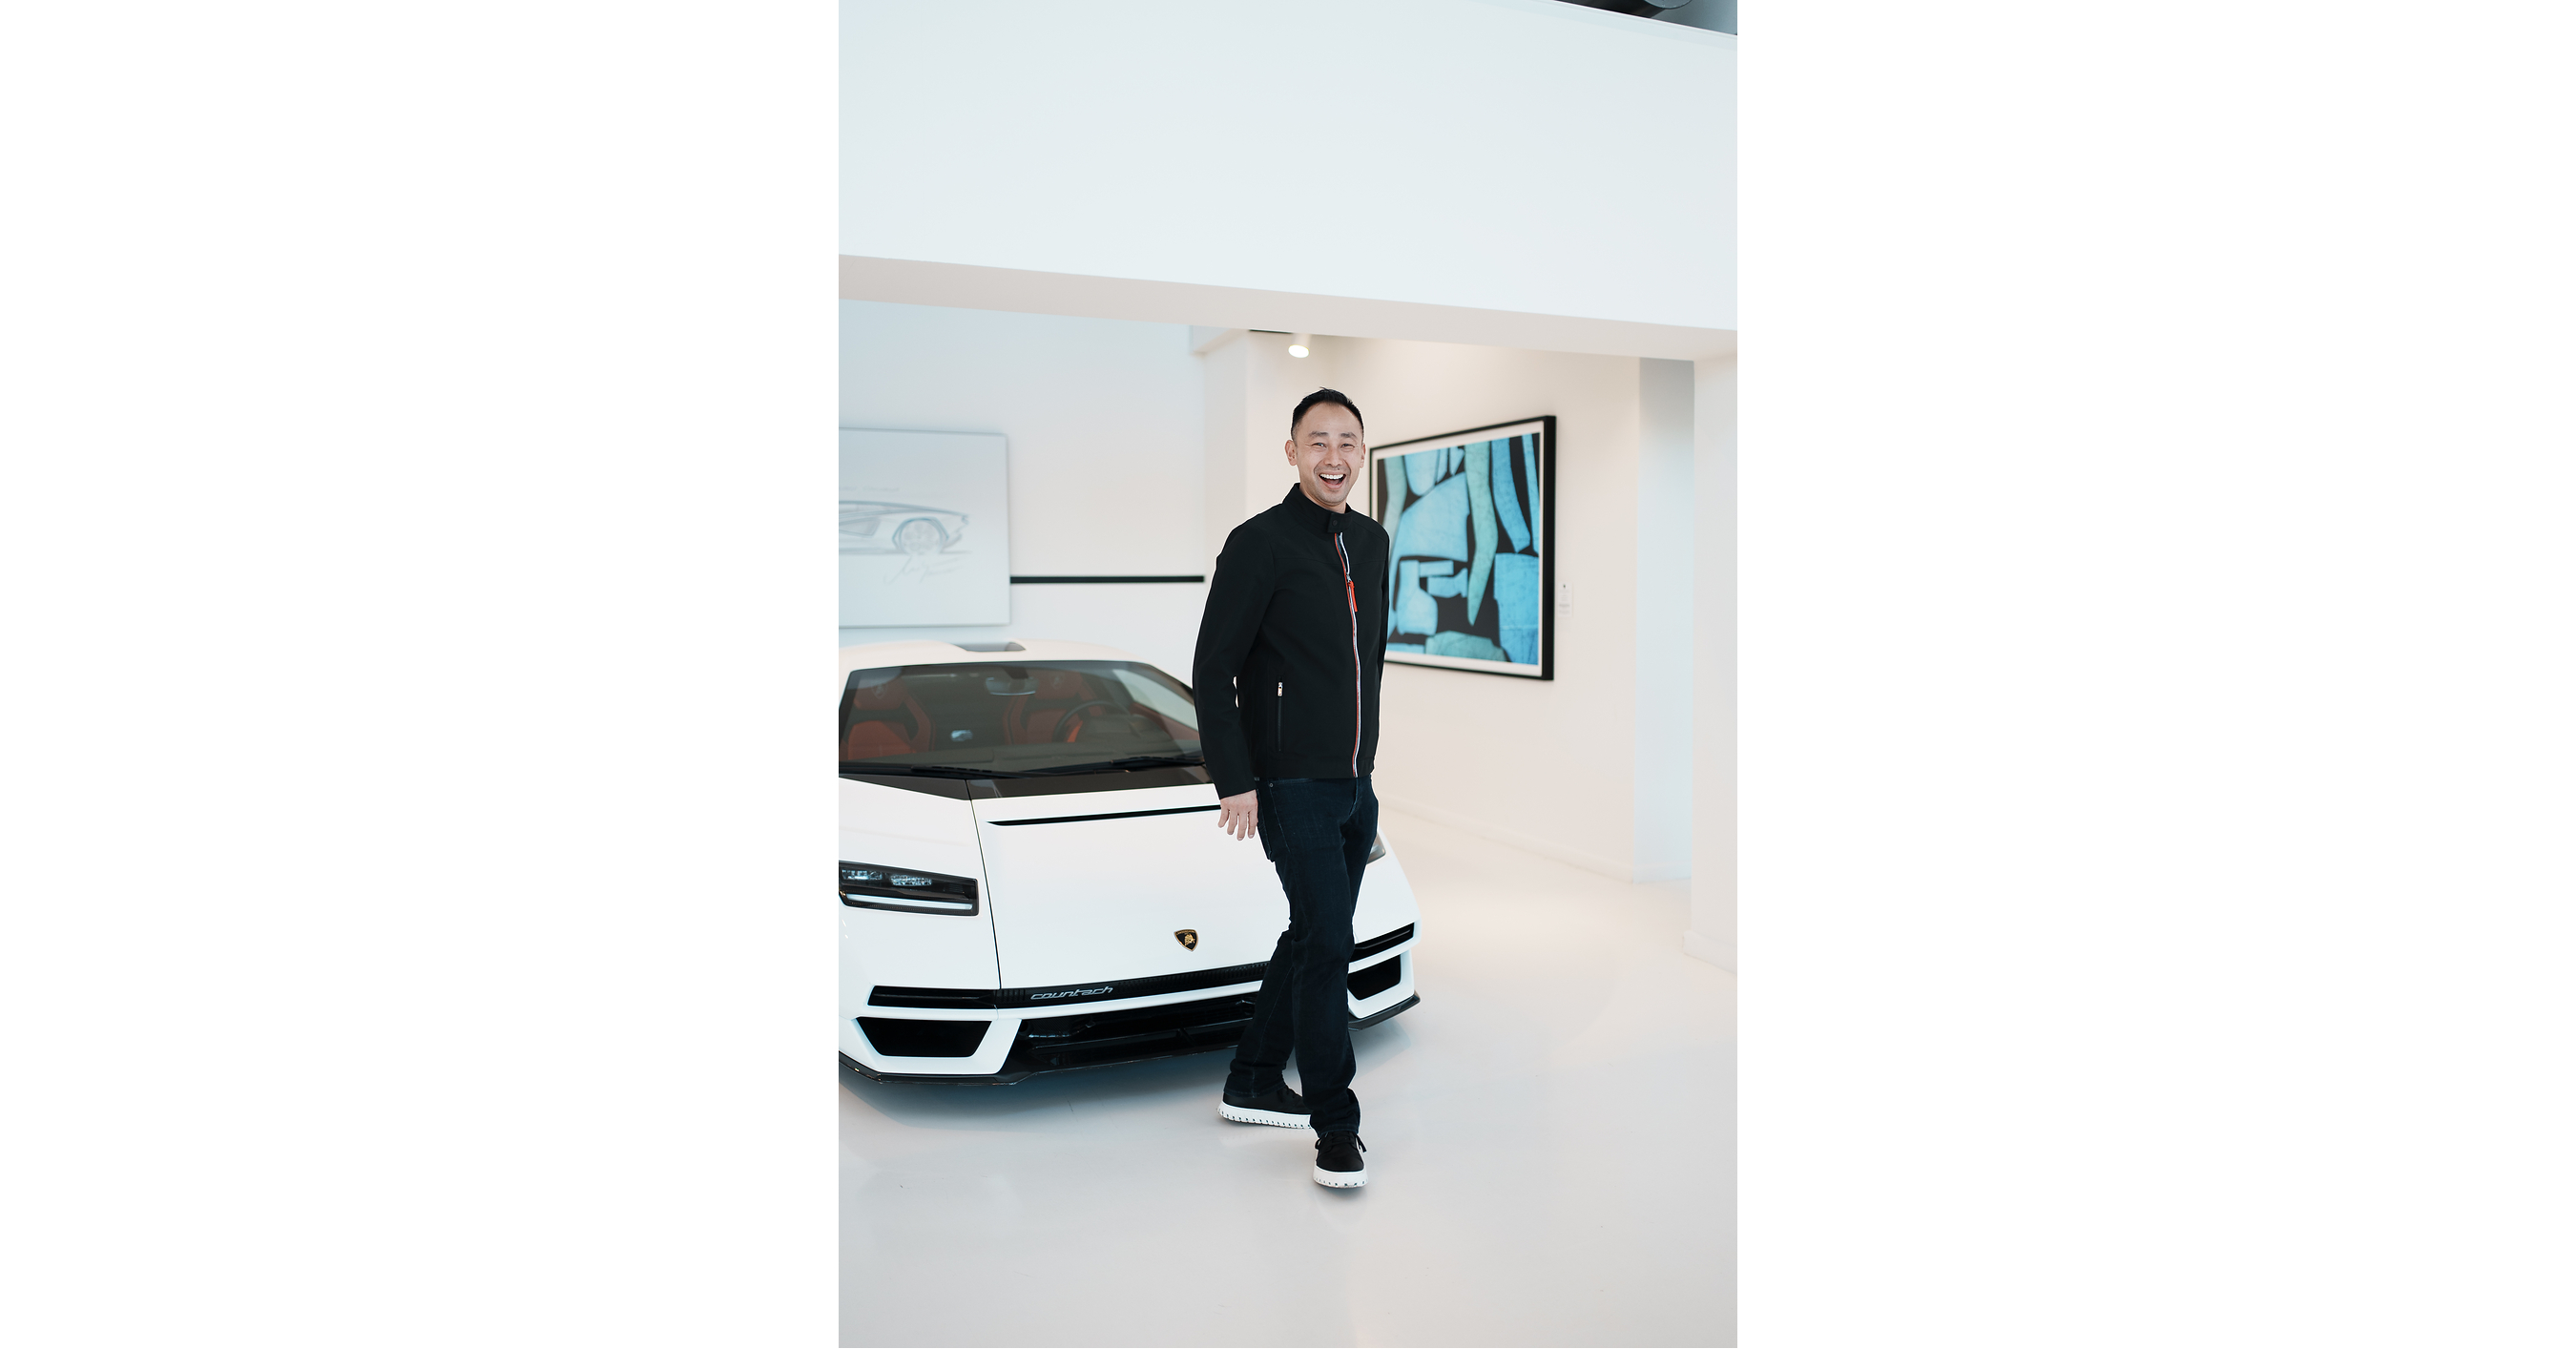
Regent Seven Seas Cruises expanded its Motorsport Lab partnership with four luxury automotive pre- and post-cruise programs across seven European voyages in 2027. Programs in Barcelona, Goodwood and Italy's Motor Valley are priced at $7,399-$7,899 per guest based on double occupancy and feature supercar or classic-car driving, private automotive access and curated culinary/cultural experiences. The offering supports Regent's premium experiential-travel positioning but is unlikely to materially affect Norwegian Cruise Line Holdings' near-term financial results.
Analysis
This is a modest but strategically useful yield-management signal for NCLH rather than a material revenue event. High-ticket land extensions monetize a customer cohort already screened for willingness to pay, potentially lifting ancillary revenue with limited onboard capacity consumption; the relevant KPI is attach rate and contribution margin, not headline program price. If repeatable across Regent itineraries, experiential packaging can support premium net-yield resilience during periods when luxury cruise pricing normalizes, but seven departures are far too small to alter consolidated estimates.
The more relevant 6-18 month implication is brand differentiation ahead of further fleet deployment: bespoke access creates a less easily comparable product than cabins or included shore excursions, reducing price transparency versus luxury peers. This favors NCLH's ability to protect Regent pricing, while also raising execution risk: third-party capacity, safety/liability exposure, and cancellation economics could dilute margins if the company absorbs guest disruption. RACE, PAH3 and AML receive branding exposure but no investable volume read-through; affluent traveler demand does not translate into vehicle sales without evidence of qualified leads, conversion arrangements, or manufacturer sponsorship.
Consensus may over-credit every luxury add-on as proof of broad high-end consumer strength. These packages target an unusually narrow enthusiast segment and are likely supply constrained, so successful sell-through would chiefly validate Regent's CRM and upsell capability—not demand elasticity across NCLH's mass-market brands. The near-term stock impact should be negligible; the trade-relevant catalyst is whether upcoming earnings show sustained net yield and onboard/other-revenue outperformance alongside stable booked occupancy, indicating that premium ancillary mix is scaling beyond isolated promotions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release. Maintain NCLH as a watch item into the next earnings call; upgrade the ancillary-yield thesis only if management discloses Regent land-program attach rates or onboard/other revenue growth above ticket-yield growth.
- For an existing long NCLH position, treat premium-experience expansion as incremental support for 6-18 month yield durability, not an estimate-changing catalyst. Thesis is falsified by lower net-yield guidance, weaker luxury booked occupancy, or evidence that promotional spend is required to fill premium inventory.
- Do not use RACE, PAH3, or AML as sympathy longs. Require disclosed commercial partnership economics, measurable customer-lead conversion, or broader recurring activation before attributing revenue value to automotive-experience exposure.
- Relative-value monitor: if NCLH materially underperforms CCL and RCL despite stable premium booking commentary and improving net-yield guidance over the next 1-3 months, consider a long NCLH / short CCL pair, sized small; exit on renewed leverage concerns or a widening discount driven by weaker forward deposits.
More News
- Miami's ultra-luxury housing market booms as cash transactions dominate, high-end brands like Bugatti and Porsche jump in
- Bentley takes on Ferrari with its first EV priced at $230,000
- Disney, dethroned: Dubai takes the Magic Kingdom’s crown for the world’s most-visited theme park
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Tesla poised to scale production of heavy-duty Semi trucks with opening of Nevada factory
- Here’s the Tesla Semi… again
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense vs Hebbia vs AllMind: Choose by Workflow
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace