
ROYAL CARIBBEAN GROUP AND SANDALS RESORTS ANNOUNCE LANDMARK PARTNERSHIP TO ACCELERATE THEIR LEADING VACATION EXPERIENCES
Source: PR Newswire
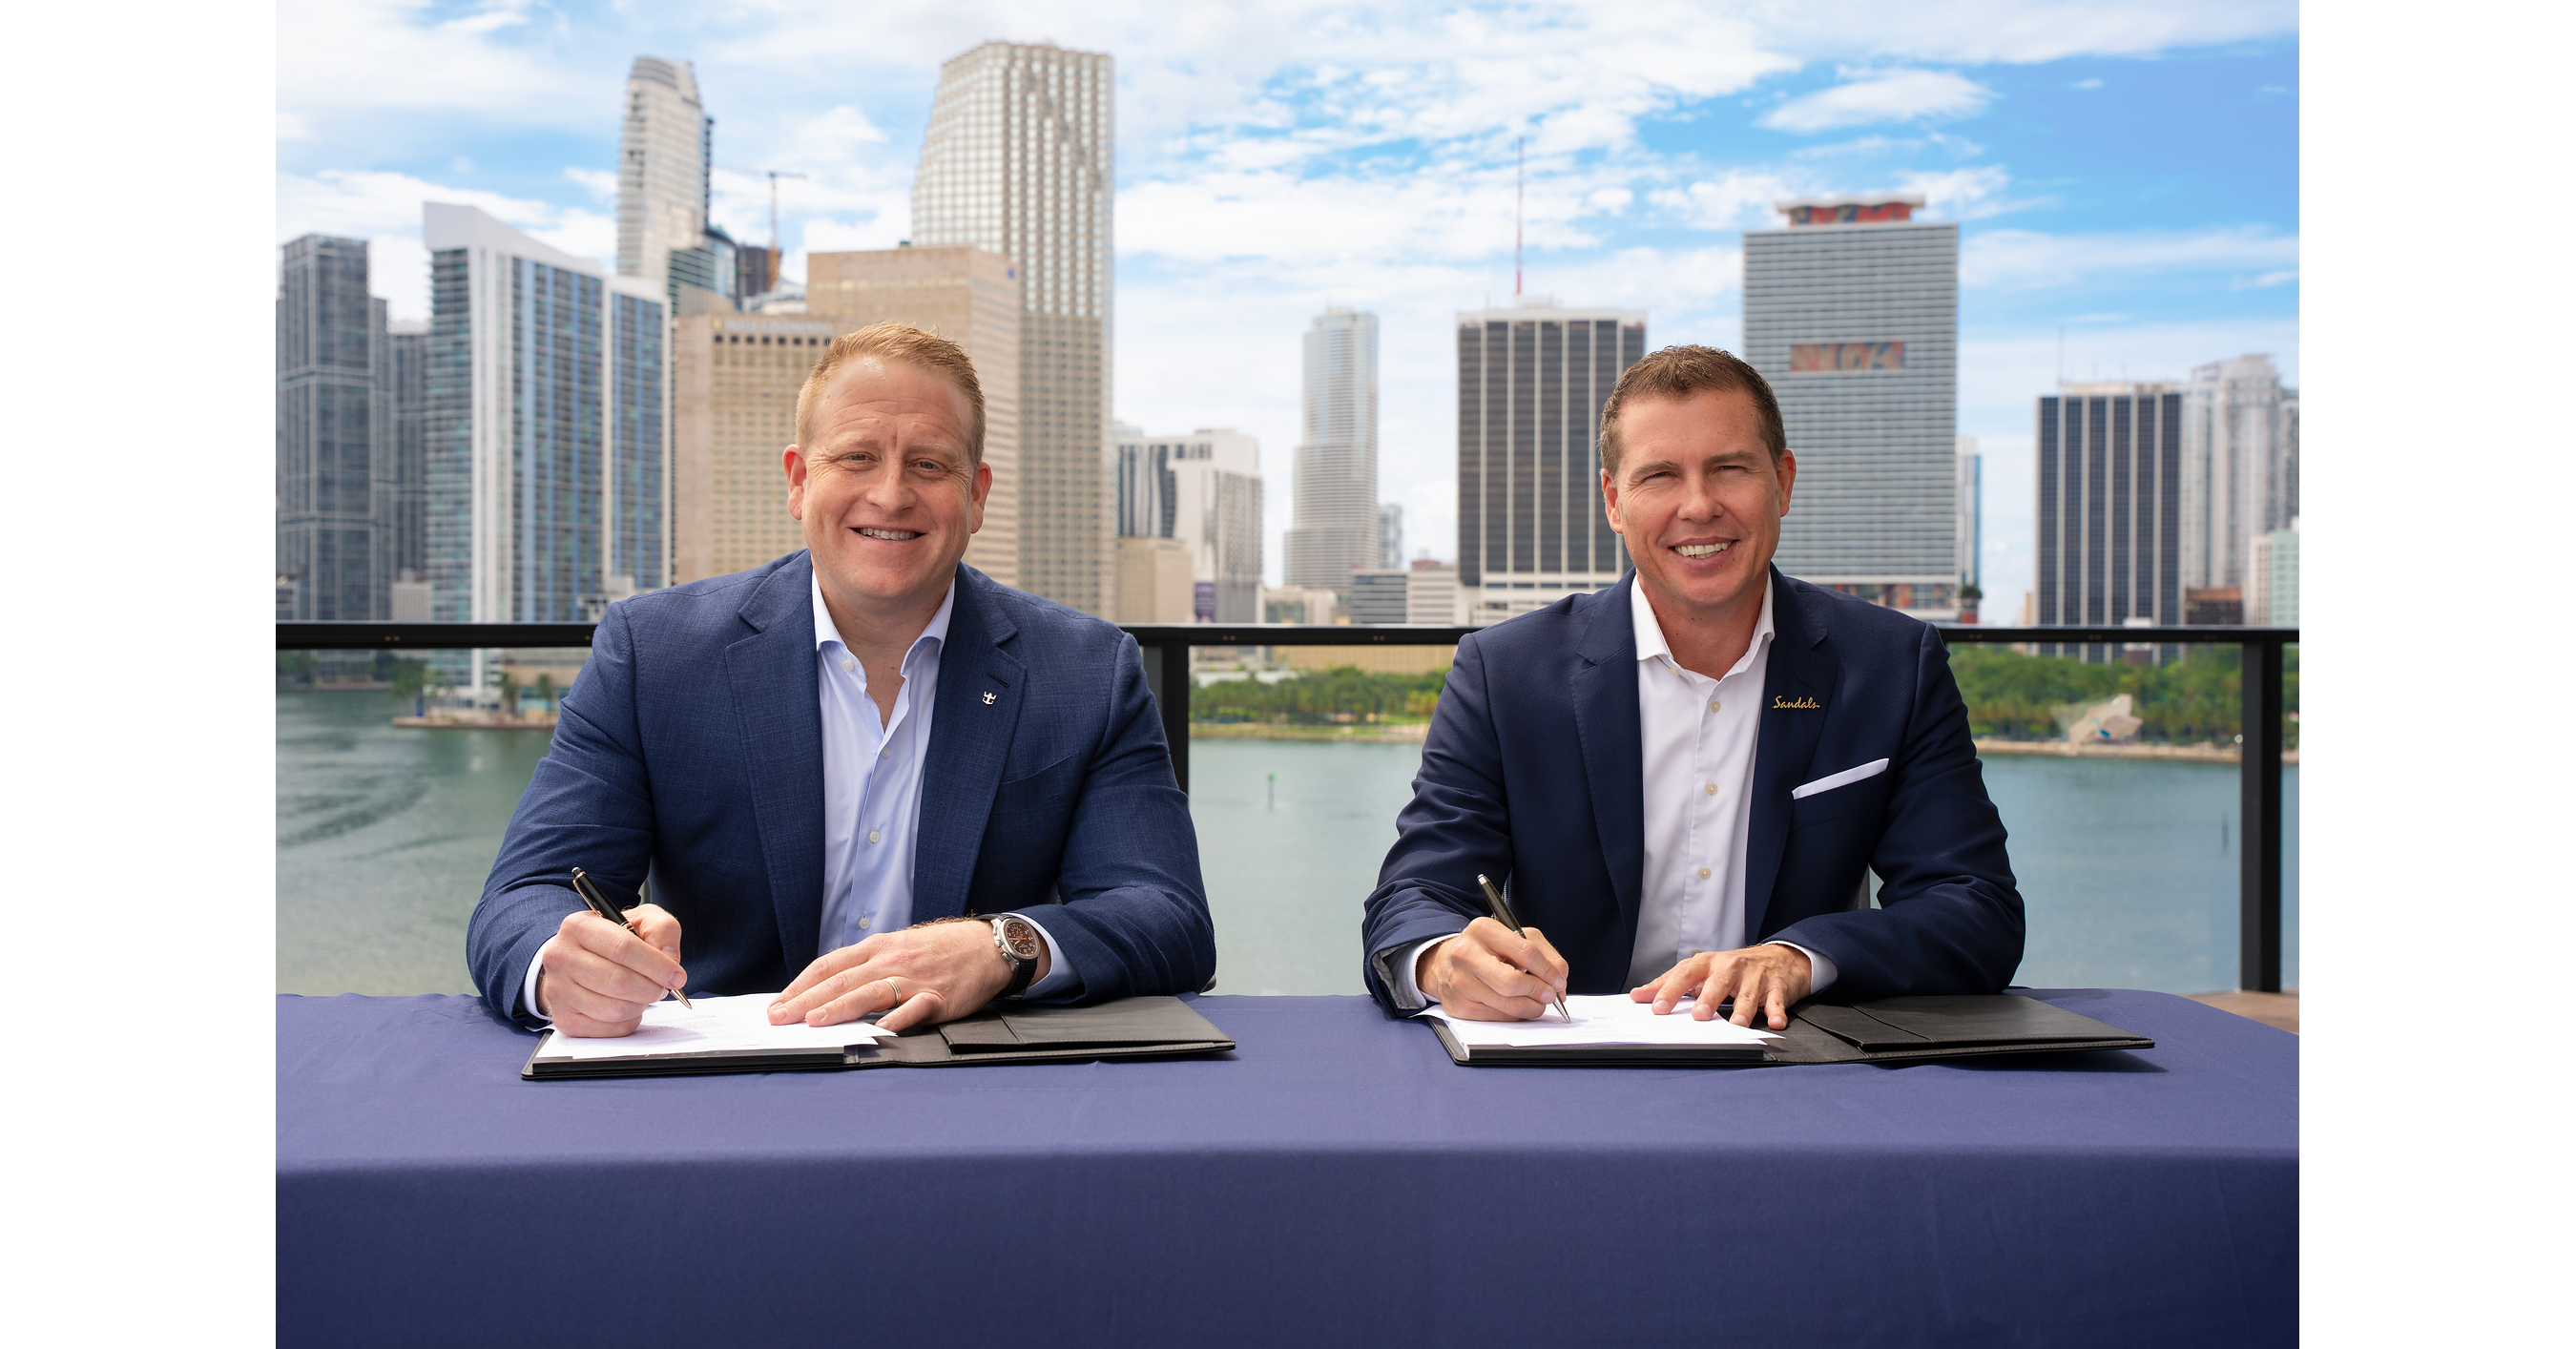
Royal Caribbean Group will acquire a 50% equity interest in Sandals and Beaches Resorts for approximately $3 billion, valuing the business at roughly 10x forward EBITDA. The transaction, funded with committed Morgan Stanley debt financing and expected to close in early 2027, expands Royal Caribbean into all-inclusive resorts and the estimated $2 trillion global vacation market. Management expects the partnership to accelerate Sandals and Beaches expansion, broaden cross-portfolio distribution and loyalty engagement, and be accretive to Royal Caribbean earnings next year.
Analysis
The strategic value is not the resort EBITDA alone; it is ownership of the Caribbean customer relationship across more booking occasions. If RCL can attach resort stays to its loyalty base and use its direct-marketing infrastructure to lower Sandals' customer-acquisition cost, the JV could support higher occupancy and reduce dependence on travel-agent distribution. The offset is that bundling cruises, private destinations and resorts may cannibalize some higher-yield cruise itineraries rather than create incremental trips, making net revenue yield—not cross-selling headlines—the key operating proof point.
The market should focus on capital allocation and financing, not the stated earnings accretion. A debt-funded 50% stake at roughly 10x forward EBITDA is unlikely to be meaningfully value-accretive unless Sandals has credible unit-growth runway, materially lower cost of capital, or significant revenue synergies; RCL is exchanging balance-sheet flexibility for an asset with weather, insurance and Caribbean airlift exposure. In the next 1-3 months, disclosure of debt tenor, coupon, leverage trajectory and any pro forma EBITDA contribution will determine whether equity treats this as disciplined platform expansion or a late-cycle multiple expansion.
CCL and NCLH face a modest competitive read-through: RCL's broader vacation ecosystem can strengthen loyalty retention among Caribbean-focused households, especially families through Beaches, but neither competitor is directly impaired without evidence of bundled pricing or loyalty conversion. Asset-light lodging operators with Caribbean all-inclusive exposure, notably H, MAR and HLT, could see distribution and development competition increase over 6-18 months if RCL uses its customer database to underwrite new resort construction. Advisory fee economics for MS, PJT, BAC and PWP are immaterial relative to their earnings bases; this is not a catalyst for those shares.
Contrarian view: the announcement may be initially over-rewarded if investors capitalize speculative cross-sell revenue before transaction financials are available. The thesis is falsified positively by post-close resort EBITDA growth above the acquisition underwriting case alongside stable RCL net leverage and no reduction in cruise yield guidance; it is falsified negatively by higher funding costs, a ratings-pressure narrative, hurricane-related disruption, or evidence that resort expansion competes for the same discretionary-vacation wallet as cruises.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Do not chase an immediate RCL rally solely on strategic language. Establish a 1-3 month watch position only after committed-financing terms and pro forma leverage are disclosed; add if the implied after-tax funding cost is below the acquired EBITDA yield and management reaffirms cruise yield and deleveraging targets.
- Use a tactical pair trade: long RCL / short NCLH over the next 3-6 months only if RCL underperforms on financing-related concerns despite unchanged booking commentary. Target 10-15% relative upside from RCL's superior loyalty and balance-sheet position; exit if RCL raises leverage targets or NCLH reports materially stronger Caribbean pricing.
- For existing RCL longs, buy downside protection through options spanning the expected early-2027 close rather than reducing the core position outright. The principal downside catalyst is a debt-market repricing or ratings concern, not an immediate deterioration in cruise demand.
- Monitor quarterly disclosures for direct-booking mix, loyalty-member penetration, Caribbean occupancy/yield, and capital commitments to new resort development. Treat any guidance for resort capex, guarantees, or incremental debt beyond the acquisition funding as a signal to reassess exposure.
More News
- Royal Caribbean to buy 50% stake in Sandals Resorts for $3 bln
- Why Viking Therapeutics Stock Skyrocketed on Tuesday
- Royal Caribbean nears $3 billion deal to take 50% equity stake in Sandals
- Meta's quick success with Muse puts consumers back in the driver's seat of the AI trade
- Meta AI agent triggers heavy selloff in banks, insurers, and travel stocks
- May Mobility's SPAC Merger: Is This a Road to Nowhere for Investors?