
iRobot Unveils Roomba® Duo at IFA 2026, Proving the Future of Floor Care Has a Familiar Name
Source: PR Newswire
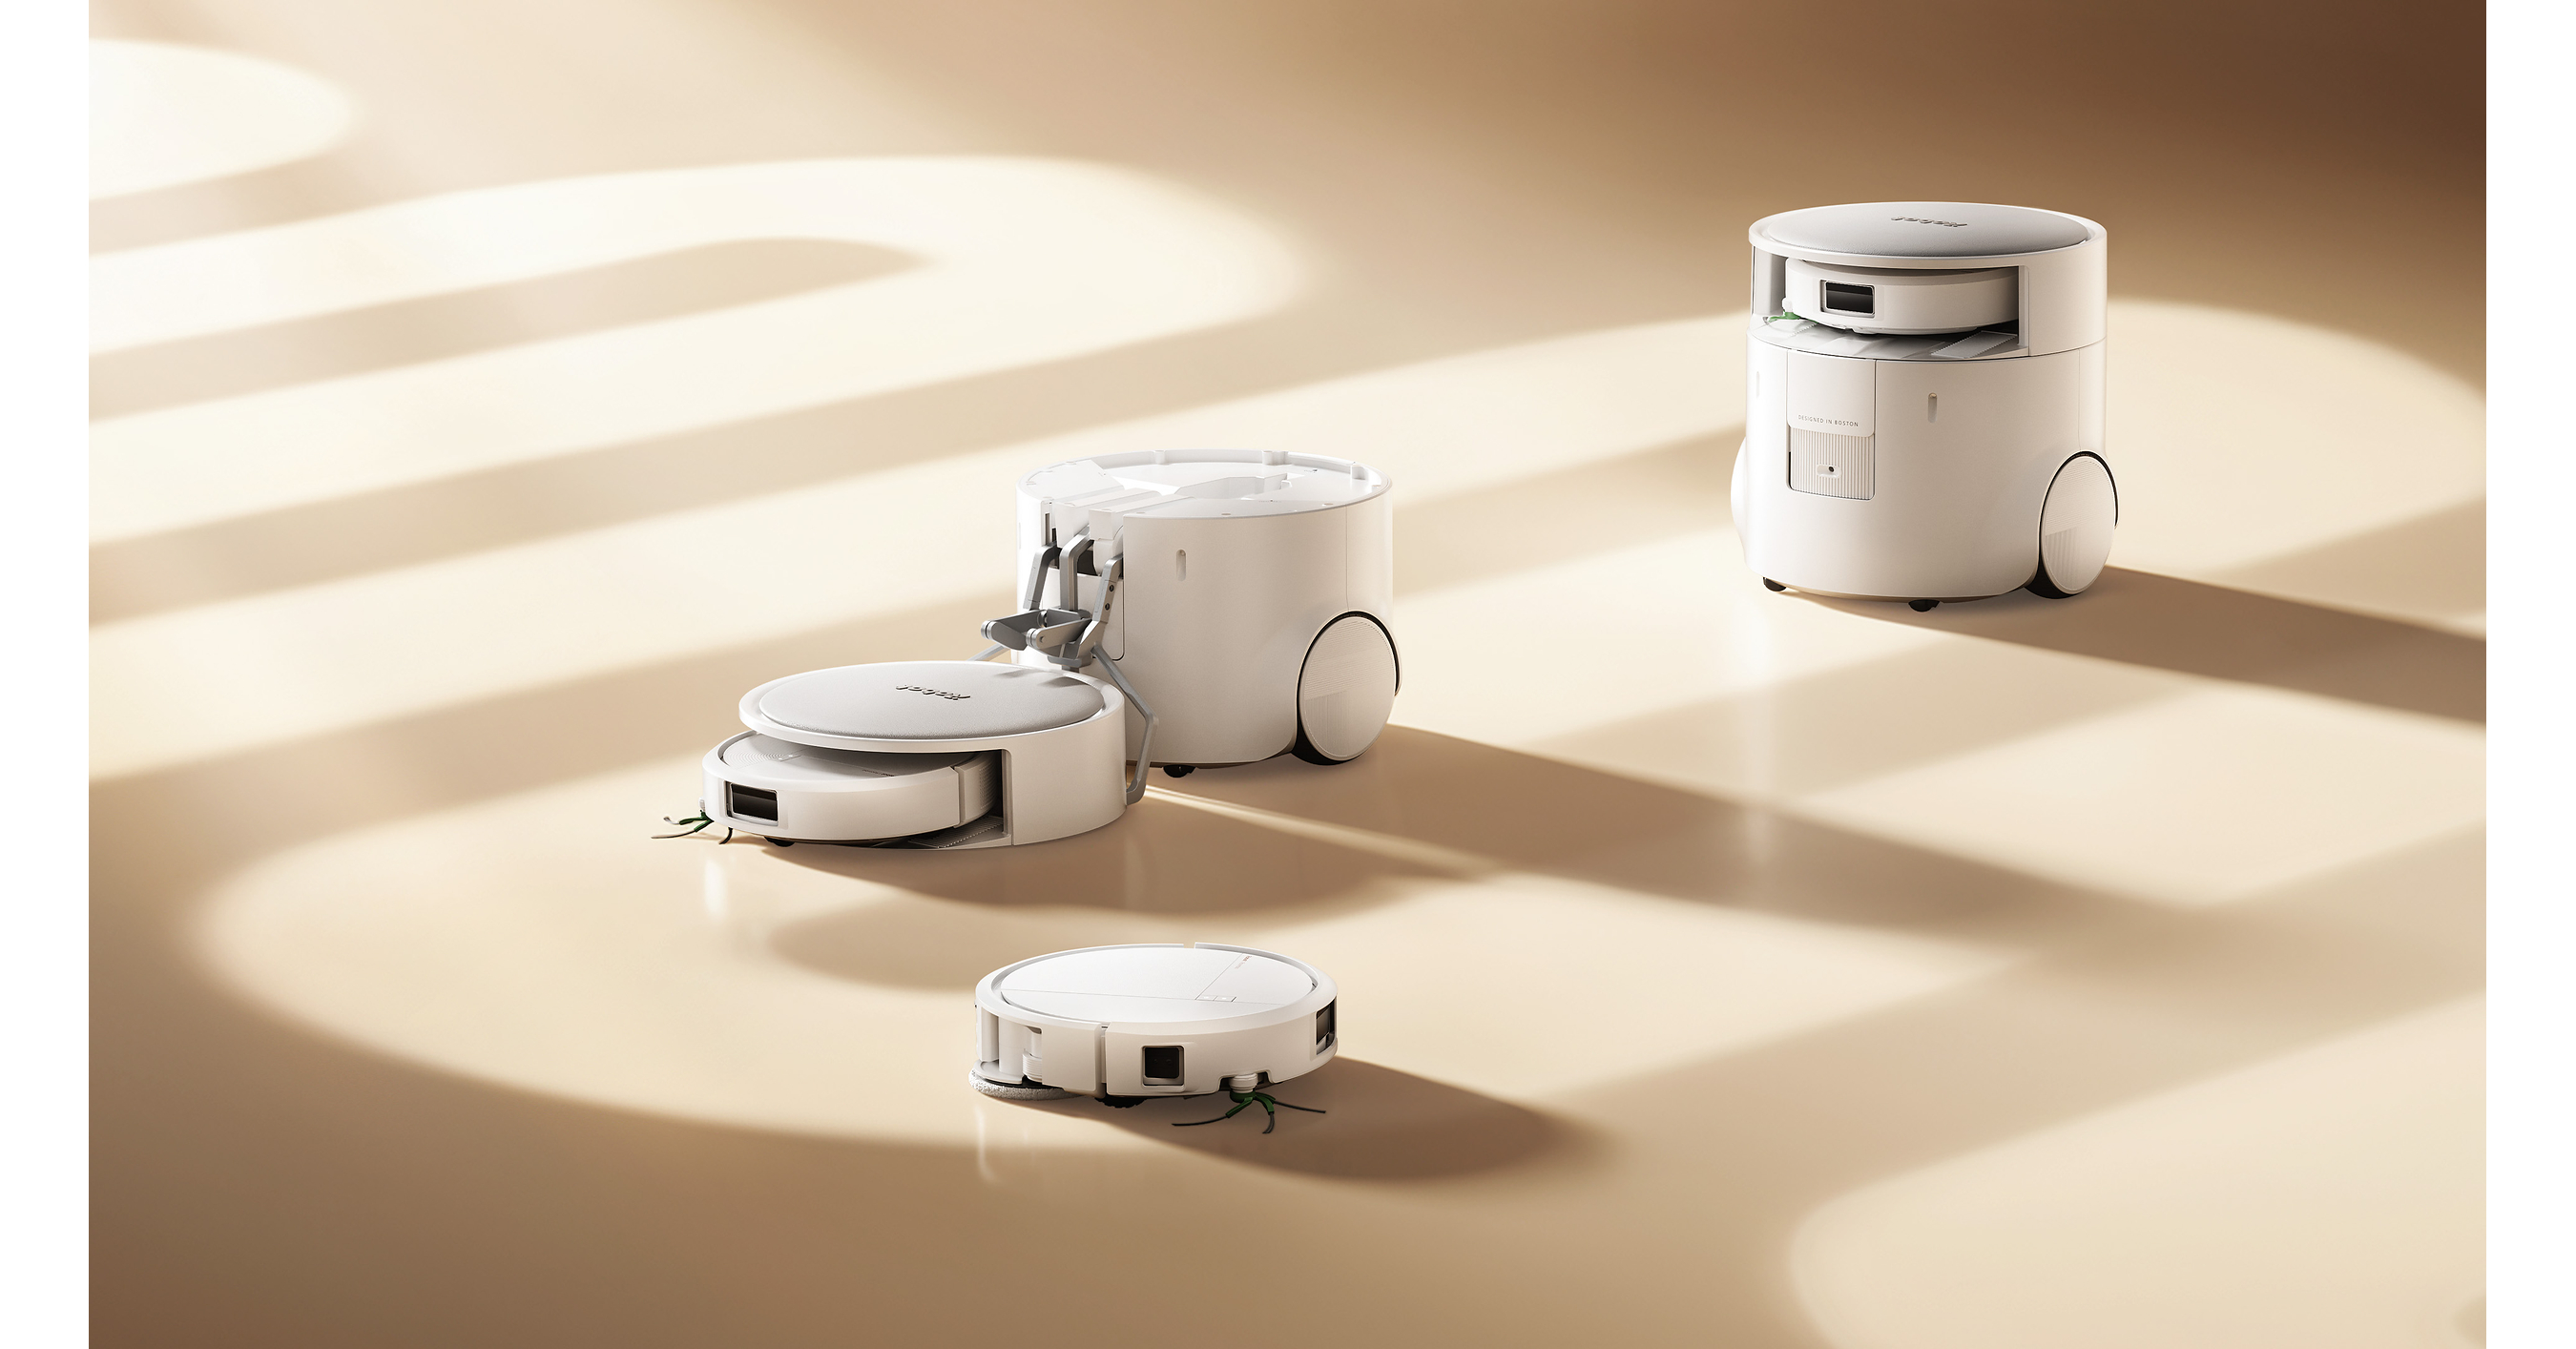
iRobot unveiled the Roomba Duo at IFA 2026, its first dual-unit robot vacuum and mop that pairs a main steam-mopping/vacuuming unit with an ultra-slim companion robot for tight spaces. The system uses a shared home map and AI coordination, with the main unit delivering wet-and-dry scrubbing via a 46N (≈4.7kg) PowerSpin Max Roller Mop and autonomous maintenance through a centralized AutoWash dock. While this is a product launch (no financial figures provided), it positions iRobot for differentiation in automated floor care coverage and autonomy.
Analysis
This is more an optionality event than a fundamental inflection. If the architecture works, it could re-establish differentiation in a category where software parity has been compressing pricing power, but the near-term benefit is mostly branding and channel buzz, not P&L. The bigger medium-term implication is defensive: premium incumbents will be pushed toward more complex, higher-ASP systems, which usually widens the gap between true platform leaders and lower-end assemblers.
The second-order issue is economics, not engineering. A dual-unit system raises BOM complexity, QA burden, returns risk, and after-sales service costs; those frictions can quietly erase gross-margin gains unless sell-through and attachment rates are strong. In that setup, the key watch item over the next 1-3 months is whether management can disclose pricing, preorder conversion, and a credible ship window; without that, the market should treat this as a trade-show prototype.
Contrarian view: consensus may be underestimating how much this signals category stagnation. When a company needs a two-robot ecosystem to solve coverage gaps, it is implicitly admitting the single-unit value proposition has plateaued, which means the monetization path may rely on higher ASPs rather than unit growth. If the launch fails to translate into channel commitments by the next earnings print, the stock likely gives back the headline pop and re-rates back on liquidity and dilution risk rather than product excitement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Do not chase IRBTQ on the prototype headline; wait for confirmed pricing, retail timing, and channel inventory terms before taking risk. Time horizon: next 1-2 earnings cycles.
- Watch IRBTQ for a tactical long only if management announces a real launch window and gross margin improvement on the next print; otherwise treat this as a sentiment trade with low durability. Falsifier: no preorder or shipment data by the next update.
- Pair trade idea: long IRBTQ / short SN only if subsequent details show the dual-unit format meaningfully widens performance lead at acceptable COGS. Risk/reward is asymmetric only after pricing is disclosed; before then, the trade is mostly headline beta.
- For a cleaner sector read-through, use SN as the competitor to fade on any evidence that premium floor-care ASPs are rising faster than replacement demand. If consumer demand weakens or promotions spike, the launch likely increases competitive discounting rather than share gains.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- China's economic growth quickens to 4.6% as exports surge, stimulus rolls out
- Asian stocks skid, Wall Street and bonds aided by oil slip
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge