
Yarbo da vida a la serie M en la IFA 2026, desde el prototipo del CES hasta el producto final, en tus manos
Source: PR Newswire
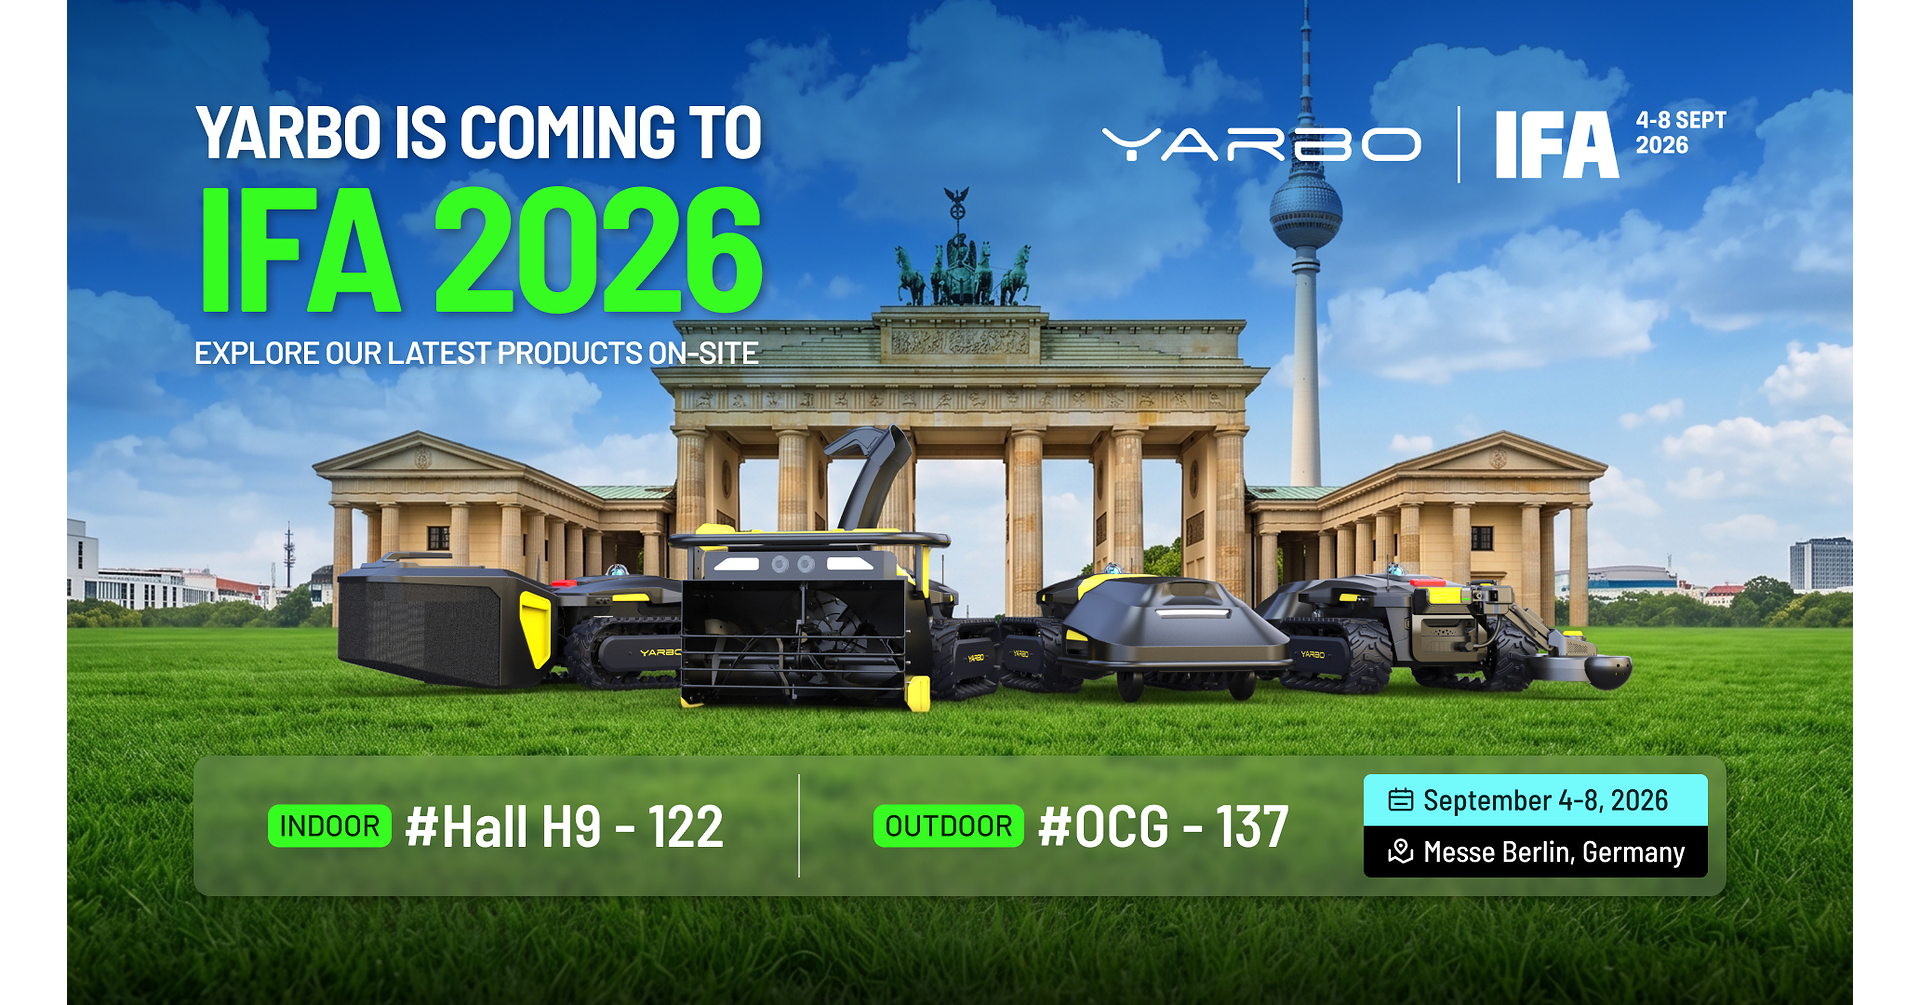
Yarbo presentará en la IFA 2026 la versión final de su serie M de robots modulares para jardinería, con configuración inicial y mapeo en ~30 minutos y carga del 10% al 90% en ~65 minutos. La plataforma apunta a ampliar la automatización a distintos tamaños de jardines y tareas (corte, retirada de nieve y recolección de hojas, con módulos adicionales planificados). En 2026 la serie M recaudó más de $3,6M con 850 patrocinadores vía crowdfunding, señalando demanda creciente, aunque sin impacto directo mensurable en mercados financieros.
Analysis
This is more of a category-validation event than a company-specific inflection. The investable read-through is that outdoor autonomy is moving from novelty to broader household use, but the economics still hinge on whether the platform can be sold through mass-market channels without expensive installation, returns, or service calls. That matters because the first-order upside is not the mower itself; the second-order upside is consumables, attachments, software, and replacement cycles, while the hidden downside is SKU complexity that can compress gross margin before scale arrives.
The market is likely to over-index on crowdfunding as proof of demand. In reality, crowdfunding typically selects for enthusiasts, not the median homeowner, so the key variable over the next 1-3 months is whether demo traffic converts into preorder velocity and whether early reviews validate reliability on uneven terrain, wet grass, and edge cases. If the product needs more support than advertised, adoption can stall quickly and push the story back into a niche premium segment.
For public comps, the clearest medium-term beneficiary is the established outdoor-equipment platform with robotic credibility, not the pure hardware upstart. Husqvarna and, to a lesser extent, Toro are better positioned to monetize category awareness through dealer relationships and accessory attach, while labor-based lawn-service models face a slower structural pressure rather than an immediate hit. The contrarian view is that modularity may ultimately be a liability: more modules raise ASP, but they also raise service burden, returns, and inventory risk, which often matters more than headline TAM.
The key falsifier is channel evidence: if unit economics, install time, and post-sale support do not improve meaningfully by the next earnings season, this remains a marketing story rather than a scalable consumer-tech platform. A sustained break in OEM commentary on autonomy, or no lift in robotic garden equipment sell-through by spring seasonality, would argue the move was overdone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate cash equity trade; treat this as a watch item until we see third-party sell-through, return rates, and gross-margin disclosure from public peers over the next 1-2 quarters.
- If you want a mild thematic expression, go long Husqvarna (HUSQ B:STO) vs short Toro (TTC) on a 1-3 month horizon: HUSQ has the cleaner robotic-garden optionality, while TTC is more exposed to conventional replacement demand. Risk/reward only works if autonomy adoption broadens; stop if TTC shows no margin pressure or HUSQ guidance stays flat.
- Set an alert on outdoor-autonomy suppliers and sensor names only if management commentary confirms design wins; otherwise avoid chasing OUST/adjacent names on this press release alone because the linkage is too indirect.
- Watch for spring 2027 consumer-season channel checks: if robotic mower attach rates and accessory sales do not accelerate, fade any long-in-the-toes exposure in HUSQ B and rotate back to traditional equipment leaders.
- If seeking event-driven upside, use a small option-style allocation rather than outright equity exposure; the better entry would be after the first wave of reviews and dealer feedback, when real demand can be separated from launch hype.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- What's behind the sell-off in AI neocloud stocks like CoreWeave and Nebius
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’