
Angel Aligner upravuje na európskom trhu torzné výstupky na „tlakové body"
Source: PR Newswire
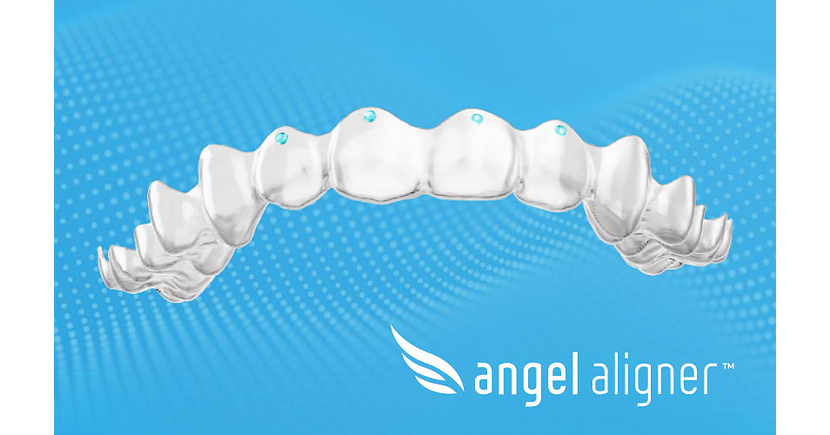
Angelalign launched its new pressure-point feature for clear aligners in Europe, replacing torsion attachments for torque corrections. The company says the single-pressure-point configuration increases tooth-contact area by 25%, improving force predictability and tooth-movement control. The feature is initially limited to torque correction, with future expansion planned for rotation and intrusion applications and eventual global distribution.
Analysis
This is unlikely to change near-term estimates: a single-feature European rollout has no disclosed case-volume, pricing, remake-rate, or clinician-adoption data. The investable implication is therefore not the feature itself, but whether it reduces treatment refinements and chair-time enough to improve clinician retention—a key weakness versus Invisalign’s (ALGN) installed-base and workflow advantage. Without independently reported conversion or retention metrics, the announcement should be treated as product marketing rather than a revenue catalyst.
If the design produces more predictable complex tooth movement, Angelalign could gain disproportionate traction in specialist orthodontist accounts, where clinical reliability matters more than entry-level case pricing. That would pressure regional clear-aligner competitors before it affects ALGN, but meaningful share transfer requires software workflow integration, training capacity, and reimbursement-neutral economics; feature parity alone rarely dislodges incumbent prescribing behavior. Any benefit to 6699.HK is a 6-18 month operating-leverage story through lower remake/support costs and higher repeat ordering, not a days-to-weeks rerating event.
Contrarian view: the claimed precision advantage may initially increase support burden if treatment-planning teams and doctors use the feature inconsistently. A broader rollout before real-world validation could elevate refinements, eroding gross margin and damaging clinician trust. The thesis is falsified if subsequent disclosures show no improvement in Europe case volumes, average revenue per case, or gross margin versus the pre-launch baseline over two reporting periods.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No new directional position on this announcement alone; liquidity, valuation, European revenue mix, and post-launch clinical KPI disclosure are missing. Reassess 6699.HK only after 1-2 quarterly reports provide regional case growth, refinement/remake rates, and gross-margin progression.
- Set a 6-12 month relative-value watch: long 6699.HK / short ALGN only if Angel demonstrates sustained European case-volume outgrowth of at least 10 percentage points and stable-to-improving gross margin. The pair limits broad elective-dental demand risk; exit if ALGN’s international case growth reaccelerates or Angel’s margin falls on support costs.
- For ALGN holders, do not extrapolate a competitive threat yet. Monitor European doctor utilization and Invisalign refinement commentary at the next earnings call; evidence of share loss in specialist cases, rather than a feature press release, would be the catalyst to reduce exposure.
More News
- FAA says Boeing 737 Max software glitch not a flight-safety issue
- Your health insurance premiums may take a big jump in 2027 — here's why
- Anthropic to invest $100 million to train AI engineer talent
- Big Pharma turns to China for new drugs as patent cliff drives multibillion-dollar deals
- Why Lilly and Novo are betting on amylin to power a new wave of obesity drugs after GLP-1s
- Why AMD Stock Jumped 30% in September