
/C O R R E C T I O N -- Electra.aero/
Source: PR Newswire
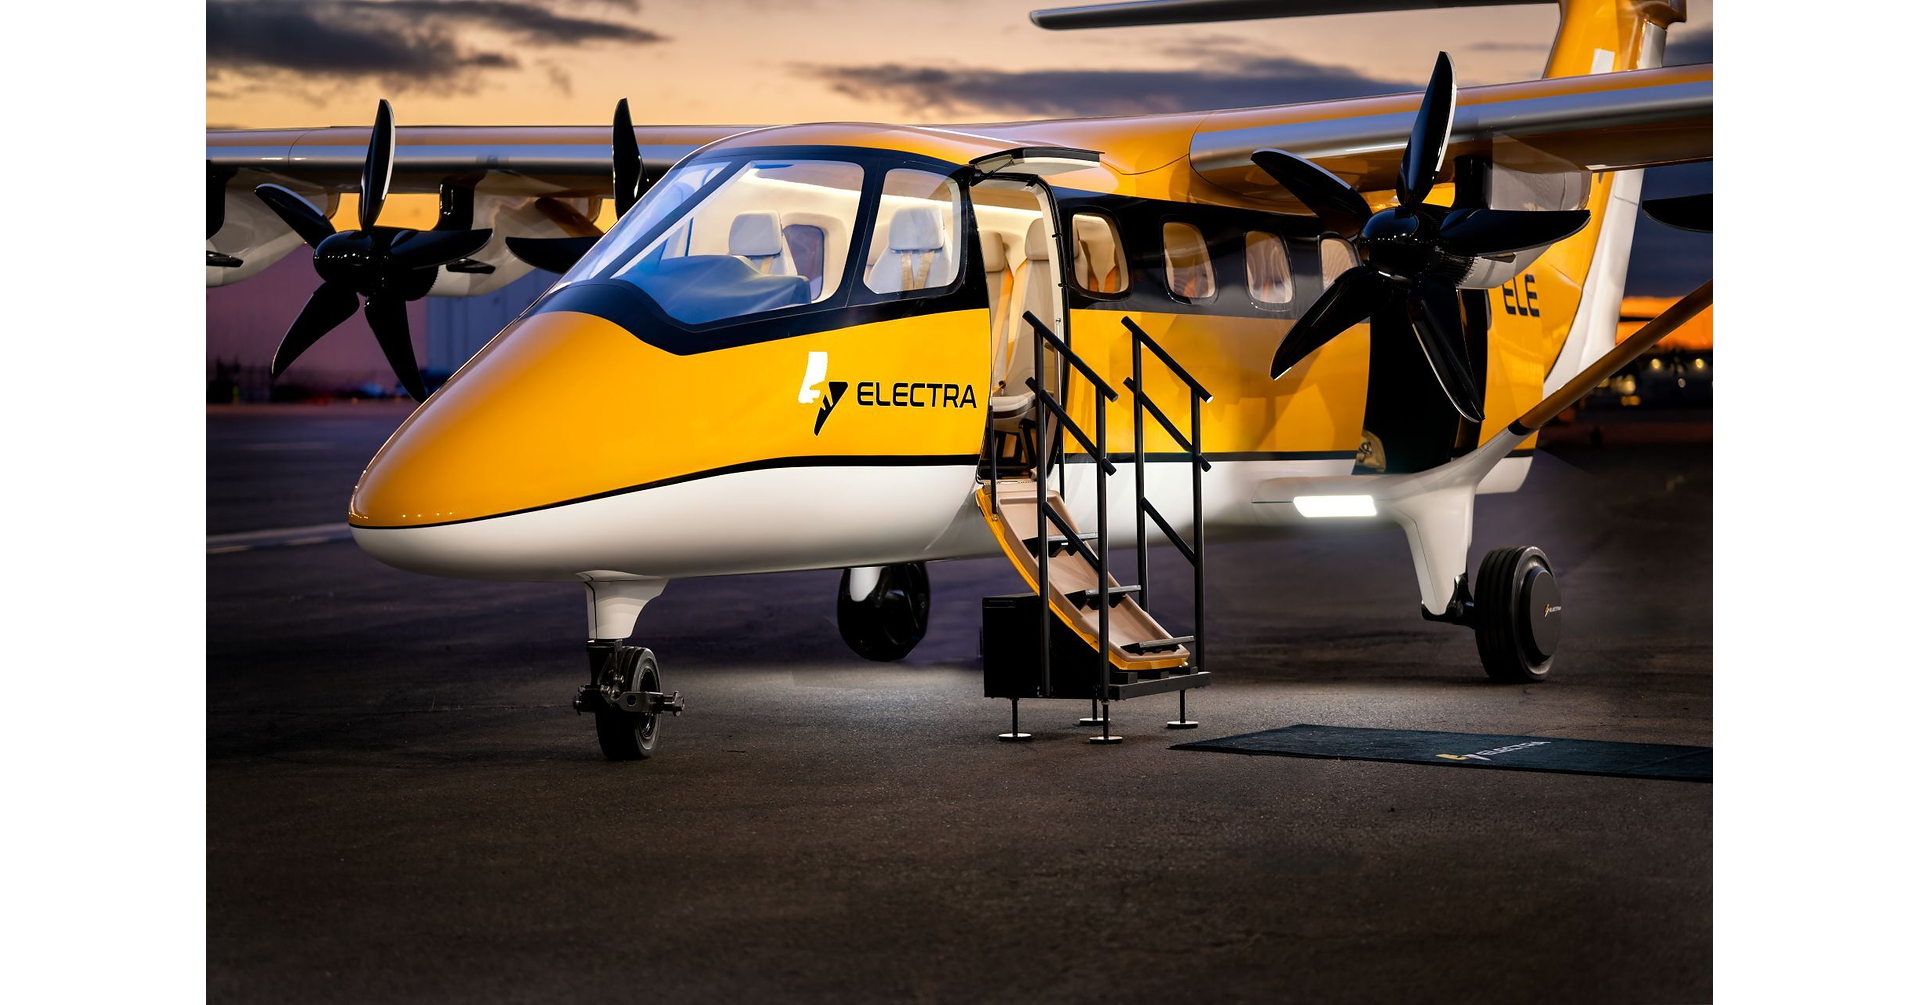
Electra signed an airframe manufacturing and assembly agreement with The Atlas Group for its nine-passenger hybrid-electric EL9 Ultra Short aircraft, with flight-test and certification airframe work beginning in September 2026 and initial deliveries expected in 2027. The company targets commercial service in 2030 and plans an $850 million Ohio production facility designed to support up to 800 aircraft annually and nearly 2,000 jobs. Electra cites more than 2,200 provisional orders from over 60 operators, including a Bristow pre-delivery agreement for five aircraft plus options for 45, though all commercial volumes remain contingent on certification.
Analysis
The investable read-through is concentrated in Safran rather than Electra’s strategic investors: a life-of-program propulsion position creates potential aftermarket and content-per-aircraft exposure, but the program is too far from revenue recognition for this to move consensus estimates in the next 12 months. The airframe award chiefly de-risks industrialization execution for a private OEM; it does not validate unit economics, financing availability, or conversion of nonbinding commercial interest into firm backlog. Honeywell’s exposure appears strategically useful but economically immaterial absent disclosure of avionics, controls, or power-management content.
The key near-term catalyst is certification-test progress, not factory capacity. A novel propulsion/flight-control certification path can create multi-year schedule slippage, and each delay raises Electra’s funding requirement before meaningful deliveries, potentially weakening supplier economics or forcing repricing of commitments. The 2030 service target leaves public-equity beneficiaries exposed to a long-duration option whose value will be driven by FAA milestone completion, demonstrated dispatch reliability, and independently verified operating cost rather than promotional market-size estimates.
Contrarian view: the apparent competitive advantage versus eVTOLs may be real only if infrastructure permissions allow frequent operations from small sites; local zoning, noise measurement standards, and operator insurance requirements could preserve conventional-airport economics despite short-field capability. Conversely, if certification is achieved on schedule, hybrid-electric fixed-wing aircraft could take share from helicopter operators and regional turboprops before pure eVTOL platforms reach scalable utilization, pressuring the strategic narrative around VTOL-adjacent peers.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in SAF/SAFRY on this announcement; place a 6-18 month watch item for disclosed TG600 production-rate commitments, certification-test milestones, and any supplier revenue guidance. Upgrade only if Safran quantifies program content or backlog sufficient to affect segment estimates.
- Maintain a tactical long SAF versus a basket of pre-revenue eVTOL proxies only after verified FAA flight-test progress; use a 9-12 month horizon and a tight thesis stop if certification timing slips or Electra raises capital on distressed terms. The trade expresses hybrid-electric certification advantage, not near-term EL9 revenue.
- Avoid treating VTOL as a clean beneficiary despite Bristow’s customer relationship: monitor whether Bristow converts deposits into binding aircraft commitments and publishes route-level utilization economics. A cancellation, deposit refund, or reduced option exercise would be an early falsification signal for regional-demand assumptions.
- Do not add LMT or HONA solely on strategic-investor exposure. Require evidence of incremental defense procurement, subsystem content, or disclosed equity-value uplift; otherwise the likely financial impact remains below materiality thresholds.
More News
- U.S. 10-yr yields surge past 5%: which stocks are most vulnerable?
- Honeywell Aero CEO calls planned GE Aerospace-CPP deal ’positive’ for industry
- Ducommun wins $35M contract for PAC-3 missile assemblies
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Saudi coalition says Houthi drone destroyed near Mecca
- Iran war increasing inflation, straining US munitions: congressional report