
SANY Heavy Truck stellt auf der IAA Transportation 2026 sein serienreifes Portfolio an Elektro-Lkw vor
Source: PR Newswire
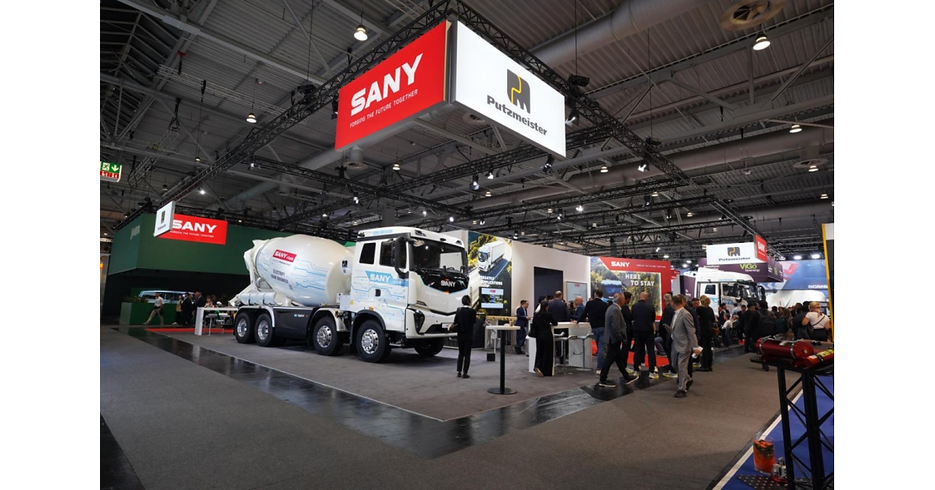
SANY Heavy Truck debuted its production-ready European battery-electric truck portfolio at IAA Transportation 2026, led by the SE636 heavy-duty model with a 636-kWh battery and up to 500 km of stated range. The 4x2 truck, which weighs 10.9 tonnes empty, has EU whole-vehicle type approval and is already operating in Germany, Turkey and other European markets. SANY said more than 70,000 of its electric heavy trucks are deployed globally, while its European vehicles have accumulated over 20 million km across 15 markets since 2022, supported by roughly 650 service workshops.
Analysis
The relevant market signal is not a single product launch but a potential pricing and utilization challenge to European heavy-truck incumbents. A credible Chinese battery-electric entrant with localized aftersales coverage reduces the moat historically provided by dealer density and fleet uptime, especially in return-to-base applications where range anxiety is less binding. Daimler Truck (DTG.DE), Volvo (VOLV-B.ST) and Traton (8TRA.DE) face the greatest risk in Germany, Benelux and Central Europe; the pressure would initially appear in order pricing, financing incentives and residual-value assumptions rather than lost reported volume.
Near term, this is not independently sufficient to revise earnings: promotional claims, fleet economics, charging access, warranty terms and delivered-unit reliability remain the key missing data. Over the next 1-3 months, watch IAA fleet-test feedback, tender wins, European registration data and whether incumbents respond with discounts. A sustained rise in Chinese OEM share over 6-18 months would be more consequential for suppliers: lower-cost vertically integrated platforms could pressure content and pricing for European powertrain/component suppliers such as ZF-linked exposure and Forvia (FRVIA.PA), while charging providers and depot-electrification integrators benefit regardless of OEM share.
Consensus may overstate the immediate disruption because long-haul fleets buy uptime, financing and resale certainty, not headline battery capacity. Incumbents retain captive service, fleet-management and leasing advantages, while EU trade or cybersecurity restrictions could materially slow Chinese penetration. Conversely, the threat is underappreciated if Chinese OEMs use subsidized financing and aggressive residual guarantees: that would force a sector-wide margin reset before registration share looks meaningful.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- No immediate directional trade solely on this release; create a quarterly European BEV heavy-truck registration watchlist versus DTG.DE, VOLV-B.ST and 8TRA.DE. Escalate only if Chinese brands achieve >5% of new BEV heavy-truck registrations in Germany/Benelux or win named multi-year fleet tenders.
- Maintain a 6-12 month relative-value bias: long VOLV-B.ST / short 8TRA.DE, sized modestly. Volvo's broader service and financing ecosystem should better defend pricing; exit if Traton's European order intake or adjusted operating-margin guidance outperforms Volvo by >100 bps for two consecutive quarters.
- For a higher-beta disruption hedge, buy 6-12 month downside protection on DTG.DE around earnings dates rather than shorting outright. The thesis requires evidence of lower European truck pricing, weaker residual-value guidance or a service-cost increase; absent those signals, premium decay is the primary risk.
- Screen charging and depot-infrastructure beneficiaries rather than OEMs for a structural long basket, including ABB (ABBN.SW) and Alfen (ALFEN.AS). Entry should follow evidence of fleet depot-capex commitments, since vehicle demonstrations do not establish charging-equipment revenue conversion.
More News
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- MBS and Saudi Arabia Face Crisis With Key Oil Pipeline Shut for Weeks
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Chinese investors rush into US stocks as Beijing opens wider path overseas
- Factbox-How AI leaders and world governments react to ’AI doom’ fears
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for CFA Charterholders: An Evidence Standard
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data