
Sterling Infrastructure: A Long Growth Runway Ahead
Source: seekingalpha.com
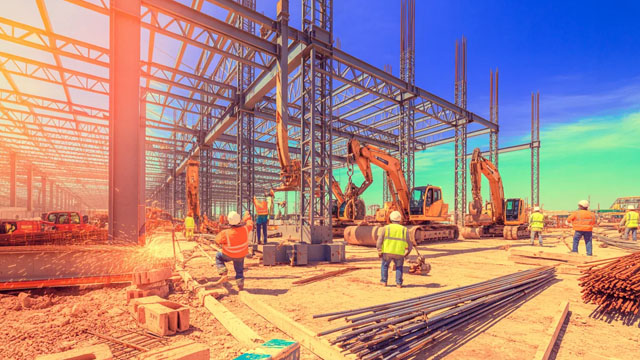
Sterling Infrastructure is rated Buy, with robust data-center demand, strong backlog growth and a multiyear growth runway supporting the outlook. Reported backlog is up 116%, while margin initiatives target a 300–500 bps uplift. The CEC acquisition adds electrical-services capabilities and opportunities for cross-selling and deeper customer relationships.
Analysis
The key question is whether backlog growth converts into profitable, timely revenue—not whether data-center demand remains a compelling theme. Phased campus construction can create a long visibility window, but project timing, customer concentration, and labor or electrical-equipment availability may make reported backlog less durable than it appears. CEC could improve Sterling’s ability to capture more work per customer; until cross-selling and acquired-business margins show up in reported results, treat that as a potential advantage rather than proven synergy. If execution is strong, Sterling may gain share from contractors with less electrical capability; if capacity is tight, labor and subcontractor costs could absorb some of the benefit.
Near term, optimistic positioning around data-center infrastructure raises the risk that good news is already reflected in the stock; the supplied information does not establish valuation or consensus expectations. Over 1–3 months, watch quarterly organic backlog, conversion to revenue, segment margins, and management’s evidence of CEC cross-selling. Over 6–18 months, phased campus schedules and margin delivery determine whether growth supports durable earnings rather than a temporary project cycle. The contrarian risk is that headline backlog growth masks delayed starts or low-quality work. A thesis break would be repeated slippage in backlog conversion, weakening margins despite the stated improvement program, or evidence that customer concentration leaves results dependent on a small number of campus schedules.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Constructive but not an automatic chase: consider a measured STRL long only after checking current valuation and the next earnings report’s organic backlog and margin detail. The article provides no basis for a price target or valuation call.
- Use quarterly results as the 1–3 month catalyst test: seek evidence that backlog is converting to revenue and that CEC is contributing through cross-selling or improved project economics. If those data are unavailable, keep the name on an alert list rather than underwriting the synergy.
- For a relative-value expression, compare STRL with larger infrastructure contractors such as Quanta Services and broader construction exposure; do not assume STRL will outperform without confirming valuation, backlog quality, and execution differences.
- Trim or revisit the thesis if backlog conversion repeatedly slips, margins fail to improve, or management flags delayed campus phases. Conversely, sustained conversion and margin progress would support holding through the longer data-center buildout.
More News
- Anthropic's third-quarter revenue is said to hit $16.8 billion ahead of IPO
- Elon Musk says Trump is 'ultimately' responsible for any curbs on Ukraine's Starshield systems
- SK Hynix seeks U.S. chip equipment exports to China tied to new factory
- Dell stock plunges 11%, leading data center sell-off on concerns about 'enterprise AI timing'
- AI infrastructure stocks tumble. Here's a few reasons for the sell-off
- UBS considers leaving Switzerland over capital rule plans, WSJ reports
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Live Event Center, In-App Documents, and Faster Transcripts
- How to Automate Equity Research Workflows: A Control-First Guide