
Oil’s Plunge Below $100 Doesn’t Mean Markets Are Out of Jeopardy
Source: Bloomberg
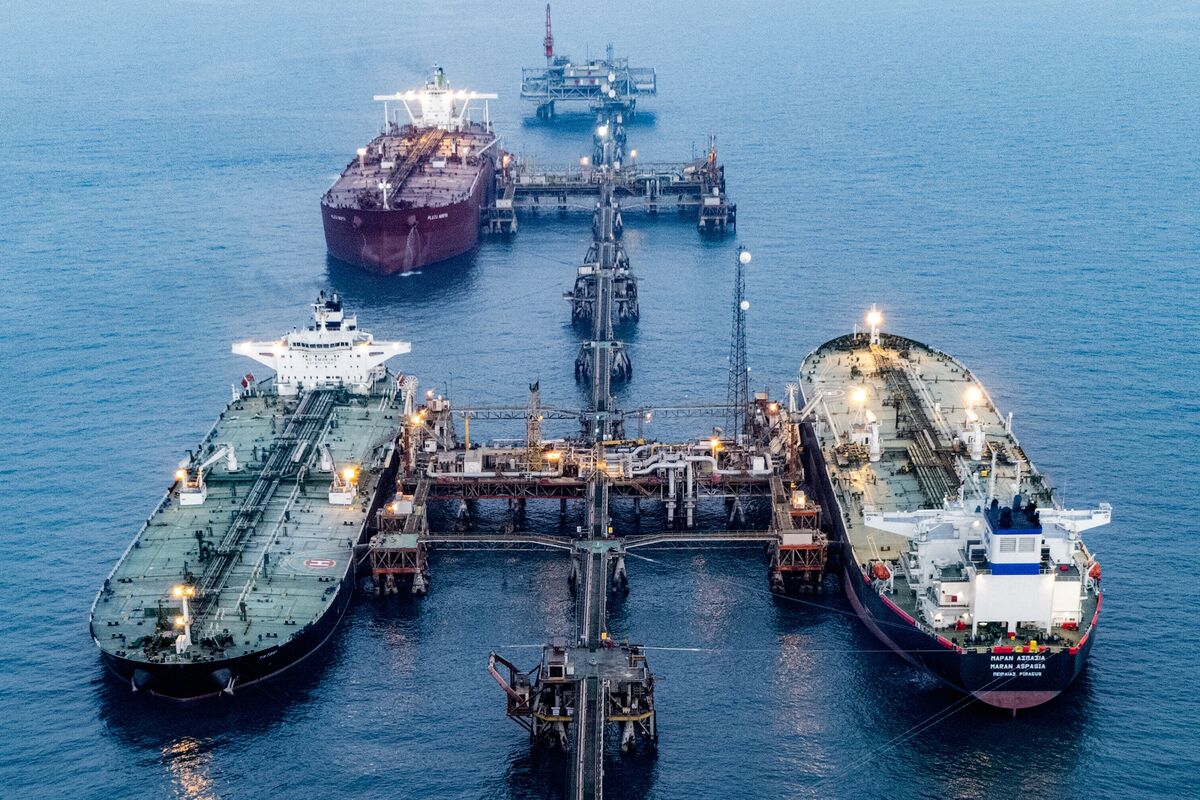
Crude oil fell below $100 as traders unwound bets on an escalation in the conflict. The article cautions that peace remains uncertain, so the price decline does not eliminate geopolitical risk to oil markets.
Analysis
The move below a round-number oil threshold is not, by itself, evidence of durable supply relief. If the price decline reflects reduced geopolitical risk premium rather than more barrels reaching the market, the front end of the curve and physical differentials should remain firm; a disconnect would leave crude vulnerable to a fast risk-premium rebound. The key near-term distinction is therefore flat price versus deliverable supply—not the headline level.
Over days, a lower crude price can ease inflation-sensitive rates and support fuel consumers, but that benefit is conditional and may be quickly reversed by renewed escalation. Over 1–3 months, monitor the Brent time spread, physical crude differentials, shipping/insurance costs and inventory data. Persistent easing across those measures would support a genuine normalization thesis. Over 6–18 months, sustained lower prices would pressure upstream cash generation and could reduce investment, eventually tightening supply; that lag makes extrapolating a short-lived selloff risky.
The contrarian risk is that markets may be pricing diplomatic progress before it is durable. Conversely, if physical indicators ease alongside futures, paying for upside protection may be a poor trade. With no supplied company-level facts or current curve/positioning data, this is a conditional setup rather than a high-conviction directional call.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
0.00
Key Decisions for Investors
- Do not short crude solely because it crossed below $100. First verify whether Brent backwardation, physical differentials and shipping/insurance costs are also easing; if not, treat the selloff as potentially vulnerable to a risk-premium rebound.
- Watch for a defined-risk 1–3 month Brent call spread via an appropriate crude-linked instrument only if physical tightness persists while futures weaken. Size as event protection, not as a forecast; avoid entry if option pricing makes the payoff unattractive.
- If crude weakness broadens into physical markets and persists, reassess fuel-sensitive exposures such as airlines and transport rather than assuming an immediate benefit: hedges and fuel surcharges can delay or dilute earnings pass-through.
- Falsification: a sustained easing in the Brent curve and physical differentials, lower shipping/insurance costs, and inventory builds would weaken the rebound thesis. Renewed disruption or reversal in those indicators would invalidate a durable-de-escalation view.
More News
- Russia to UAE, Iran steps up diplomacy amid Trump threats: What we know
- FTSE 100 today: Stocks slump as global tech rout deepens
- Soaring freight rates give US refiners edge as crude discounts widen
- AI crush is powering one stock to sky-high valuations
- Jobs Boom Meets AI Market Turmoil
- The midterms didn’t stop the AI buildout. They simply repriced it—and OpenAI is already promising to pay up