
Roborock, IFA 2026'da İnsan Odaklı Temizliği Yeniden Tanımlıyor: Oturma Odasından Havuza Kadar Kapsamlı Bir Ekosistem Sunuyor
Source: PR Newswire
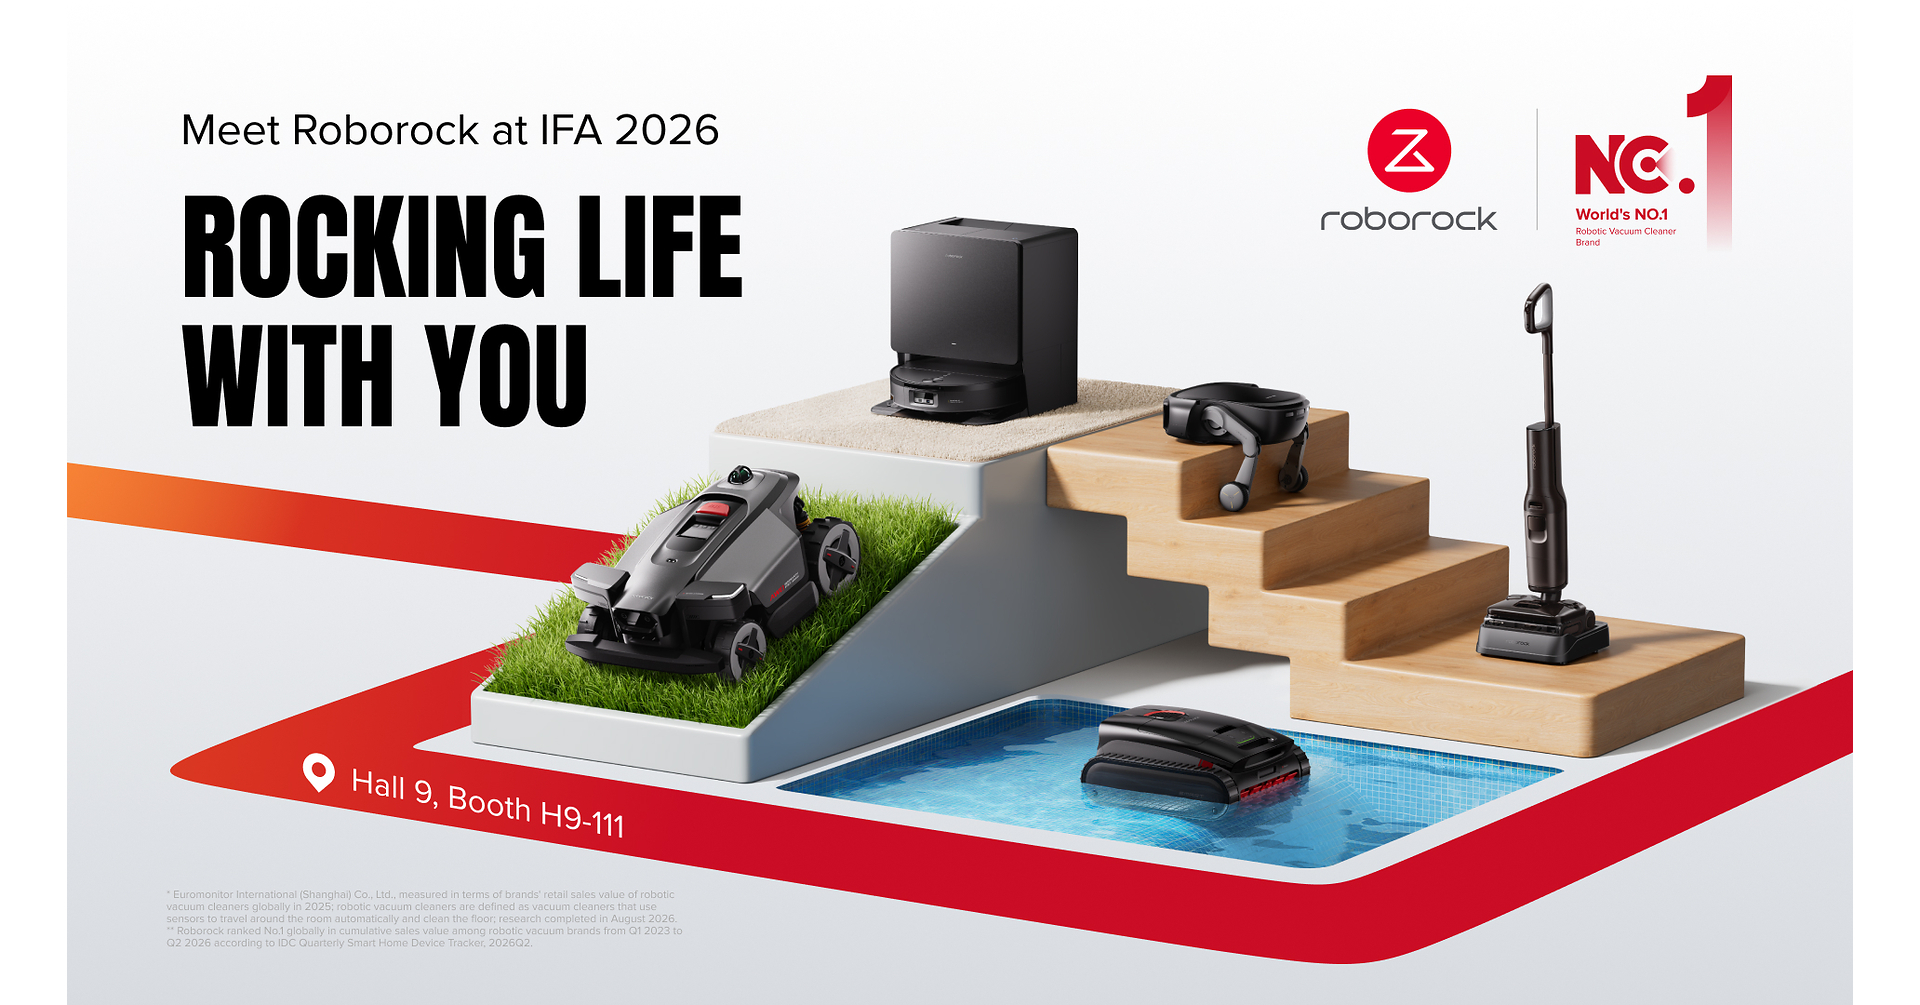
Roborock, IFA 2026’da RockAqua P1’i tanıtarak ilk havuz temizleyici ürün grubunu piyasaya çıkarıyor; 6.800 GPH emiş, 4 litrelik çöp haznesi, 3,5 saate kadar çalışma ve 3,5 saatlik hızlı şarj gibi teknik özellikler öne çıkıyor. Ayrıca robot süpürge tarafında Saros 20 Flow ve Qrevo Edge 3 Pro (36.000 Pa HyperForce®) ile dış mekan için RockNeo Q2 LiDAR çim biçme makinesini sergiliyor. Haberde yeni ortaklık olarak Real Madrid ile iş birliği de duyuruluyor; genel olarak ürün genişlemesi ve inovasyon odaklı lansmanlarla büyümeye pozitif işaret veriyor.
Analysis
This reads more like category-expansion signaling than an immediately monetizable catalyst. The key mechanism is not the launch itself, but whether Roborock can convert brand strength in floor-care into a broader household automation platform without diluting gross margin through higher warranty, servicing, and channel complexity. Outdoor adjacencies like pools and lawns are attractive because they expand TAM, but they also lengthen sales cycles and increase installation friction, which usually benefits slower-moving incumbents if execution slips.
For public comps, the most exposed losers are brands with weaker innovation cadence and limited ecosystem breadth: IRBT on core vacuum share, and to a lesser extent premium cordless/cleaning adjacencies if Roborock keeps trading up into higher-price tiers. The second-order effect is on component suppliers rather than end-market demand: LiDAR, camera modules, brushless motors, batteries, and charging systems may see incremental design wins, but only if these launches translate into volume, not just PR. A broader portfolio can also improve bargaining power with retailers, pressuring smaller competitors on shelf space and promo intensity over the next 1-3 quarters.
Contrarian view: the market may be overestimating how much revenue these announcements add near-term. The real test is whether the company can sustain ASPs and operating margin while entering categories with higher field-failure risk; if ASPs fall faster than unit growth rises, the narrative turns from premiumization to channel inventory. Watch for evidence in 1-2 earnings prints: sell-through, warranty accruals, and mix shift toward outdoor categories versus core vacuums. A meaningful reversal would be signs of discounting or slower international channel expansion, which would cap multiple upside.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate directional trade in MNIZ; treat this as a watchlist event until channel checks confirm sell-through and gross margin retention over the next 1-2 quarters.
- Relative-value: long premium home-robotics leaders with proven margin durability, short weakest legacy cleaner names (IRBT as the clearest public proxy) for a 3-6 month pair, but only if Roborock launches translate into share gains in web traffic and retailer data.
- Set an alert on MNIZ next earnings for warranty/returns and gross margin: if launch-related mix expansion comes with >150 bps margin compression, fade the premiumization story.
- Watch supplier proxies tied to LiDAR/camera/motor content for a 1-3 month catalyst only if OEM design wins are confirmed; otherwise avoid chasing the announcement tape.
- If MNIZ underperforms after the event and management reiterates guidance without raising full-year revenue, consider a tactical short into any post-IFA strength, targeting mean reversion as launch fatigue sets in.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
- Zoom and big financial firms add ‘Proof of Human’ badges from Sam Altman’s World to stop fraud and deep fakes