
Interest Rate Rise, Helen Haines, AustralianSuper: Australia Briefing
Source: Bloomberg
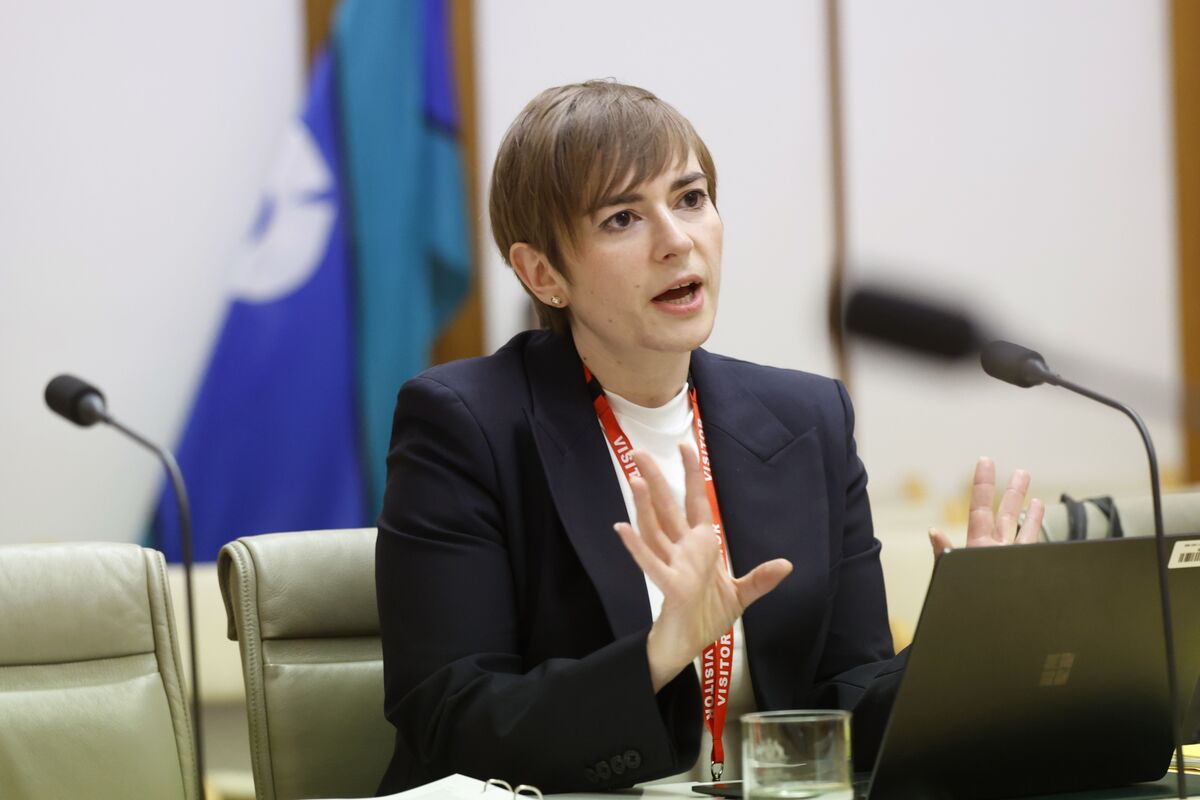
RBA Assistant Governor Sarah Hunter said the central bank is “not quite” done tackling inflation, signaling that a rate hike on Melbourne Cup day could be possible. The report provides no specific inflation figures, rate-change amount, or market reaction.
Analysis
The market-relevant risk is repricing of the Australian front end, not the interview as a standalone policy signal. If near-term rate expectations rise, duration-sensitive Australian assets—especially REITs and rate-sensitive consumer names—could face multiple pressure before any earnings downgrade appears. AUD support is less clean: higher expected rates may help near term, but a growth or credit scare could erase that advantage.
For banks, the effect is two-sided rather than an automatic positive: lending yields may reset faster, but deposit competition and mortgage arrears can offset any margin benefit. The second-order risk is weaker household spending and housing turnover feeding through to retailers and credit quality over the next several quarters.
The signal is modest and conditional. A single hawkish comment does not establish that a hike is imminent; upcoming inflation and labor data, plus RBA communication, are the catalysts over the next one to three months. Over six to eighteen months, sustained restrictive policy would matter more through household cash flow and asset valuations. The contrarian case is that the headline may exaggerate the policy shift if incoming data cool and market pricing has already moved. No company-specific earnings or valuation data are supplied, so avoid asserting a bank or sector mispricing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.20
Key Decisions for Investors
- Do not chase the headline. Track Australian overnight-indexed swap pricing and the front end of the government curve; consider a short-duration expression only if rate expectations rise further and are confirmed by data or RBA communication.
- Treat Australian REITs and rate-sensitive consumer exposure as the more direct downside watchlist if yields continue higher; avoid a blanket short absent confirmation from market pricing and earnings revisions.
- Do not assume Australian banks are a clean long on higher rates. Reassess only with evidence on deposit pricing, mortgage arrears and net interest margin guidance; those indicators would test whether repricing benefits outweigh credit and funding costs.
- A tactical AUD-positive view is conditional, not a standalone recommendation: it is falsified if the currency weakens despite higher local rate expectations, suggesting growth concerns dominate the yield differential.
More News
- Here are 4 big things we're watching in the stock market this week
- More pain may be coming for the AI trade. Why I’m not giving up on it
- Meet the homeowners who have been forced to slash their asking prices in a stagnant market. ‘It’s been a roller coaster of emotion’
- Does enough capital exist to finance everyone’s ambitious AI spending plans?
- How is the US-Israeli war on Iran causing havoc in Europe?
- 5 big analyst AI moves: ’Uniquely catalyst-rich’ months ahead for SpaceX