
PETL Introduces PETL 2 Plus: A Full Extra Charge for Your iPhone Duo in a 5,000mAh MagSafe Battery
Source: PRWeb
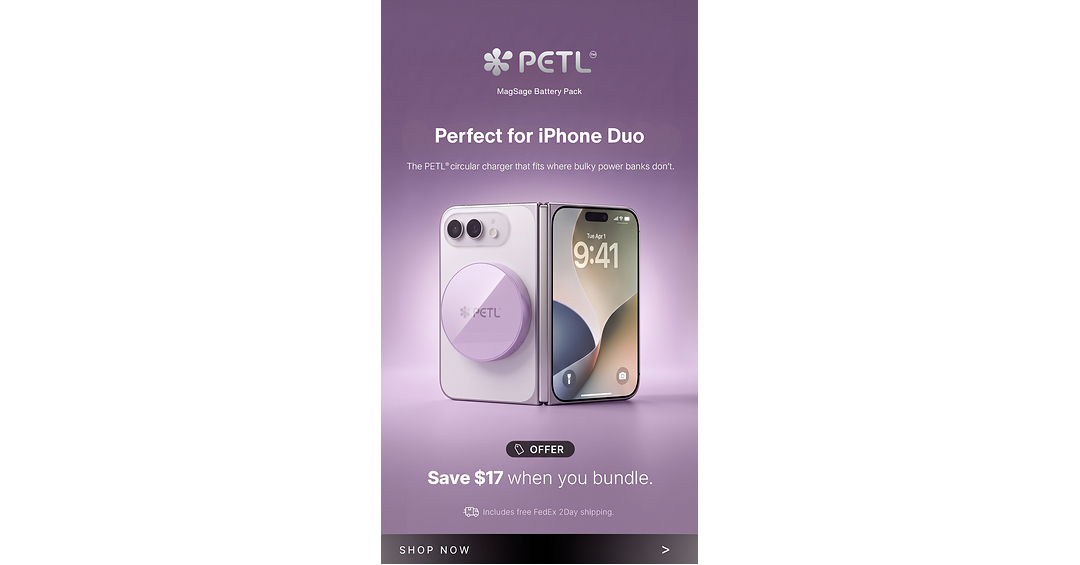
PETL launched the $89.95 PETL 2 Plus, a 5,000mAh MagSafe-compatible battery pack positioned for Apple’s iPhone Duo and Pro-class iPhones. The direct-to-consumer accessory maker reported August sales of $946,619, roughly 30% month-over-month growth, and more than 80,000 units shipped in its first year; it expects to approach 100,000 units by year-end 2026. The company is profitable at nearly $1 million in monthly revenue and plans additional product launches through 2027.
Analysis
This is not a measurable near-term earnings input for AAPL, but it modestly validates a potentially higher accessory attach rate around a new form factor. The more relevant read-through is that foldable-phone ergonomics create a specialized accessory market where standard rectangular power banks fit poorly; that could support premium pricing and incremental MagSafe ecosystem revenue, but third-party brands—not Apple—will likely capture most of that wallet share.
PETL's reported growth and profitability are unaudited marketing claims from a subscale, direct-only vendor, so they should not be extrapolated into iPhone unit demand. Its disclosed shipment run-rate is immaterial against Apple's installed base, while an $89.95 accessory price points to a narrow design-conscious cohort rather than mass-market demand. The larger competitive implication is for incumbent mobile-accessory vendors such as Anker Innovation (300866 CH), Belkin/Foxconn (2354 TW), and ZAGG/Vertiv-linked accessory channels: foldable-specific designs could fragment a historically commoditized category and raise product-development and inventory-risk requirements.
Over 6-18 months, the key investable question is whether Apple’s foldable architecture sustains enough volume to alter accessory attach rates or merely shifts purchases from existing MagSafe packs. AAPL upside would require independently observable evidence of elevated foldable mix, Services/Accessory revenue acceleration, or supply-chain order increases; a proliferation of niche DTC accessories alone is not a catalyst. Conversely, rapid adoption of integrated higher-density batteries or faster wired charging would cap the external-pack category despite favorable form-factor fit.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No standalone AAPL trade: treat this as a low-impact ecosystem datapoint rather than an iPhone demand signal. Reassess only if Apple reports an acceleration in Wearables/Home/Accessories revenue or supply-chain checks indicate foldable volumes above initial expectations over the next 1-2 quarters.
- For AAPL holders, monitor third-party accessory pricing and return rates through the holiday season; sustained premium sell-through would support accessory attach-rate assumptions, while discounting below $70 would indicate the category remains commoditized and offers no incremental margin thesis.
- Watch Anker Innovation (300866 CH) and Foxconn/Belkin exposure (2354 TW) for foldable-specific accessory launches in the next 3-6 months. A broad incumbent response would validate the segment but likely compress PETL-like niche pricing rather than create a material AAPL revenue uplift.
- Do not underwrite PETL's stated revenue growth into public-equity estimates without independent traffic, paid-acquisition, repeat-purchase, and gross-margin data; a DTC launch can show high early growth while customer-acquisition costs and warranty returns impair durable profitability.
More News
- Fed chairman talks tough on inflation — plus, what's behind Micron's big rally
- Investors Eye AI Payoff in Microsoft, Alphabet Earnings
- Apple brings touch to the Mac, reversing years-old stance on touchscreen laptop
- The 2,000-Nit OLED in Apple’s New MacBook Is a Big Deal
- Apple’s touchscreen MacBook Pro pushes laptop pricing to a new extreme
- The Inside Story of Why Apple Finally Brought a Touch Display to the Mac