
BUILD-A-BEAR DEBUTS EXCLUSIVE LLOROMANNIC PLUSH AS PART OF NEW SANRIO HALLOWEEN COLLECTION FOR THE FIRST TIME EVER IN SELECT COUNTRIES
Source: PR Newswire
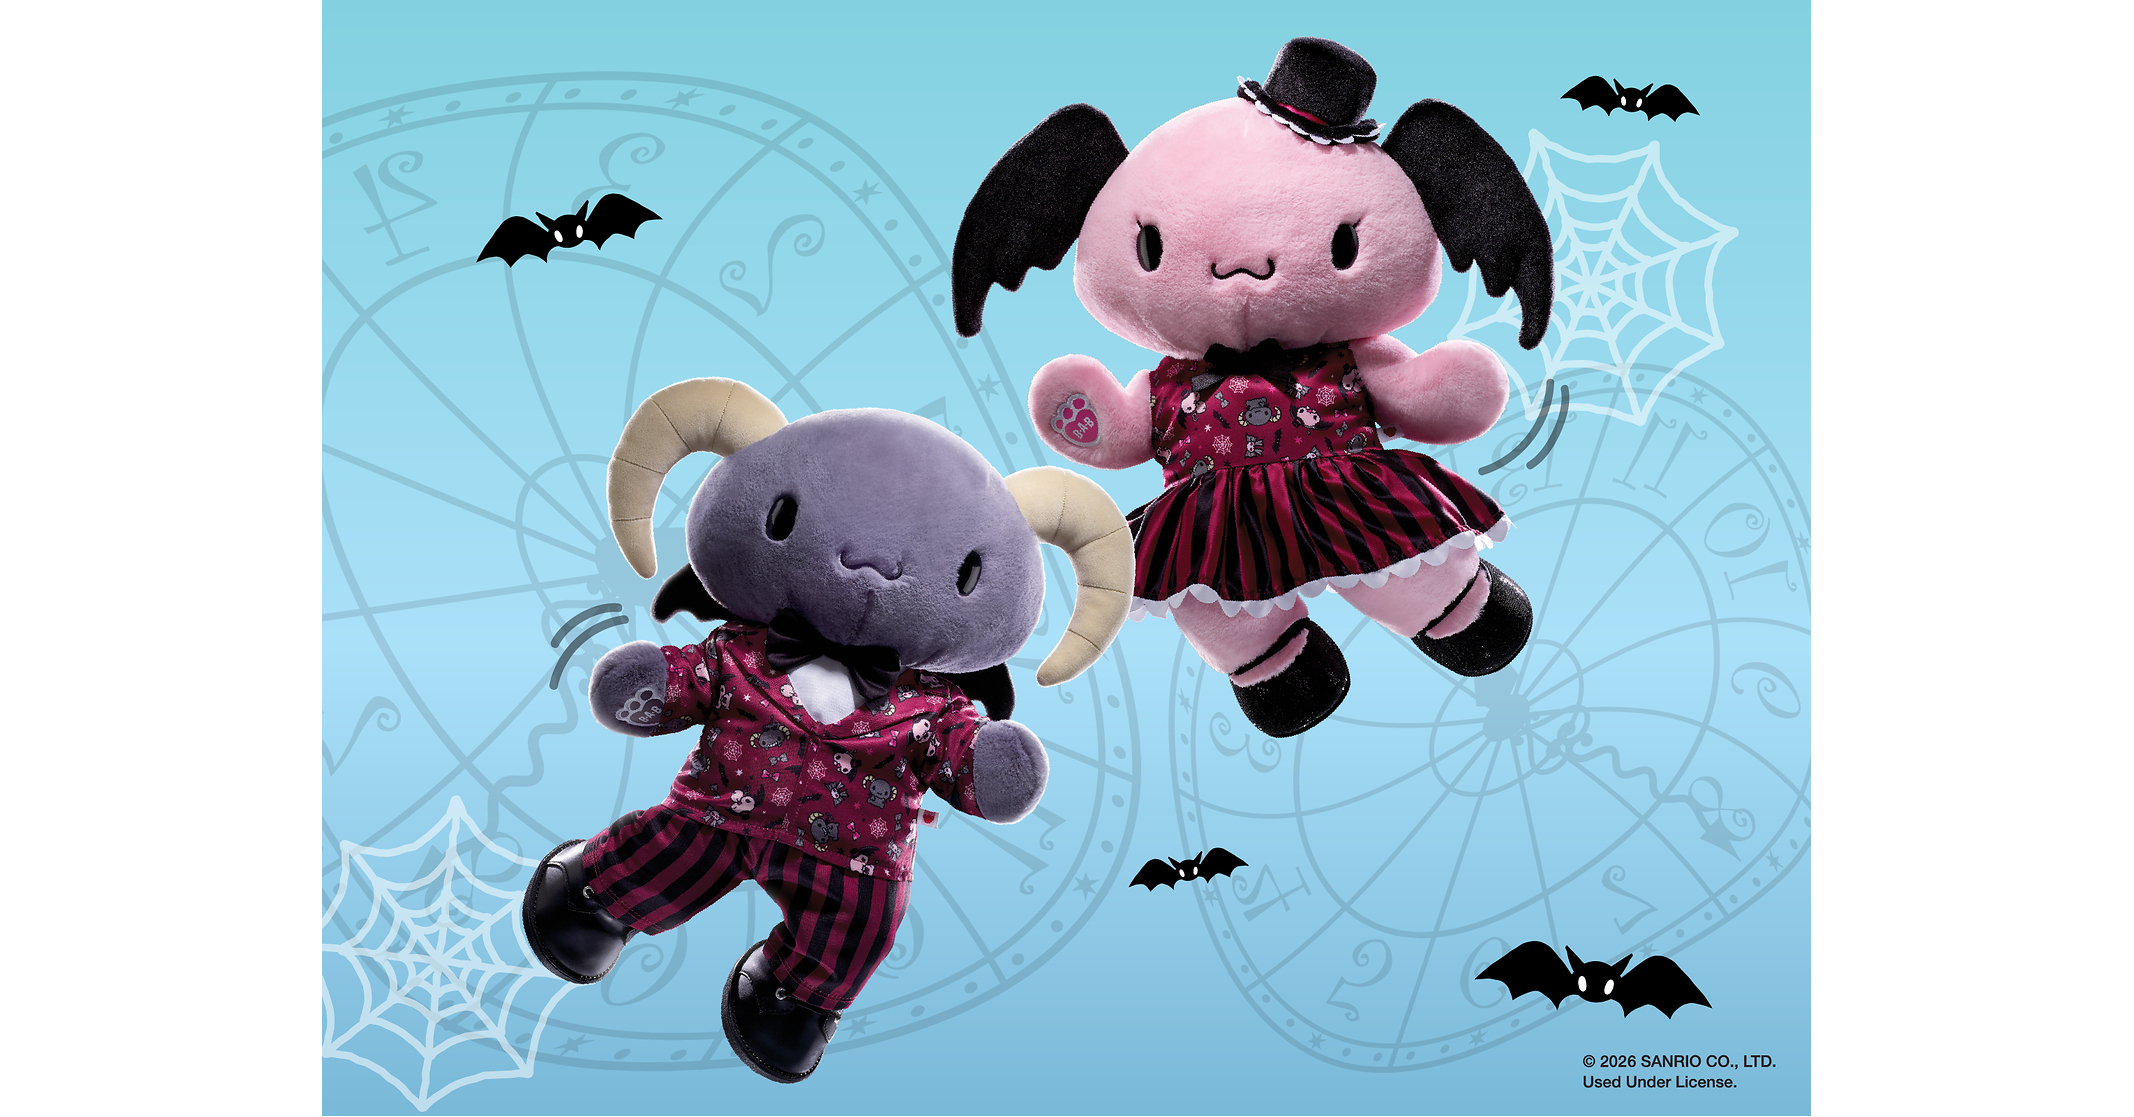
Build-A-Bear (NYSE: BBW) launched its Sanrio Halloween Collection featuring full-size plush debuts of Lloromannic characters Berry and Cherry, plus seasonal versions of Cinnamoroll and Hello Kitty. The products are available exclusively at Build-A-Bear locations and online while supplies last, and the company positions the rollout as a first-to-market licensed offering in the US/UK/Ireland/Canada. Impact is likely limited to promotional/engagement benefits rather than a near-term earnings catalyst, with broader support from BBW’s strong recent revenue base ($529.8M FY2025, fifth consecutive record year).
Analysis
This is less about one plush drop and more about whether BBW can keep proving it has a real licensing flywheel. The economic value is in traffic and attachment rate, not the character itself: limited-edition IP should lift average ticket through add-on outfits/accessories with relatively little incremental SG&A, which is more important than the top-line contribution of the base item. If the launch resonates, the margin mix can improve faster than revenue because the collectible audience tends to buy bundled add-ons at launch.
The best read-through is to Sanrio/OTC holder exposure and, secondarily, to other IP licensors whose catalogs can be monetized through scarcity. SNROF gets a high-margin royalty stream with almost no capital intensity, while BBW’s competitor set is really mass merchants and toy/gift retailers that lack this kind of exclusivity; they lose the occasion spend without a clean substitute. The second-order risk for BBW is that these collaborations train customers to wait for drops, which can make demand bursty and increase inventory markdown risk if social-media demand does not convert quickly.
Catalyst timing matters: the next 2-6 weeks are mostly sentiment and web traffic, but the real test is Halloween sell-through and holiday repeatability into the next earnings print. If same-store sales or gross margin guidance do not inflect, this becomes a marketing win rather than a valuation driver. Structurally, repeated licensed exclusives can justify a higher multiple for BBW only if they prove durable across seasons, not just one collectible cycle.
Contrarian view: the market may be overrating how much of this is incremental versus pre-allocated fan spend. If this merely pulls forward Sanrio collector demand from other channels, BBW gets excitement without much earnings delta. Falsifiers are weak sell-through by mid-October, flat accessory attach, or any commentary that inventory was built conservatively and margins failed to expand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Long BBW into the Halloween-to-holiday sell-through window, but keep it tactical: target a 4-8 week holding period and only add if web traffic and social engagement translate into visibly better comp guidance; invalidate if management does not raise gross margin expectations on the next update.
- Pair trade: long BBW / short XRT or a weak specialty retail basket for 1-3 months, on the thesis that licensed exclusives can support traffic and mix better than undifferentiated discretionary retailers; cover if BBW fails to hold relative strength after Halloween.
- Buy SNROF on any post-announcement pullback as a low-beta royalty beneficiary; the risk/reward is skewed because the upside comes from incremental licensing dollars with minimal operational risk, while the downside is mostly that the collaboration is too small to move estimates.
- Avoid chasing BRY/other non-economic read-throughs: there is no clear second-order beneficiary outside BBW/Sanrio, so treat this as a stock-specific merchandising event unless later data show a broader Sanrio demand reacceleration.
- Set an alert for BBW around the next earnings release: if inventory rises faster than sales or accessory attach does not improve, the trade thesis is likely overdone and the stock should be faded rather than owned.
More News
- Take Five: Bangkok blues
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- TSMC expected to report sixth straight quarter of record profit thanks to AI boom
- Vår Energi cuts 2026 output forecast; Q3 production at 369,000 boepd