
HEXCLAD RAISES THE BAR WITH NEW HIGH-PERFORMANCE BAKEWARE
Source: PR Newswire
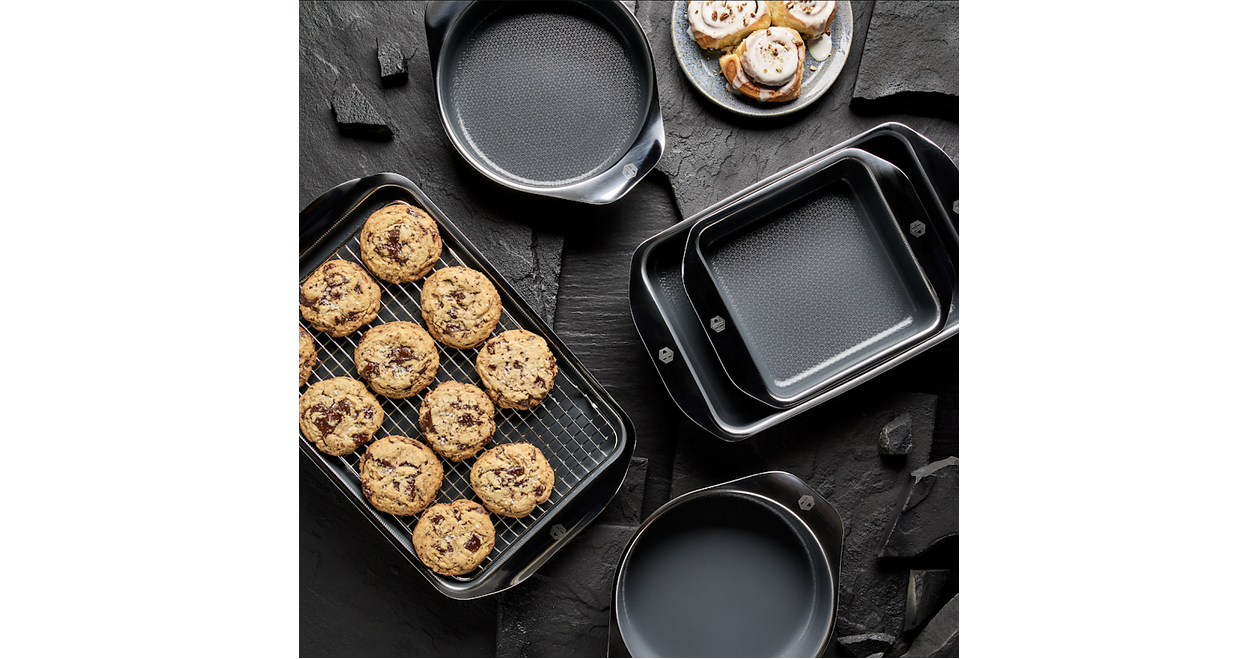
HexClad launched a six-piece Hybrid Bakeware collection after four years of development, extending its hybrid cookware platform into bakeware. The PFAS-free TerraBond ceramic nonstick products are rated for oven temperatures up to 900°F and are priced from $179 to $499, with presales beginning immediately and shipments expected by October 5. The launch broadens HexClad's premium kitchenware offering beyond stovetop products, though no revenue, sales-volume, or profitability impact was disclosed.
Analysis
This is not independently investable news because HexClad is private, and the launch alone is unlikely to alter near-term earnings for listed kitchenware or retail peers. The relevant read-through is whether a premium, PFAS-free positioning can sustain unusually high bakeware price points through the holiday selling season; successful sell-through would validate further premiumization in cookware, while weak conversion would signal that the brand's customer acquisition engine does not transfer efficiently beyond its core category.
WSM has the clearest public exposure as a premium kitchen retail proxy: incremental traffic and attach-rate from a new aspirational brand could benefit its retail ecosystem if carried broadly, but proprietary/private-label bakeware economics are likely superior to third-party brand sales. NWL faces a modest competitive narrative risk through Calphalon if consumers increasingly equate ceramic/PFAS-free claims with a quality upgrade, though HexClad's premium price tier limits direct volume substitution. The key 1-3 month catalyst is verifiable shipment timing, retailer distribution, review quality, and holiday discounting; aggressive promotions would undermine the implied durability and pricing-power thesis. Over 6-18 months, a credible nonstick durability advantage could pressure conventional coated-bakeware margins, but the product claims require third-party validation and meaningful repeat-purchase data.
Contrarian view: premium bakeware is a low-frequency purchase, so strong pre-sales may reflect brand-loyalty demand rather than a scalable new profit pool. At these price points, the principal risk is not competing commodity bakeware but consumer comparison with premium stainless, carbon-steel, and ceramic alternatives that may offer lower perceived replacement risk. There is no basis to infer material public-equity earnings revisions until distribution breadth, unit velocity, and gross-margin contribution are disclosed or observable.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone trade recommended. Treat this as a holiday-demand watch item rather than a catalyst for public kitchenware equities.
- Monitor WSM holiday commentary and channel checks over the next 1-3 months for premium bakeware demand and third-party brand sell-through; consider a tactical long only if premium-category comp trends accelerate without incremental promotional intensity.
- Maintain a watch alert on NWL/Calphalon for evidence that PFAS-free ceramic products gain shelf space or pricing traction. A sustained share loss or reduced cookware guidance would be required before considering a relative short versus WSM.
- For any premium-consumer discretionary long, use post-holiday gross-margin performance as the falsification test: elevated markdowns, returns, or weaker-than-expected kitchen-category demand would indicate that headline pre-sale interest did not convert into durable pricing power.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Fed hikes again - an AI-Picked insurer is still cashing in
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- US official says upcoming spectrum auctions could generate more than $100 billion
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- What to know about US Federal Reserve’s first interest rate hike in 3 years