
METLEN und PETRONAS schließen LNG-Liefervertrag zur Stärkung der Energiesicherheit und Diversifizierung in Südosteuropa
Source: PR Newswire
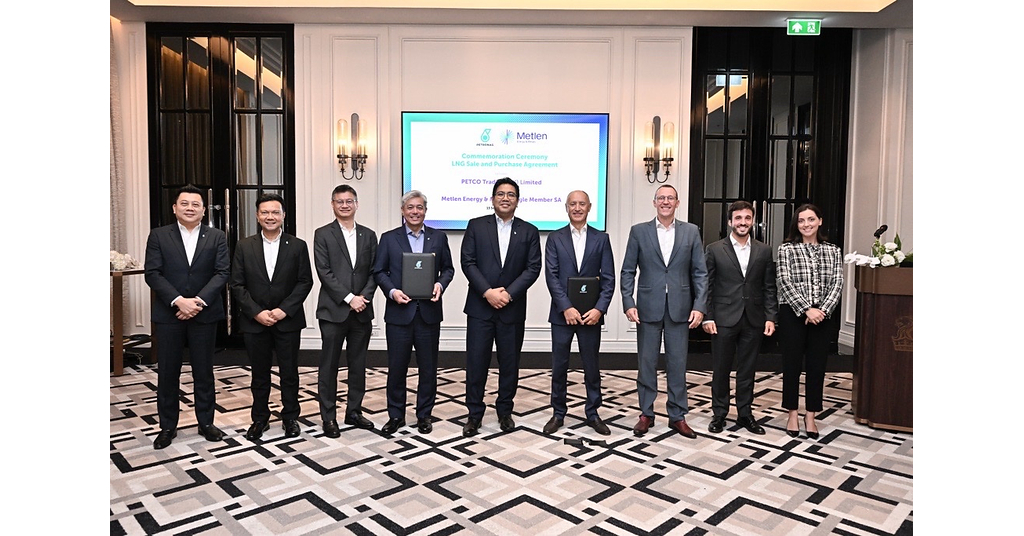
METLEN and PETRONAS signed a five-year LNG supply agreement under which PETCO Trading will deliver six Atlantic-portfolio cargoes annually to Greece from 2027, equivalent to about 0.6 bcm per year. The deal diversifies METLEN's gas procurement, improves supply flexibility and resilience, and supports Greece's role as a Southeast European energy hub. For PETRONAS, the agreement expands LNG market presence west of Suez, particularly in Europe and the Mediterranean.
Analysis
The economic value to MTLN is not the contracted volume itself but optionality: incremental dependable supply can support its gas-to-power, trading and regional resale franchise when southeast-European hub prices dislocate from northwest Europe. If the contract is indexed to TTF or JKM with destination flexibility, MTLN gains a modest but recurring trading-margin hedge; if it is oil-linked or rigidly take-or-pay, it instead adds basis and demand risk. The key missing terms—pricing slope, diversion rights, terminal access and annual delivery profile—determine whether this is EBITDA-accretive or principally a security-of-supply cost.
Near term, the announcement should not alter earnings estimates materially and is unlikely to justify a standalone re-rating. Over 1-3 months, the relevant catalyst is evidence that MTLN has secured regasification, transmission and downstream offtake capacity sufficient to monetize regional spreads; this would also marginally pressure incumbent Balkan gas suppliers and traders reliant on constrained pipeline routes. Over 6-18 months, a deeper Atlantic LNG supply chain raises MTLN's strategic value only if Greek and Balkan power demand remains gas-intensive and cross-border interconnector utilization expands.
The contrarian risk is that new global LNG supply expected from 2027 compresses European spot volatility and trading margins precisely as these cargoes begin, reducing the value of portfolio diversification. A weak regional industrial-demand backdrop or faster renewable/storage deployment could leave MTLN carrying contracted volumes into a soft market. This thesis is falsified positively by disclosed flexible pricing plus higher energy-trading EBITDA; negatively by increased working-capital needs, take-or-pay disclosures, or a material rise in net leverage without corresponding contracted downstream sales.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in MTLN on the release alone; treat as a watch item until contract pricing, destination flexibility and downstream offtake are disclosed. Reassess following the next results call if management quantifies trading-margin or working-capital effects.
- For existing MTLN longs, retain exposure only if energy-trading EBITDA and cash conversion improve over the next 2-4 reporting periods; reduce if net leverage rises while gas volumes are not matched by contracted customer sales.
- Monitor the TTF-JKM spread and southeast-European gas basis through 2027: sustained regional premiums would support MTLN's optionality, while a compressed spread and declining hub volatility argue against assigning incremental multiple value to the agreement.
- Do not infer an investable read-through to MSCI or LSEG; their appearance is ESG/index-data related rather than a revenue, earnings, or capital-markets catalyst.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off