
Jonathan Cahn Lands 11th Consecutive New York Times Bestseller With The Altar of Pergamon
Source: PR Newswire
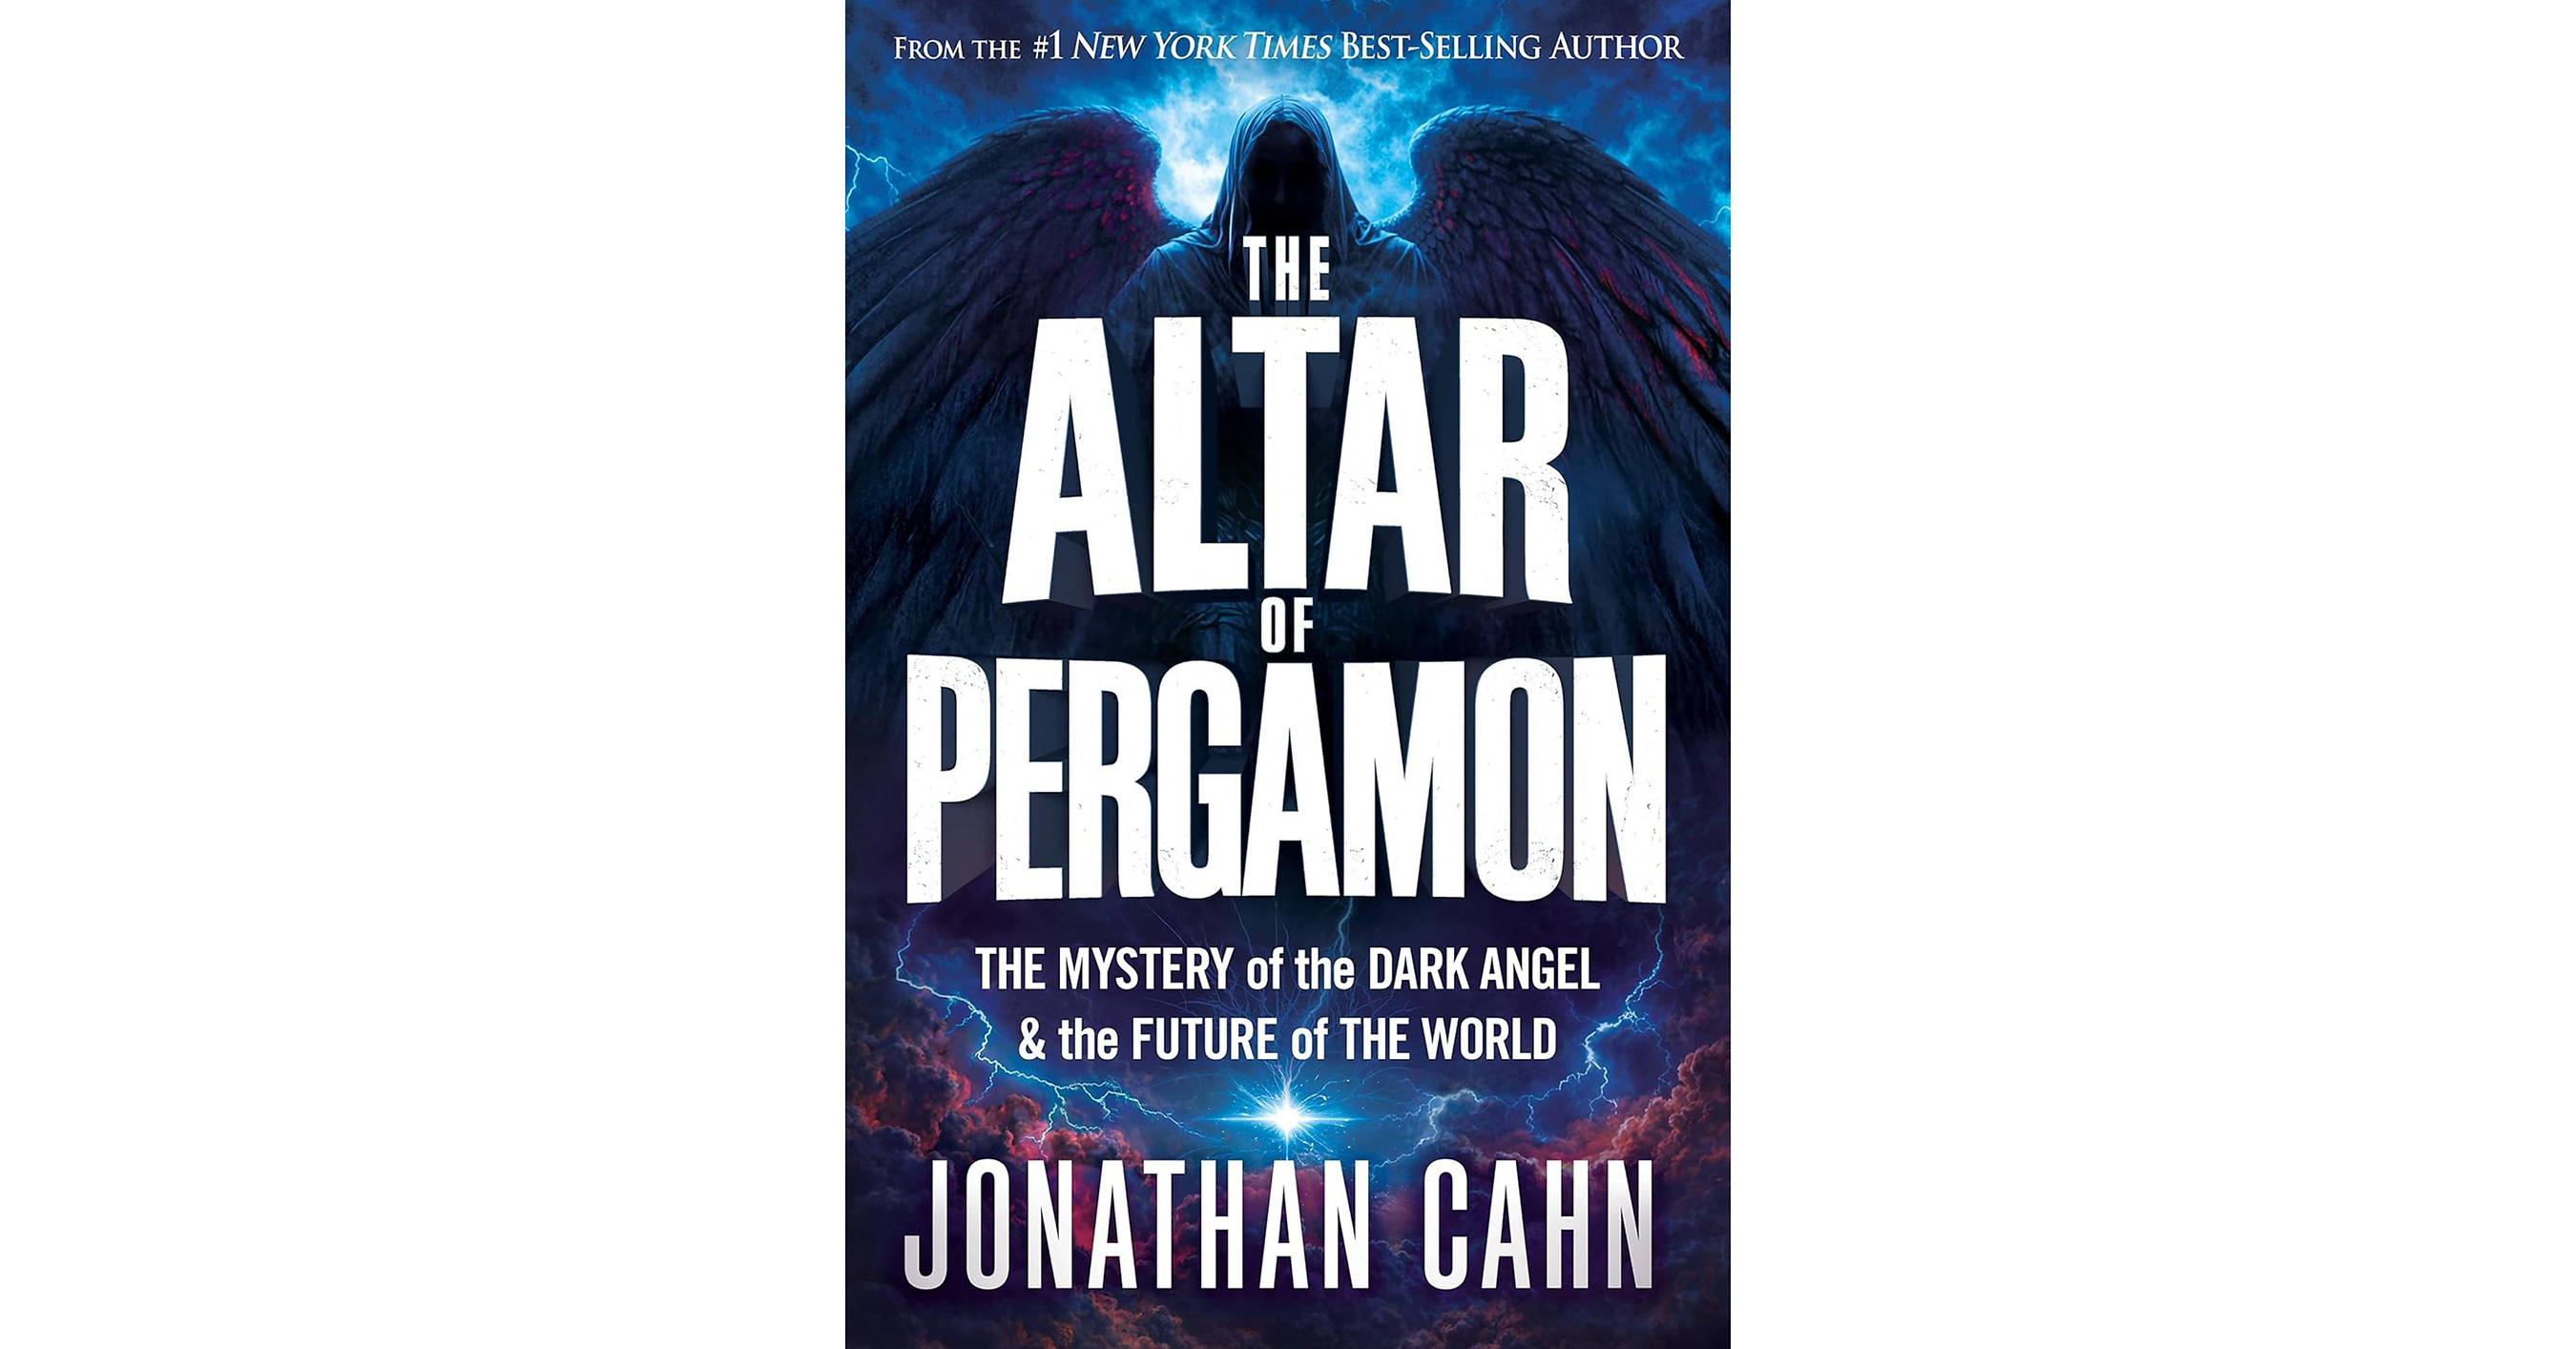
Jonathan Cahn's The Altar of Pergamon debuted at No. 11 on The New York Times Hardcover Fiction bestseller list following its September 1 release, extending his streak to 11 consecutive NYT bestsellers. The book's publisher highlighted Cahn's decade-long commercial track record, including The Harbinger's 102-week run on the list. The announcement is promotional publishing news and is unlikely to have material public-market implications.
Analysis
There is no investable read-through for AAL from a single, highly publicized onboard incident: any liability, diversion, and disruption costs are immaterial against the carrier's network economics. The only near-term relevance is reputational amplification if follow-on media coverage creates a broader narrative around cabin-security failures; absent evidence of repeated events or a regulatory response, this should not alter revenue or valuation assumptions.
For NYT, a placement on its bestseller list is not a meaningful earnings catalyst. The list can marginally reinforce the franchise's cultural relevance and licensing value, but book-list economics are too small to affect subscription, advertising, or EBITDA estimates. The underlying release is issuer-promotional and provides no independently verifiable unit-sales, sell-through, or royalty data.
The more relevant second-order angle is that faith-oriented publishing remains a fragmented, privately held niche rather than a clean public-equity theme. A sustained breakout would be more likely to benefit large trade publishers and retailers through aggregate category demand, but this item alone does not establish incremental consumption versus a shift among religious-title buyers. ORCL has no identifiable fundamental linkage.
Consensus should treat the newsflow as non-actionable rather than extrapolate an isolated bestseller ranking into a media-demand signal. Reassess only if disclosed sales velocity translates into broader category data from Circana/NPD, or if AAL faces an FAA/DOT investigation or demonstrable booking deterioration tied to safety perception over the next 1-3 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No standalone position in AAL, NYT, or ORCL based on this release; expected fundamental impact is below materiality thresholds.
- Maintain AAL as a watch item only: investigate if FAA/DOT action, a repeat cluster of comparable incidents, or measurable deterioration in PRASM/forward bookings emerges within 30-90 days. A regulatory escalation—not the event itself—would be the catalyst for downside estimate risk.
- Do not chase NYT on bestseller-list visibility. Consider a media-sector thesis only if future disclosures show broad book-category growth feeding paid-subscription conversion or higher-margin licensing; the required evidence is absent here.
More News
- Bloom Energy: Not Pricing In Capacity Upside
- Is Berkshire Bending the Rules With Bending Spoons?
- As AI Labs Burn Cash, the Real Question Is Which Suppliers Get Paid
- 3 Stocks to Buy as the AI Trade Sputters
- Bloom Energy Just Reported—Its Biggest Order Is Still Waiting on a Pipeline
- Instacart reportedly discussed selling itself with DoorDash and Uber
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Document Search Enhancements, AI Enhancements, AI Actions, & Chat Export
- AI Vendor Landscape for Institutional Investment Teams