
SANY Heavy Truck dévoile sa gamme de camions électriques prêts à la production à IAA Transportation 2026
Source: PR Newswire
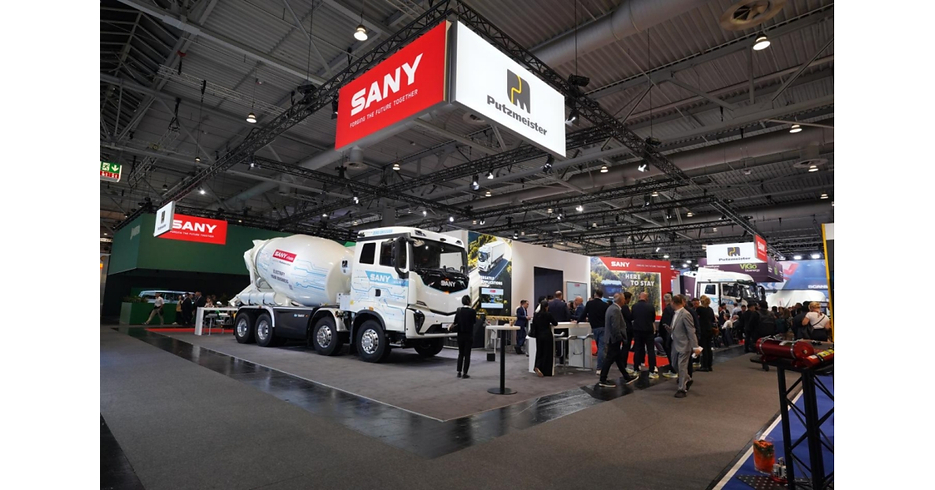
SANY Heavy Truck launched its production-ready SE636 battery-electric truck range for Europe at IAA Transportation 2026, led by a 636 kWh, 4x2 heavy-duty model with up to 500 km stated range and a 10.9-tonne curb weight. The SE636 has EU vehicle type approval and is already operating in Germany, Turkey and other European markets; SANY says it is the first mass-produced Chinese battery-electric heavy truck to obtain this certification. SANY reports more than 70,000 electric trucks globally, over 20 million cumulative operating kilometers in Europe since 2022, and a European service network of roughly 650 workshops.
Analysis
The investable implication is competitive rather than a direct SANY earnings catalyst: credible Chinese BEV-truck entrants raise the probability that European incumbents must defend fleet accounts through pricing, financing and uptime guarantees. That pressure is most acute for Daimler Truck (DTG.DE) and TRATON (8TRA.DE), whose premium valuation depends partly on software, service and residual-value economics rather than initial vehicle margin. Volvo (VOLV-B.ST) and PACCAR (PCAR) are relatively better insulated by entrenched dealer networks, captive finance and customer relationships, but none is immune if Chinese entrants demonstrate comparable availability and lower total cost of ownership.
The key second-order issue is residual value. A deep independent repair footprint reduces the perceived downtime risk that has historically protected incumbent truck pricing; if fleet managers become willing to underwrite a new Chinese badge, lease rates and used-truck assumptions could reset before reported unit-share losses become visible. This is a 6-18 month risk, while the next 1-3 month catalyst is whether European fleet trials translate into disclosed orders, financing partnerships, and operating-cost data under real payload and winter conditions. Company-reported range and installed-fleet figures are not sufficient evidence of profitable European scale; warranty reserves, parts fill rates and utilization data matter more.
Consensus may overstate the near-term disruption: heavy-duty fleet purchasing is conservative, and homologation plus service coverage do not solve financing, driver acceptance, residual-value guarantees or cross-border parts logistics. A broad short on European truck OEMs is premature absent evidence of material tender wins or price concessions. The more likely early impact is incremental selling expense and lower-margin fleet deals, not an immediate volume cliff.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No standalone directional trade on this announcement; set an alert for independently verified European fleet orders above 500 units or a disclosed captive-finance/residual-value program. Either would make a 6-12 month margin-pressure thesis on DTG.DE and 8TRA.DE more actionable.
- Monitor the DTG.DE / VOLV-B.ST relative performance over the next 1-3 months; consider a modest short DTG.DE versus long VOLV-B.ST only if DTG.DE underperforms by less than 5% despite evidence of European electric-truck tender activity. Thesis: Daimler's premium service and financing economics face greater downside from price-led entry; stop if Daimler raises 2027 service-profit or free-cash-flow guidance.
- For a sector hedge, favor long PCAR versus short 8TRA.DE on a 6-18 month horizon if Chinese suppliers gain EU fleet traction. PACCAR's North American exposure and dealer-finance ecosystem offer relative insulation, while TRATON has greater exposure to price-sensitive European fleet tenders; exit if TRATON demonstrates stable order margins and no increase in sales incentives through two reporting periods.
- Watch European battery-electric heavy-truck lease-rate quotes, resale assumptions and OEM warranty provisions rather than registration data alone. A 5-10% decline in quoted lease rates or a rise in warranty/service provisions would signal competitive pressure is migrating into reported margins.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- US official says upcoming spectrum auctions could generate more than $100 billion
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- Investors react to Fed hike and market sell-off: Brace for 'higher for longer' rates
- Oil Extends Slump as Saudi Arabia Moves to Restore Key Pipeline
- AI Buildout Hits Inflation as Fed Hikes Rates