
CHAIRMAN AND CEO DAVID ELLISON ANNOUNCES YNON KREIZ CO-CEO OF THE ANTICIPATED COMBINED PARAMOUNT AND WARNER BROS. DISCOVERY AT CLOSING TO HELP BUILD THE NEXT-GENERATION GLOBAL MEDIA COMPANY
Source: PR Newswire
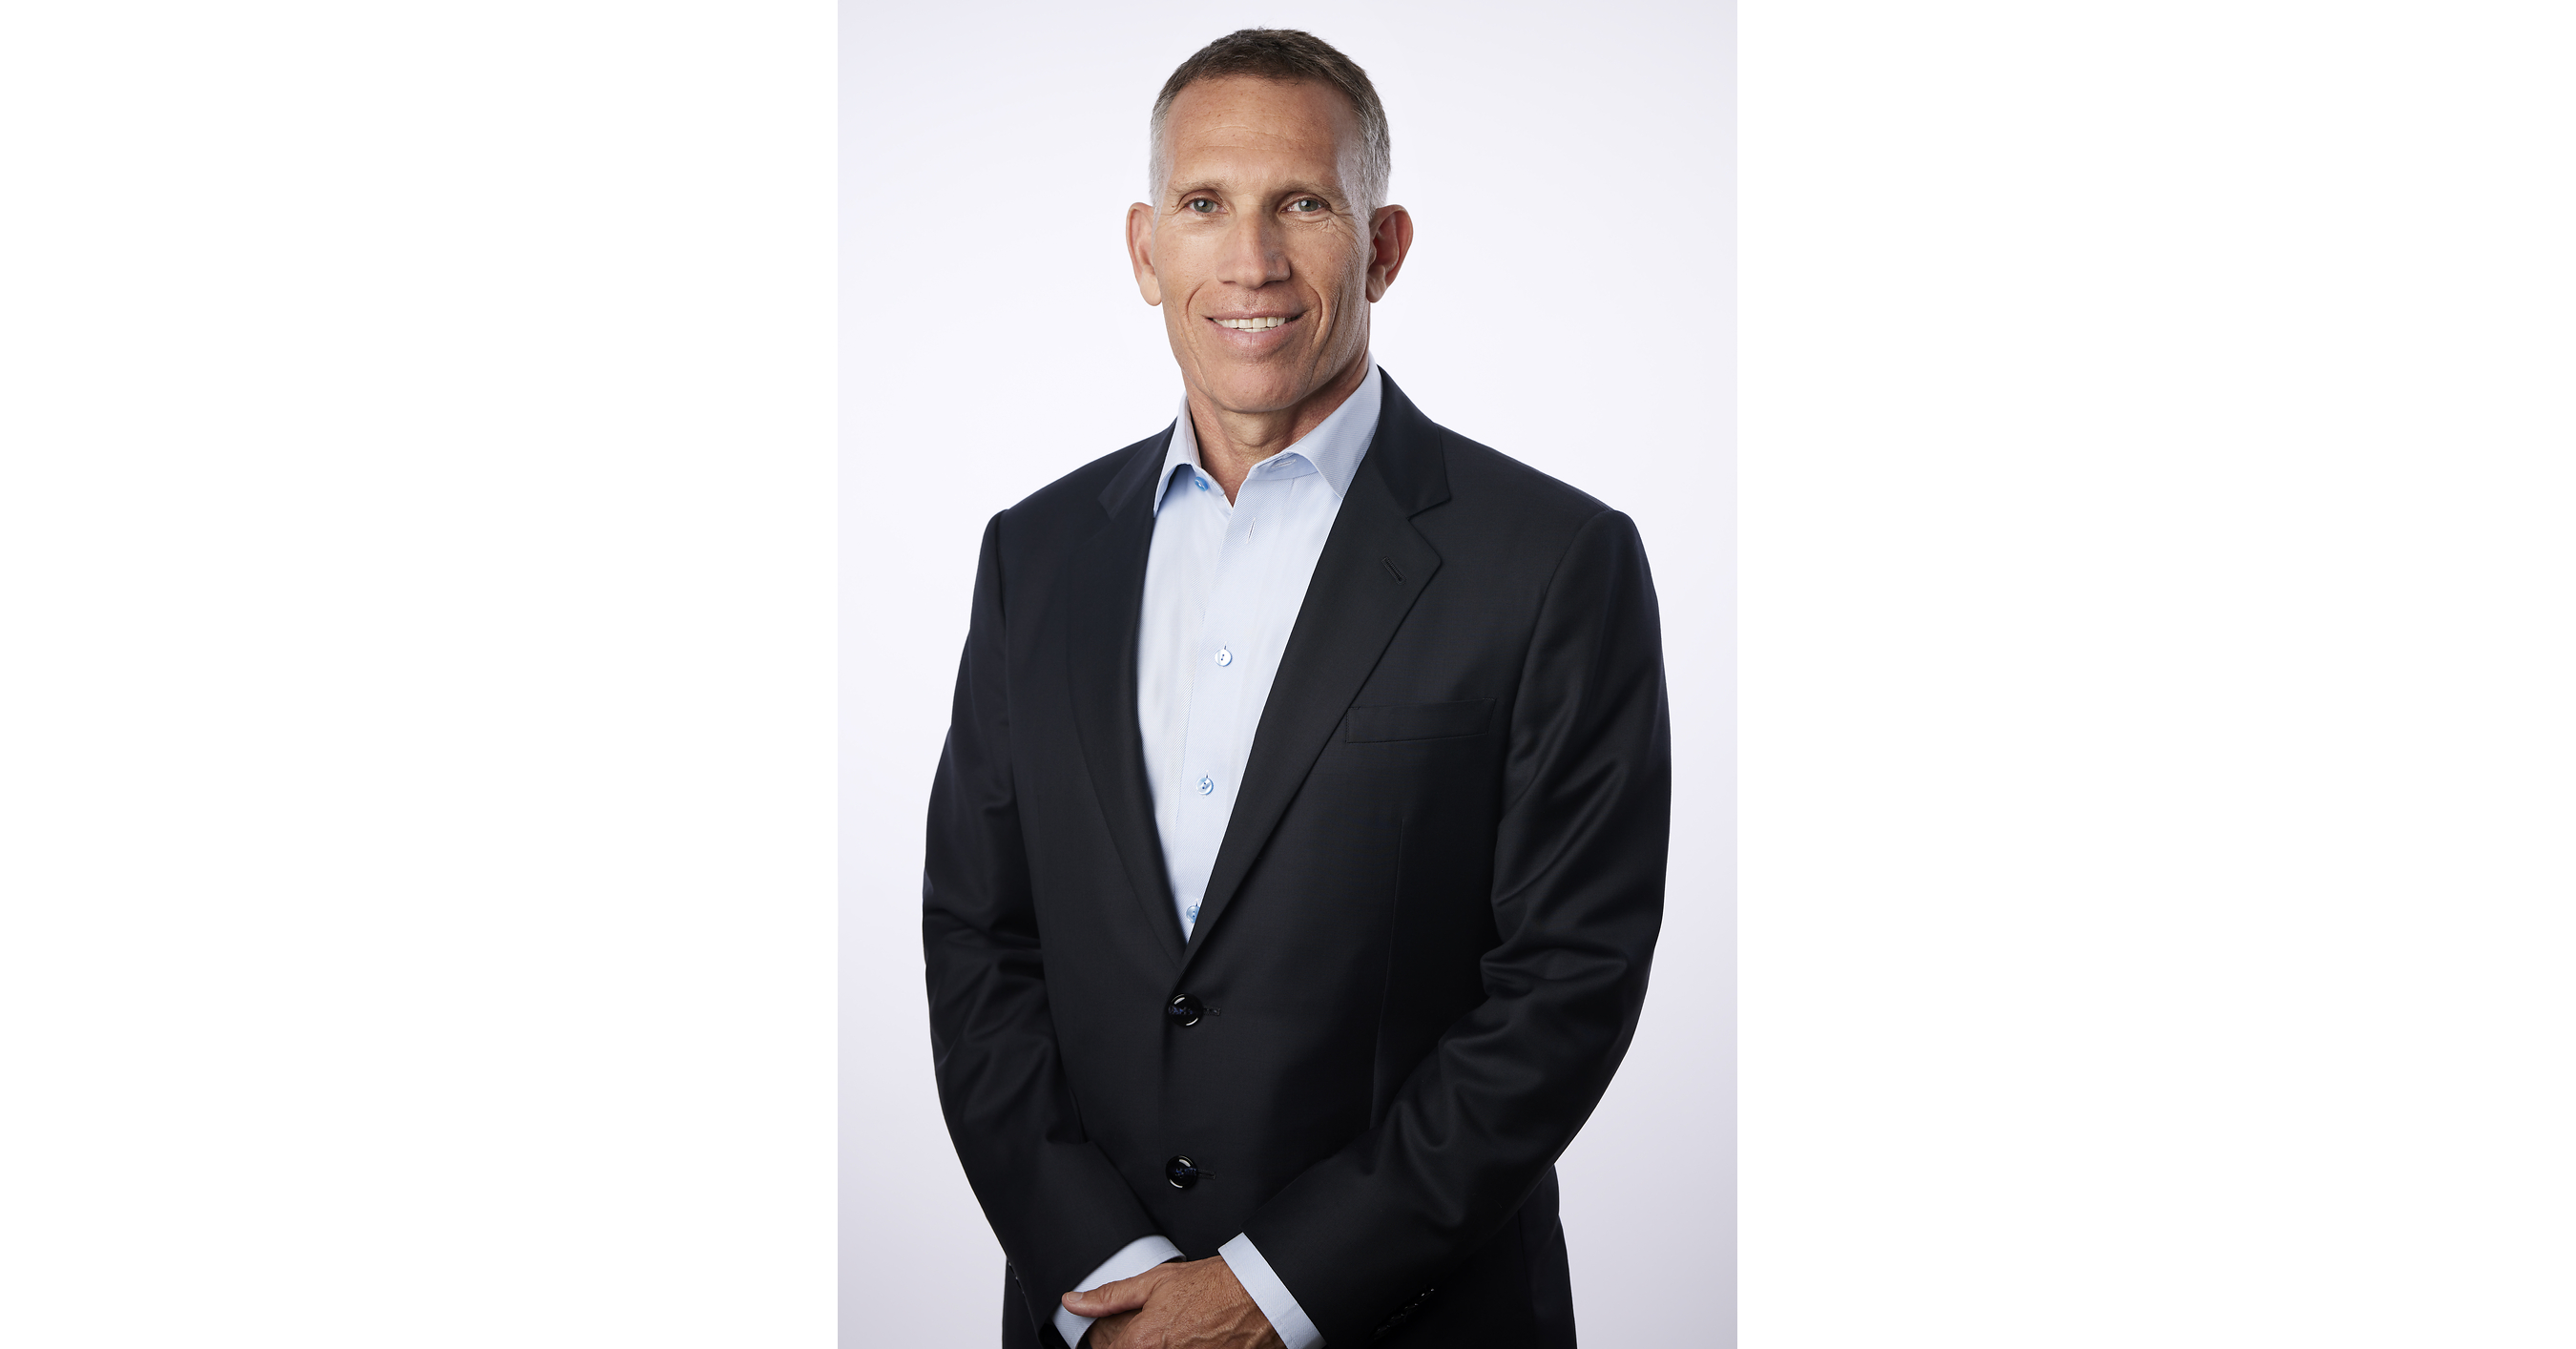
Paramount Skydance named Mattel CEO Ynon Kreiz as Co-CEO of the planned combined Paramount-Warner Bros. Discovery company, effective upon merger closing, with David Ellison retaining the Chairman and CEO roles. Kreiz will run day-to-day operations and integration, while Ellison leads strategy, creative direction, technology and capital allocation. Management projects 2026 revenue and pre-stock-based-compensation EBITDA growth of 16%-19%, more than $6 billion of run-rate merger synergies, and a streaming platform exceeding 200 million global subscribers, subject to closing and integration risks.
Analysis
The appointment marginally improves integration credibility rather than merger economics. Kreiz's relevant edge is monetizing IP across film, consumer products, games and experiences; if deployed effectively, the combined company could raise franchise lifetime value and reduce dependence on linear advertising. The near-term valuation driver, however, remains closing certainty and the financing/regulatory path—not a management announcement—so PSKY/WBD upside should be limited until a detailed synergy bridge, timing, and integration-cost budget are disclosed.
The key second-order negative is MAT. Its strategic premium has rested on converting toy brands into recurring entertainment and licensing ecosystems; an externally recruited successor could preserve that plan, but a transition creates a 6-12 month execution discount precisely when film, games and consumer-products investment requires coordination. Conversely, DIS faces limited immediate impact: a larger rival may become more disciplined in content spending, which would relieve rather than intensify the industry’s bidding inflation for talent and sports rights.
Consensus is likely to capitalize the stated synergy target too quickly. Media integrations often realize procurement and duplicative-overhead savings first, while the more valuable distribution, streaming, and advertising benefits require difficult product rationalization and risk subscriber churn. Falsification for a constructive PSKY/WBD view is a closing delay, rising net leverage/credit spreads, or first-year integration costs that absorb most of expected annual savings; confirmation is a quantified 12-24 month cost-takeout schedule and stable streaming engagement through any platform consolidation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- Maintain a merger-arbitrage watch rather than add directional PSKY or WBD exposure in the next 30 days. Enter only after reviewing the definitive exchange ratio, regulatory timetable, pro forma net leverage, and a cash-cost-adjusted synergy schedule; these missing inputs determine whether the apparent EBITDA uplift accrues to equity rather than creditors.
- Initiate a 3-6 month tactical long PSKY / short DIS pair only on a post-announcement pullback, sized to a 1:1 beta-adjusted ratio. The thesis is integration-driven multiple expansion versus Disney's more mature earnings profile; exit if deal timing slips or PSKY underperforms DIS by 10% from entry, with upside dependent on closing milestones and quantified savings.
- Reduce or hedge MAT into the leadership transition; prefer a 6-9 month long HAS / short MAT relative position if MAT does not name a credible internal or franchise-experienced successor promptly. Risk is that a strong successor and continued brand-licensing execution eliminate the transition discount; cover on successor announcement plus reaffirmed margin and entertainment-investment guidance.
- Do not chase WMG on this news. Monitor for talent and soundtrack/content-rights partnerships after closing, but require disclosed contract economics before treating any relationship as an earnings catalyst.
More News
- David Ellison names Ynon Kreiz co-CEO of Paramount and Warner Bros. Discovery
- US judge allows Paramount to close Warner Bros acquisition
- Paramount names Ynon Kreiz as co-CEO ahead of WBD merger
- Warner Bros Discovery stock hits 52-week high at $30.93
- Hollywood’s big debt deal hits a wall of higher yields as Paramount finances Warner Bros. buyout
- Mattel's CEO departing after a rough year at toy giant as Barbie sales deteriorate: ‘Change is overdue'