
Hormel Foods, Culinary Institute of America Open Applications for National Culinary Enrichment and Innovation Program
Source: PR Newswire
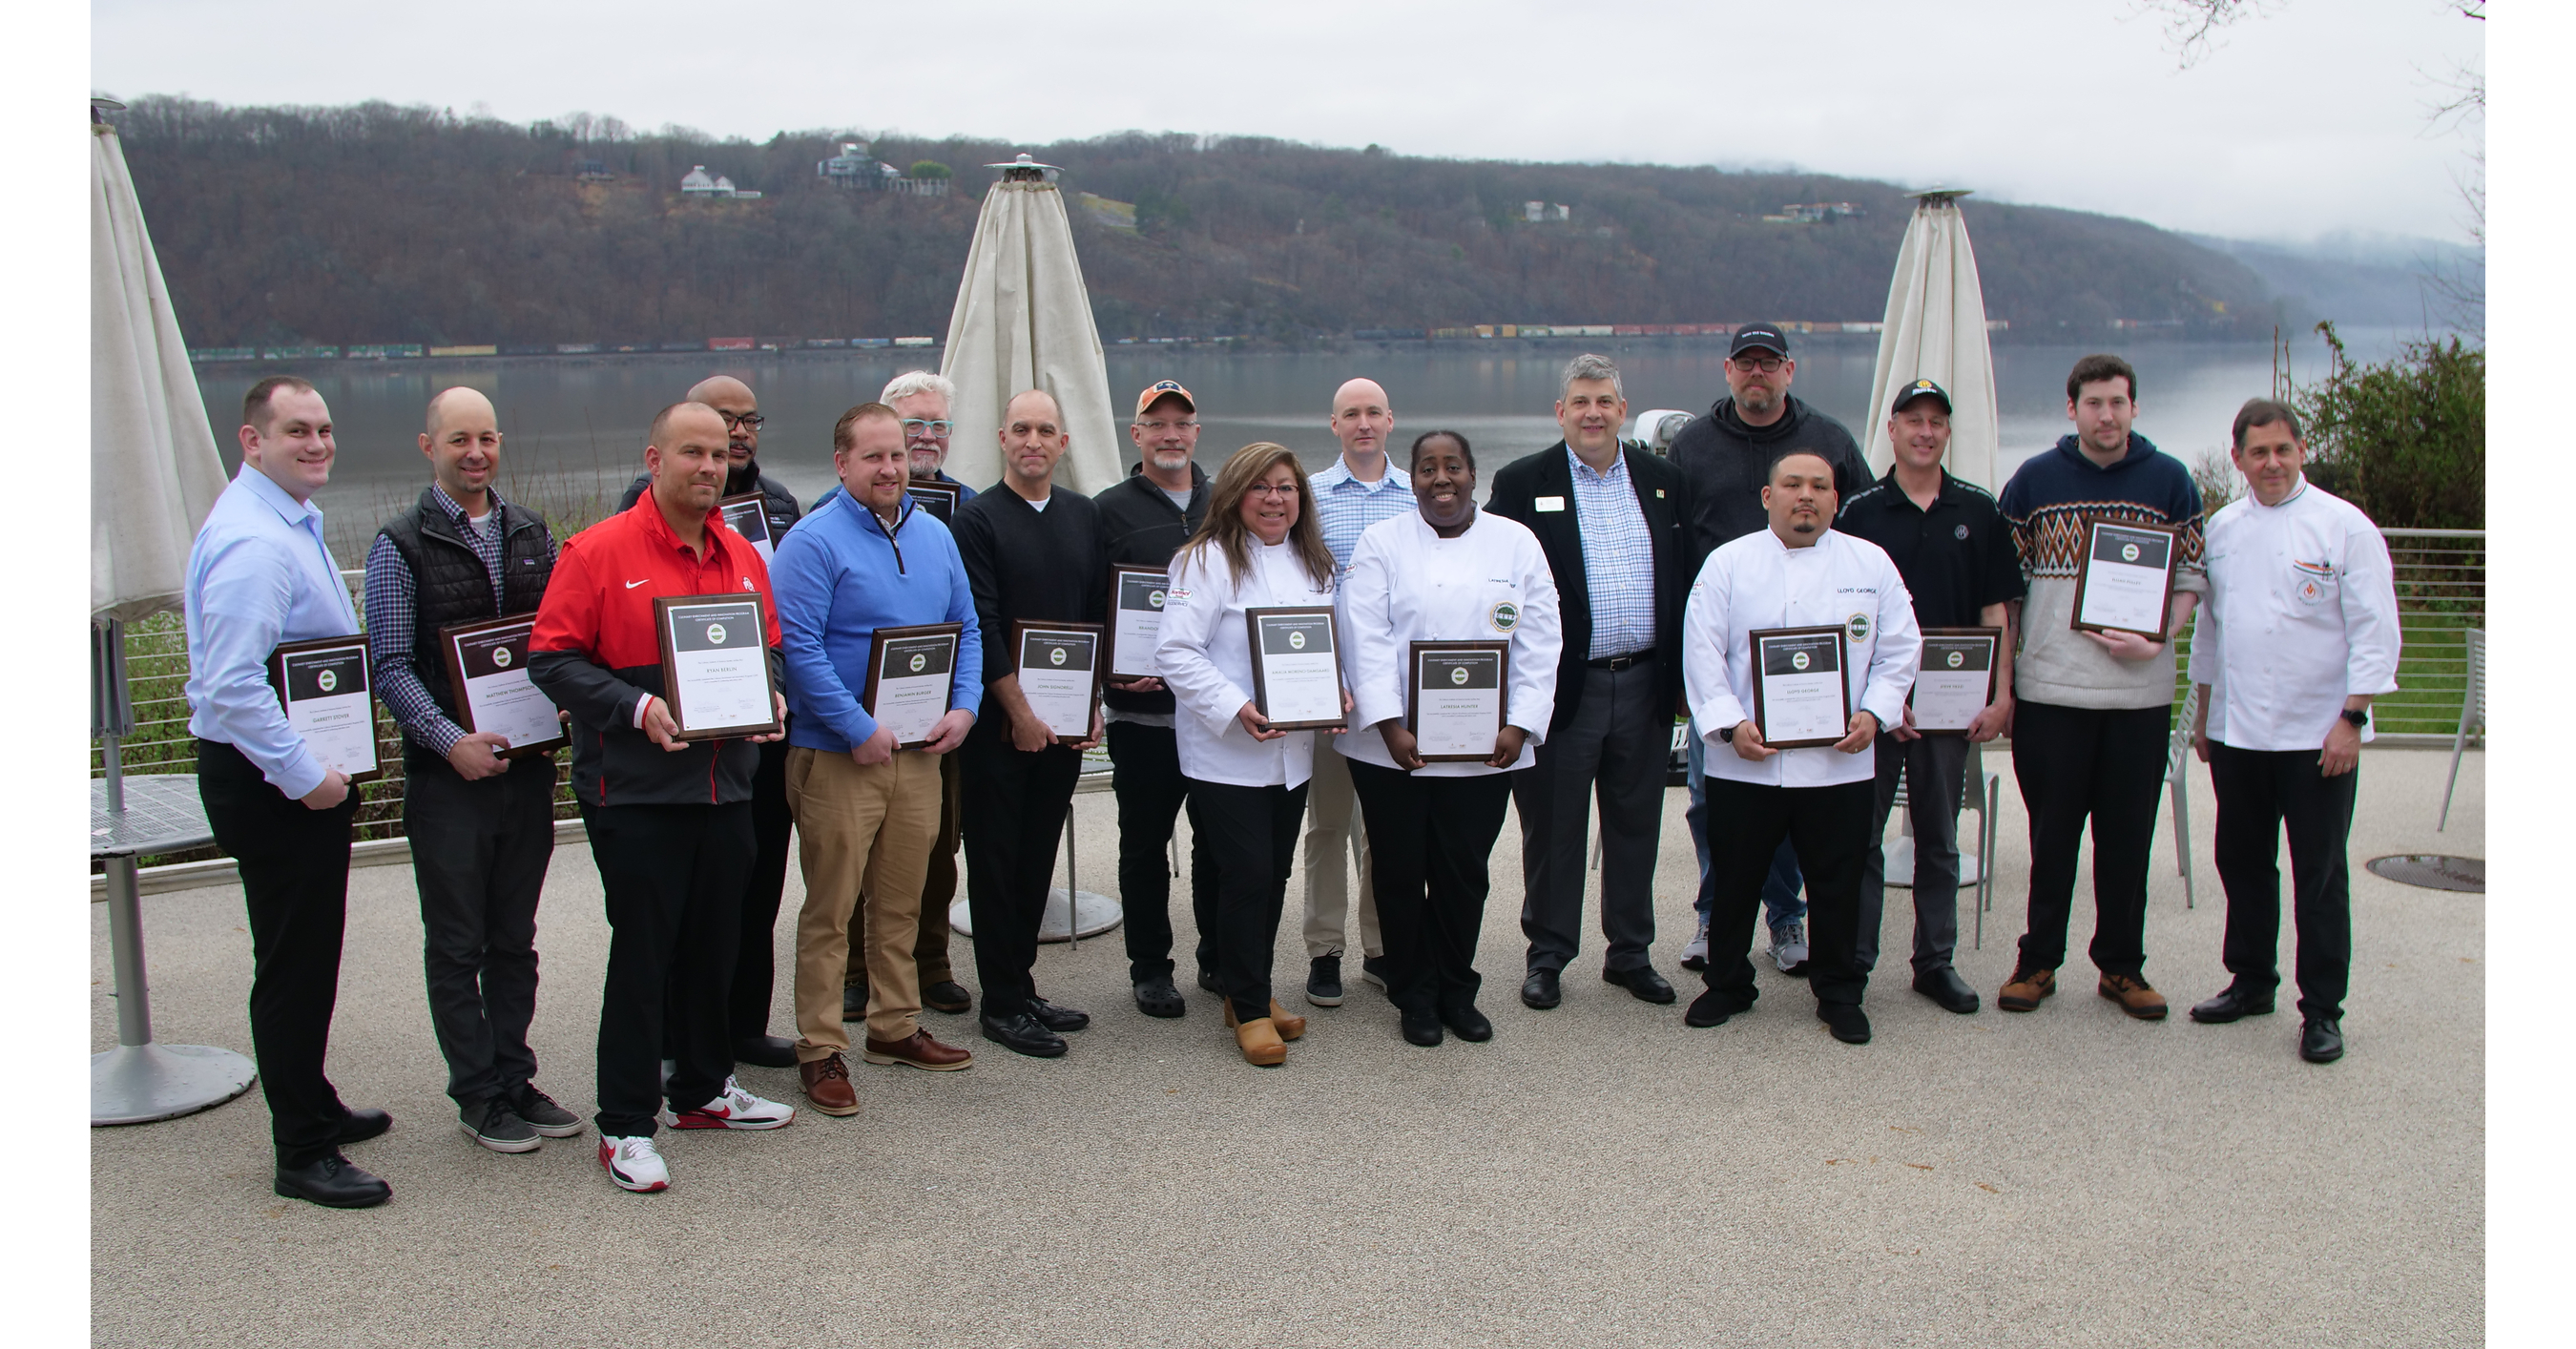
Hormel Foods is accepting applications through Nov. 30, 2026 for its CEIP Class of 2028, a 12-month culinary leadership program for 20 experienced foodservice chefs. Hormel will underwrite tuition and meals for three modules at Culinary Institute of America campuses in Napa Valley, San Antonio, and New York, reinforcing its foodservice-industry workforce and customer-engagement investment. The announcement is primarily a corporate-development initiative and is unlikely to materially affect Hormel's financial outlook.
Analysis
This is a relationship-marketing expense rather than a near-term earnings driver: a 20-person cohort cannot meaningfully alter HRL's foodservice revenue or margin trajectory. Its value is access to influential menu developers and operators, potentially improving trial rates for higher-value prepared proteins and globally flavored products. Any benefit would emerge over 12-36 months through menu placements and repeat purchasing, but it is not independently measurable from disclosed segment data.
The more relevant competitive dynamic is that chef-led specification can create modest switching costs in foodservice once products are embedded in recipes, training, and kitchen workflows. That favors branded, labor-saving suppliers such as HRL versus commodity protein vendors, particularly if restaurant labor pressure persists. However, competitors including Tyson Foods (TSN), Conagra (CAG), and privately held foodservice distributors can replicate chef-engagement programs; the initiative does not establish a durable moat absent evidence of incremental contract wins or foodservice share gains.
Consensus should not treat this as evidence of a demand inflection. The program's long lead time and small scale make it principally a brand-building signal, while HRL's investable debate remains volume elasticity, input-cost recovery, and the pace of normalization in turkey and value-added protein margins. A positive read-through would require subsequent management disclosure showing foodservice growth materially above the broader segment or improved mix-driven gross margin; without that, this should have no valuation impact.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in HRL on this announcement; expected fundamental impact is immaterial relative to quarterly volume, pricing, and commodity-cost variables.
- Maintain HRL on a 6-18 month watchlist for evidence that foodservice mix is becoming a margin lever: act only if reported foodservice/channel growth exceeds total company growth for two consecutive quarters and management links it to value-added protein adoption.
- For existing HRL longs, use the next earnings release as the decision point: reduce exposure if volume remains negative and gross-margin guidance is not raised despite easing protein inputs; the chef program offers no near-term downside protection.
- Monitor TSN and CAG foodservice commentary as competitive checks rather than pair-trade candidates; broad restaurant traffic or distributor inventory changes will dominate any isolated benefit from chef outreach.
More News
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- What to know about US Federal Reserve’s first interest rate hike in 3 years
- Analysis: How Trump could reignite the Fed independence fight after Warsh's rate hike
- Fed Rate Hike Looms as Retail Sales Surge
- Consumers hit by one-two punch of oil and rates from Iran war. The estimated bill is $1,700 per household
- US retail sales rebound sharply in August