
Air Products to Supply Malaysia's First LNG-Based Air Separation Unit for PETRONAS Gas Berhad-Led Joint Venture
Source: PR Newswire
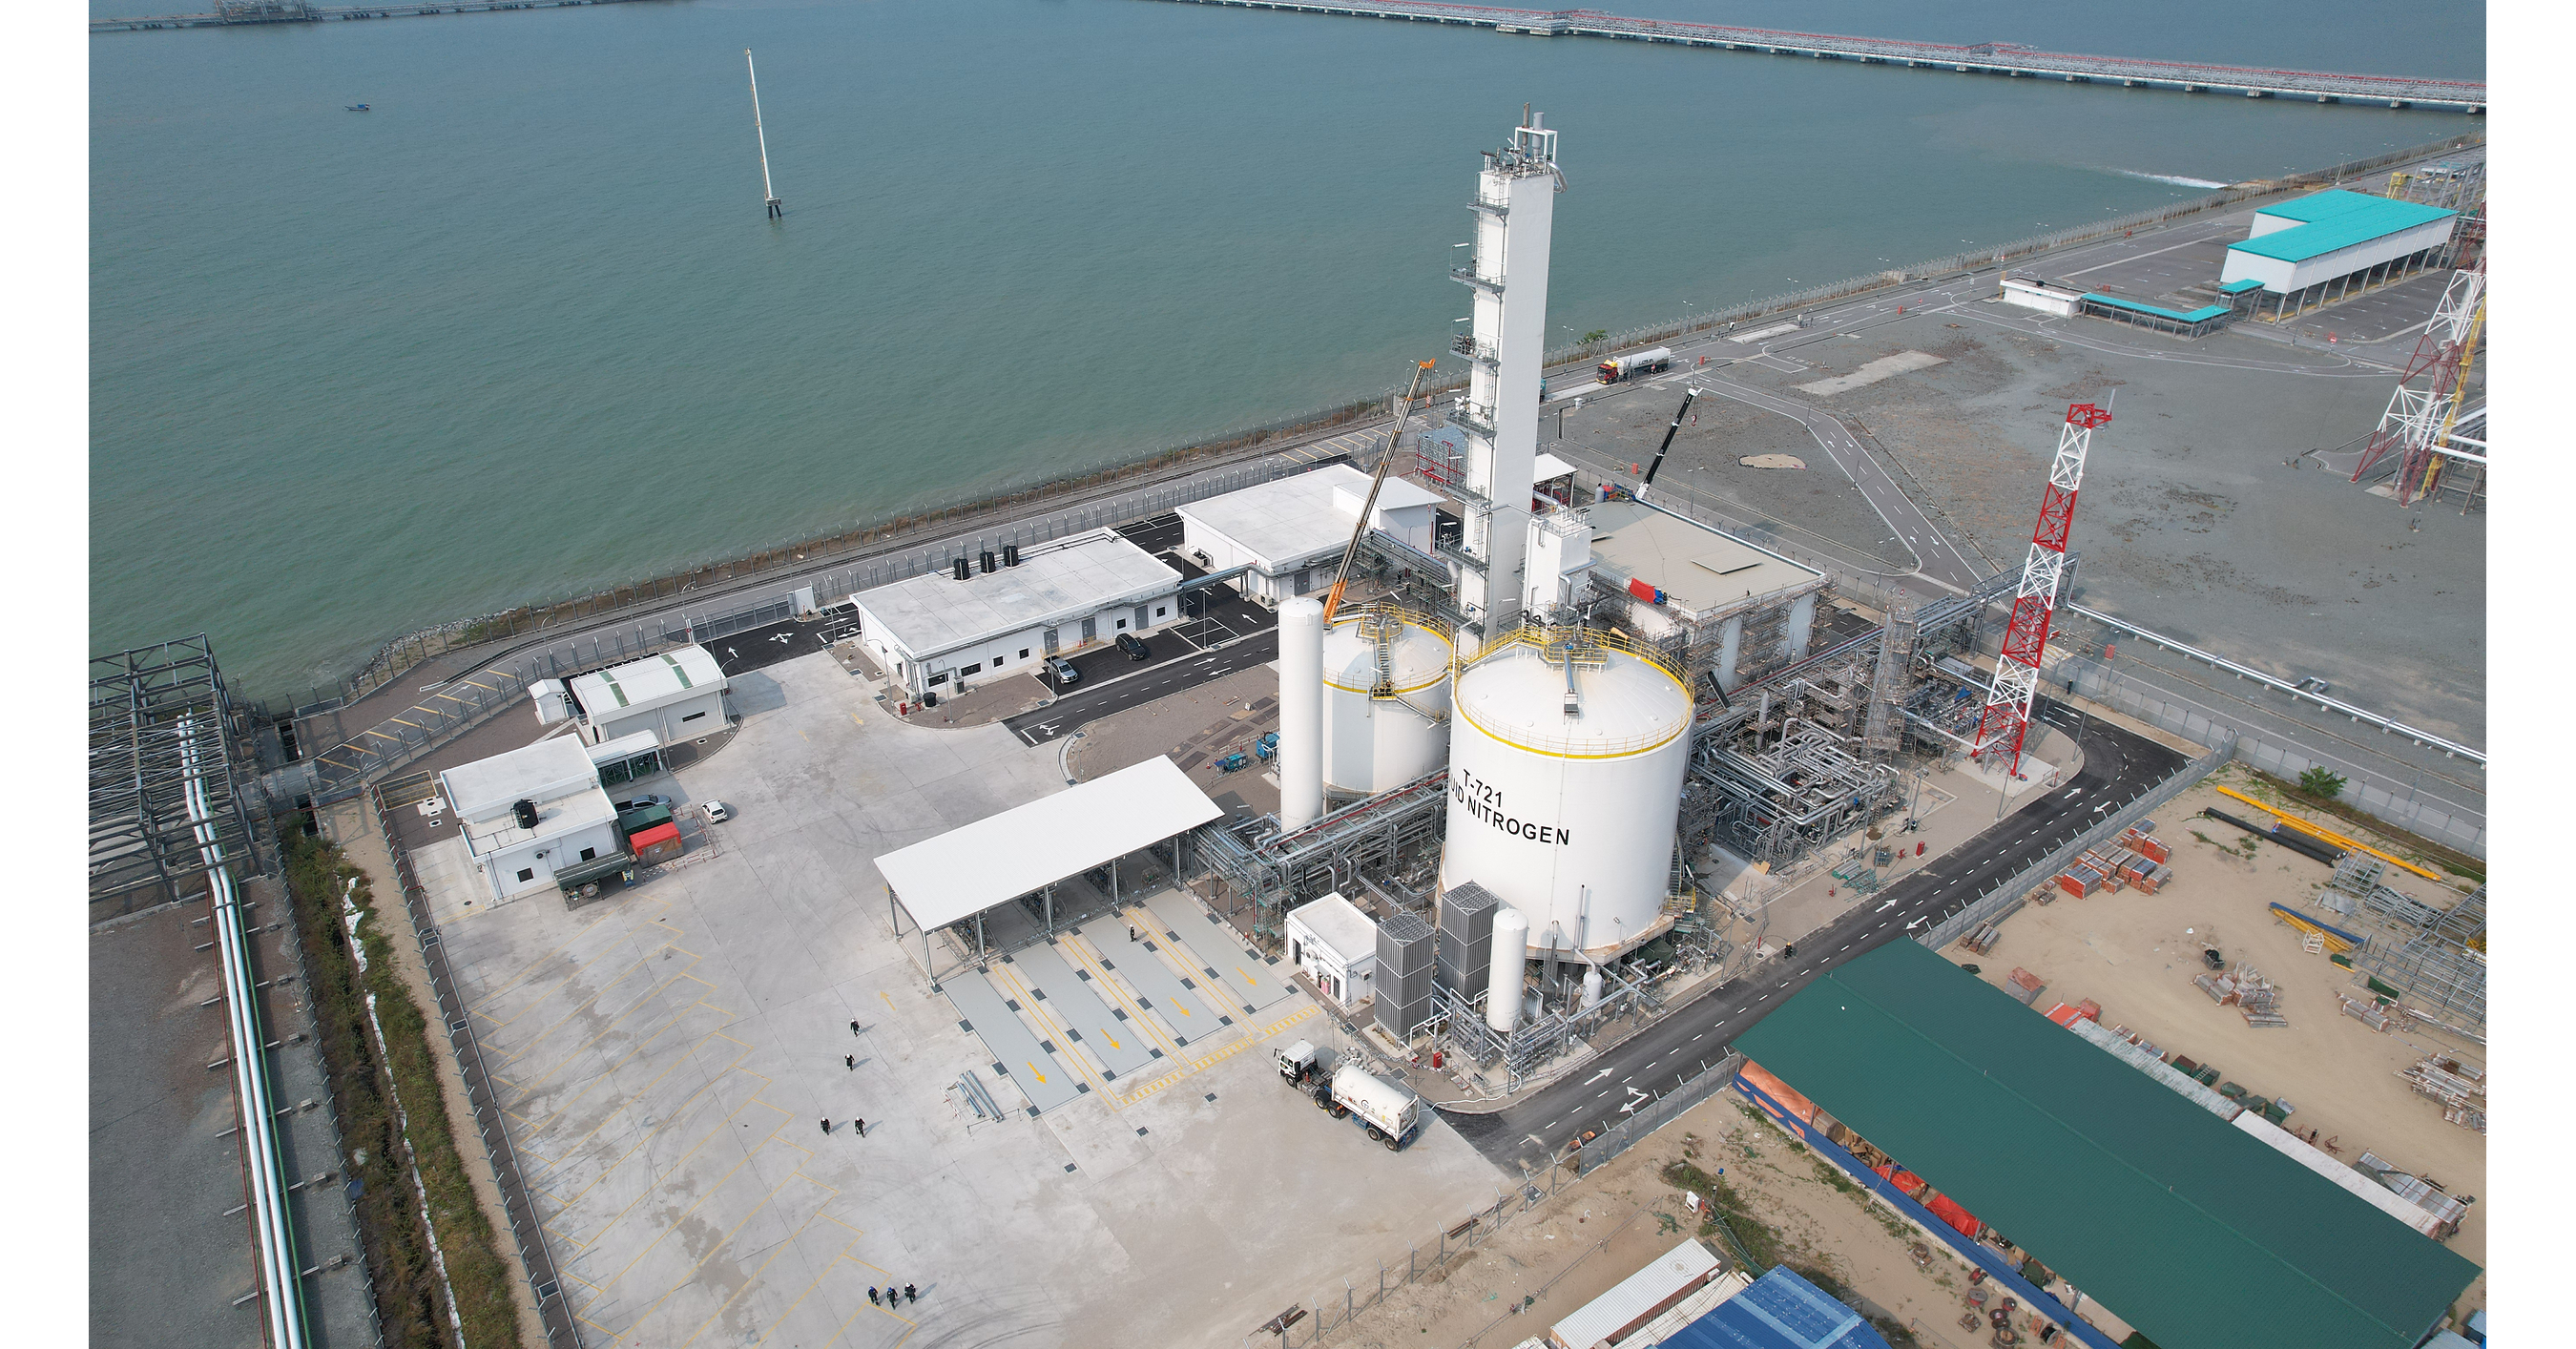
Air Products concluded a definitive agreement with PG Cold Energy 1 to design, build and operate an LNG-based air separation unit at Malaysia’s Pengerang LNG regasification terminal. The plant is expected to come online by early 2027 and produce more than 600 tonnes per day of liquid oxygen, nitrogen and argon, serving industrial customers in Southern and Central Malaysia. Using LNG regasification cold energy is expected to improve efficiency and reduce production-related emissions; the announcement provides no project cost or financial guidance.
Analysis
The announcement is more strategically relevant than financially material near term: the plant adds a regional supply node, but no project cost, contracted offtake, expected return, or APD earnings contribution is disclosed. The key economic variable is not headline capacity; it is whether LNG-terminal throughput and customer demand keep the cold-energy input advantage available at attractive utilization. If so, APD may gain cost position and displace merchant supply in Southern and Central Malaysia. If demand ramps slowly, new capacity could instead intensify local price competition, including for established suppliers such as Linde and Air Liquide.
The claimed emissions and efficiency benefit is conditional on the LNG process and should not be treated as a monetizable premium without independently verifiable lifecycle data. For APD, execution, commissioning, and customer ramp-up matter more than the announcement itself; the release gives no basis to estimate capex payback or margin impact. A delay beyond the early-2027 target, weak terminal utilization, or slower electronics/manufacturing demand would weaken the thesis. Over 6–18 months, verify project spending, binding customer commitments, commissioning milestones, and whether APD’s regional pricing or utilization improves. Contrarian read: strategic positioning may be real, but investors could overvalue the “lower-emission” framing while overlooking utilization and return-on-capital risk. No standalone earnings trade is justified on this disclosure alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- No immediate APD position change on the announcement; treat it as a modest strategic positive, not an earnings catalyst. The project’s financial scale and return are unquantified.
- Put APD on a milestone watch through early 2027. Reassess if commissioning is delayed, disclosed capex rises materially, or customer commitments and utilization fail to support the added capacity.
- For a potential APD long, require evidence of attractive project returns and sustained regional demand rather than relying on capacity or emissions claims. Falsifiers include weak customer ramp-up, local price pressure, or a deterioration in APD guidance/capital-return metrics.
- Track LNG-terminal utilization and industrial demand in Malaysia, plus local supply additions from Linde and Air Liquide; these determine whether the cold-energy advantage translates into share gains or merely expands regional capacity.
More News
- Trump says he is not keen on a deal with Iran as U.S. reportedly prepares for 'massive bombing'
- Tanker hit by multiple projectiles off north coast of Qatar, UKMTO says
- US stocks slide as oil prices fluctuate over renewed Iran war fears
- Oil, Inflation Fears Derail Record US Stock Rally
- Asia shares subdued, bonds swamped by AI debt wave
- Former world No. 1 Jon Rahm's lawyer tells court Spaniard is done with LIV Golf after three seasons
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Options, Earnings Call Transcripts, AI Chat, Bookmarks & More
- AI Tools for Family Offices: A Stack by Decision Type