
Jeden na trzech: Europa przechodzi na energię elektryczną, a VinFast buduje na dłuższą metę
Source: PR Newswire
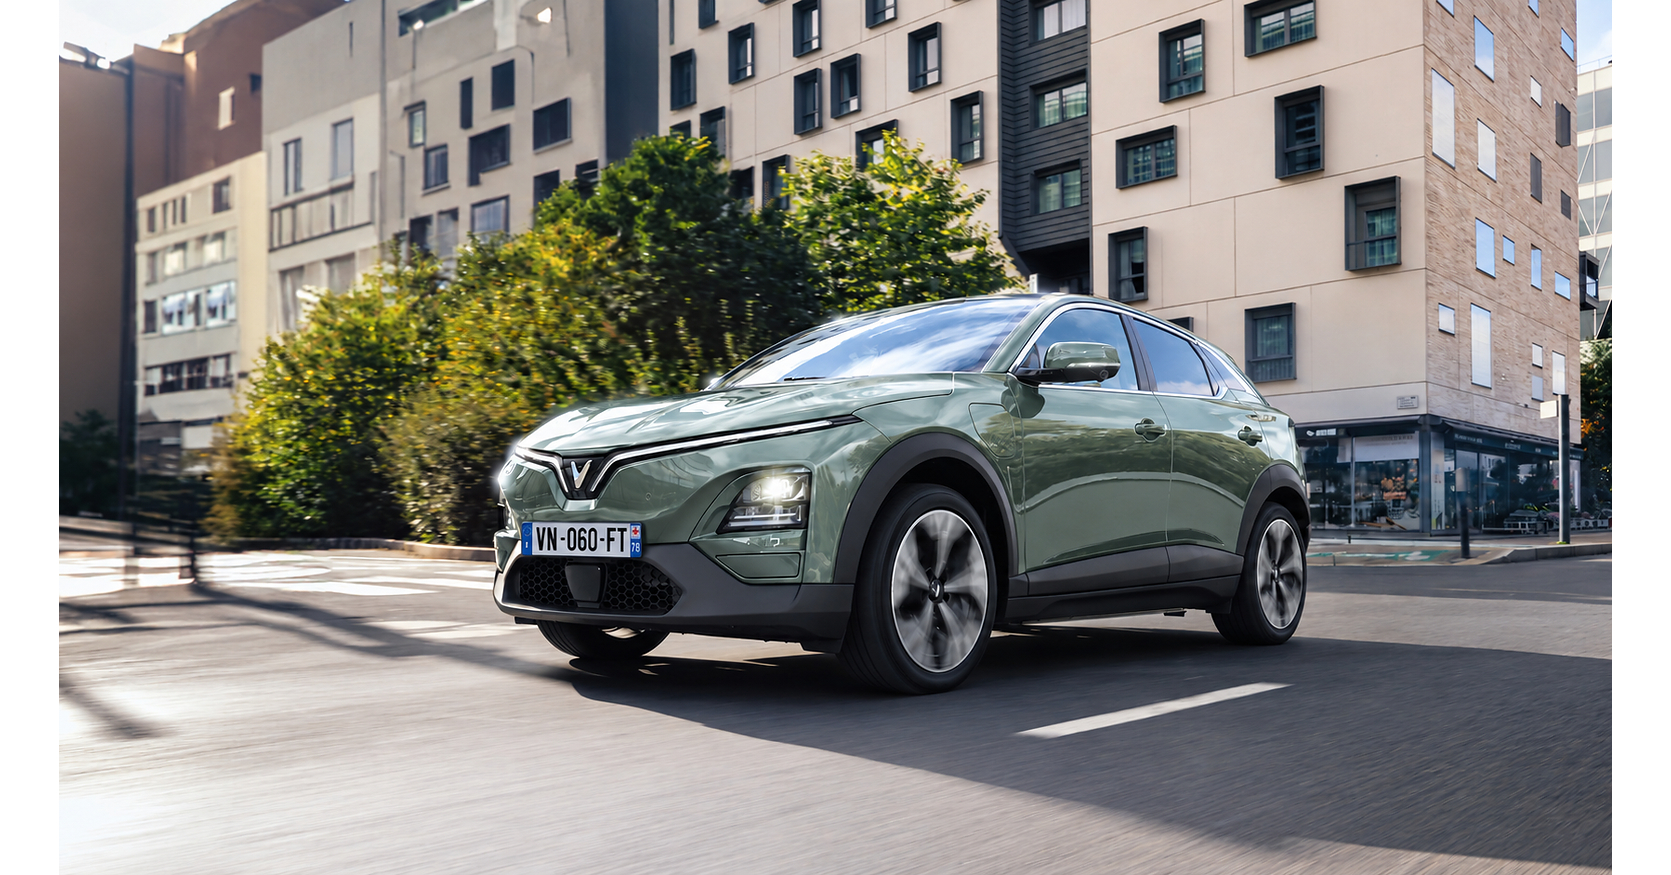
Battery-electric vehicles accounted for 30.5% of new-car sales across 16 key European markets in August, with 202,833 registrations, up 54.2% year over year; France reached a 38.3% EV share and Germany 32.5%. VinFast is positioning for this expansion through its VF 6 compact electric SUV, certified EB 12 electric bus and a dealer- and service-partner network across Europe. EU rules requiring 90% of newly registered urban buses to be zero-emission by 2030 and 100% by 2035 support the company's public-transport strategy, although the release provides no sales, revenue, or order figures.
Analysis
The investable signal is less VinFast-specific than a confirmation that European EV penetration is moving from policy-led adoption to a scale-and-service competition. This favors incumbents with established European distribution, financing and residual-value ecosystems—VWAGY, STLA, BMWYY and Mercedes-Benz (MBGYY)—over subscale entrants whose apparent price advantage can be offset by warranty reserves, spare-parts inventory and dealer-service subsidies. For VFS, European expansion is likely cash-consuming before it is margin-accretive: public-transit tenders have long qualification cycles, performance bonds and working-capital demands, while passenger-car volumes require localized service capacity to protect resale values.
The bus opportunity is strategically credible but should not be capitalized until awarded contracts, unit economics and funding terms are disclosed. Incumbent European suppliers Daimler Truck (DTG), Volvo (VLVLY) and Traton (TRATON) retain procurement advantages through installed fleets and maintenance contracts; Chinese competitors BYD and Yutong create a pricing ceiling. A second-order beneficiary is charging and grid equipment—ABB, Schneider (SBGSY), Siemens Energy (SMNEY)—because fleet electrification requires depot-level power upgrades that often precede vehicle delivery.
Near term, VFS can trade sharply on certification, dealer announcements or first municipal orders, but these are weak indicators of durable demand. Over 1-3 months, the key catalyst is independently verifiable European registrations and binding fleet orders; over 6-18 months, the thesis depends on gross-margin progression and whether European service obligations expand losses faster than deliveries. Consensus may overvalue certification as proof of commercial readiness: reliability data, parts availability and residual values—not homologation—determine repeat fleet purchases. Falsify the cautious view if VFS reports multiple funded municipal awards with disclosed delivery schedules, positive vehicle gross margin excluding subsidies, and stable warranty costs for two consecutive quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.46
Ticker Sentiment
Key Decisions for Investors
- No directional VFS core position on this release. Set an event-driven alert for disclosed European fleet contracts, monthly registration data and dealer/service-network economics; initiate only after evidence of deliveries rather than certification or partnership headlines.
- For a 6-12 month structural expression, favor long ABB or SBGSY against a short basket of European ICE-exposed suppliers via long CARZ / short a European auto-supplier proxy where executable; depot charging, switchgear and automation spend has clearer revenue capture than a single entrant's vehicle sales. Reassess if municipal charging-capex budgets are delayed or power-connection queues lengthen.
- For VFS specifically, treat any news-driven rally without contract values or delivery commitments as a potential tactical fade rather than a breakout. Risk should be capped tightly because VFS liquidity/volatility can make borrow and short execution unreliable; cover on verified order disclosure or a material improvement in quarterly gross margin.
- Monitor DTG and VLVLY for public-transit tender wins over the next 1-3 months. A sequence of incumbent wins would validate service-network barriers and weaken the premise that market growth translates into share gains for VFS; conversely, meaningful VFS awards at non-dilutive terms would require revisiting the relative thesis.
More News
- Mark Ruffalo says Paramount’s $111 billion Warner Bros. deal ‘Will stifle creativity, weaken free speech, and cost people their jobs’
- States, cities sue U.S. agencies over weaker vehicle fuel economy rules
- Trump vs Europe as US presses for release of emergency diesel stocks
- Anthropic warns government attitudes may hurt customer ties, IPO prospectus shows: Reuters
- Paramount and Warner Bros Discovery to become Skydance
- FAA says Boeing 737 Max software glitch not a flight-safety issue
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings