
CRI Merges In Morrison & Smith, Expanding Alabama Footprint
Source: Newswire
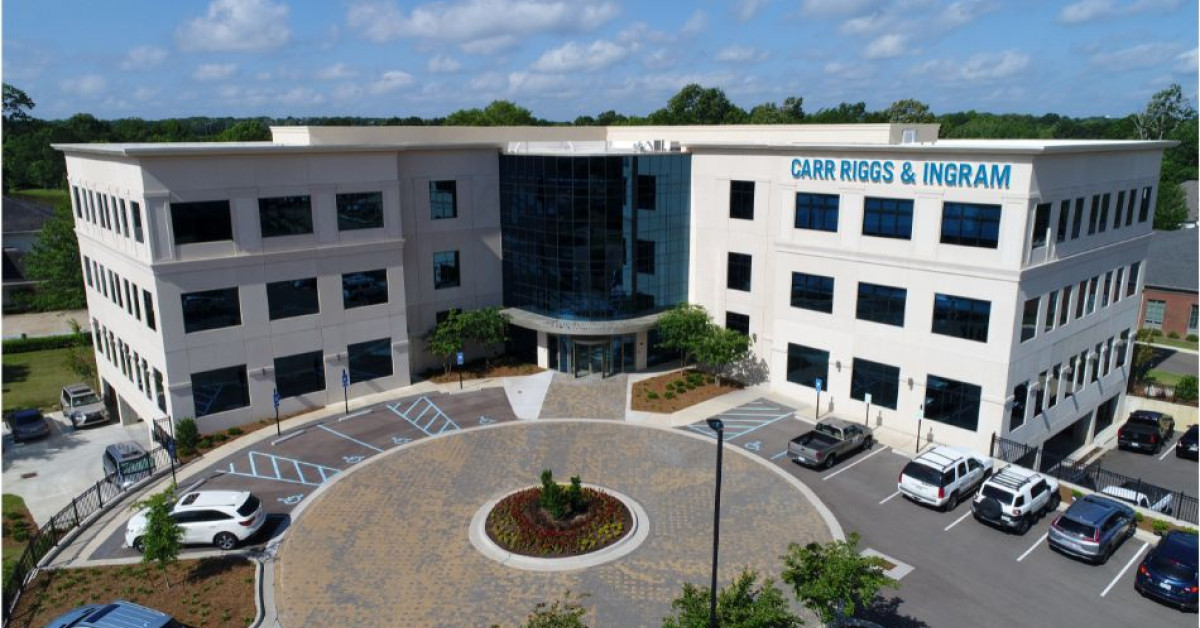
Carr, Riggs & Ingram (CRI) announced its merger with Tuscaloosa-based Morrison & Smith, LLP, extending CRI’s presence in western Alabama. The Morrison & Smith team will continue operating from its existing office under the CRI name and clients will gain access to CRI’s broader tax, assurance, advisory, wealth management, data analytics, and fractional CFO capabilities. The deal follows CRI’s late-2024 growth backing from Centerbridge Partners and Bessemer Venture Partners, signaling continued expansion rather than a standalone financial impact.
Analysis
This is more a signal on industry structure than a company-specific earnings event. The real economic value in these tuck-in deals is not the headline footprint expansion; it is the ability of a scaled platform to monetize partner succession, cross-sell advisory services, and lock in multi-service client relationships before smaller regional firms can respond. That dynamic is incrementally negative for standalone local CPA firms in secondary markets, which face a widening gap in technology, talent retention, and service breadth.
The second-order effect is on the client mix: banks, healthcare, and construction clients tend to generate recurring compliance work, but the monetization uplift comes from advisory attach rates and outsourced finance services over 12-24 months. If CRI can keep senior partners in place, the acquired book can become a feeder into higher-margin consulting and wealth businesses; if not, the deal is just a low-growth book swap with little economic impact. That makes partner retention and client churn the key variables, not the merger announcement itself.
For public markets, the nearest read-through is the persistence of the roll-up model in professional services, which is modestly supportive for scaled consolidators with similar cross-sell levers and disciplined acquisition frameworks. But this is not a catalyst-rich setup: there is no obvious near-term revenue surprise, and the market usually needs proof in retained revenue and EBITDA conversion over several reporting cycles. The contrarian view is that investors often overestimate synergies in accounting roll-ups; most of the value is defensive, not explosive, and integration slippage typically shows up only after the first renewal cycle.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No immediate trade in FCD.UN.TO or FISI from this item; the implied economic impact is too indirect and too small to justify risk-taking absent a clearer read-through to their client exposure or fee mix.
- Watch CBZ and HURN as public proxies for the professional-services roll-up model; use any post-print weakness in partner-retention or organic-growth metrics as a better entry point than chasing merger headlines.
- Set a 6-12 month alert on CRI-style consolidators: if acquired-firm revenue retention holds and advisory attach rates rise, the market may re-rate scaled accounting platforms; if not, the thesis is just multiple arbitrage with limited durability.
- For standalone regional accounting firms with visible succession risk, consider a relative-value short bias versus scaled platforms only on evidence of partner departures or slowing M&A velocity, not on this announcement alone.
More News
- AI Capex, Gamble or Jackpot?: Market Snapshot
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- Hybe shares jump 10% as K-pop sensation BTS' tour lifts earnings hopes
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Software for Buy-Side Teams: Build the Research Stack
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit