
Micron: Memory Revenue Looks More Durable Than The Cycle Suggests
Source: seekingalpha.com
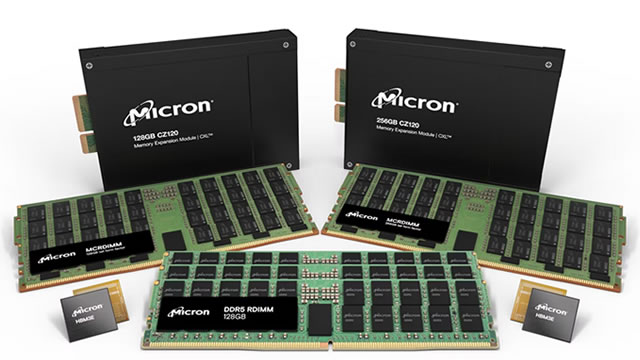
Micron is delivering record revenue, driven by surging DRAM pricing and robust AI and data-center demand; the increase is primarily pricing-led rather than volume-led and is supported largely by strategic customer agreements. The article says AI infrastructure growth and HBM adoption may dampen memory cyclicality and sustain a higher revenue base than in pre-AI cycles.
Analysis
The key underwriting question is not whether AI demand is real, but how much of the pricing uplift Micron can retain once supply responds. Strategic agreements may improve visibility and soften the usual spot-market whipsaw, but their value depends on repricing cadence, volume commitments, and whether they protect economics through a downturn; those terms are not provided. In the near term, constrained memory supply can divert capacity toward higher-value products and tighten conventional DRAM availability, supporting pricing while increasing cost pressure for device makers and data-center buyers. Samsung Electronics and SK Hynix are the relevant competitive checks: their capacity additions or aggressive pricing could quickly reset the industry curve.
Over 1–3 months, monitor contract-price commentary, customer inventories, and Micron’s shipment growth alongside ASPs. Pricing-led growth without corresponding shipment strength is more exposed to inventory digestion than a broad-based demand expansion. Over 6–18 months, new capacity, yield improvement, or slower AI infrastructure spending could restore cyclicality; HBM adoption may change the mix, but does not by itself eliminate memory supply cycles. The contrarian risk is that investors capitalize peak-like pricing as a durable earnings base. With no valuation, contract-term, or consensus data supplied, the evidence supports a cautiously positive bias—not chasing a sharp repricing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Ticker Sentiment
Key Decisions for Investors
- Consider a staged long MU on pullbacks, hedged with SOXX to reduce broad semiconductor beta; avoid adding after a momentum-driven gap until contract pricing and shipment trends are confirmed. Upside depends on pricing holding while volumes broaden; downside is a rapid pricing reversal against elevated expectations.
- For the next 1–3 months, track sequential DRAM pricing, Micron shipment growth, customer inventory commentary, and agreement renewal/repricing terms. Treat stable pricing plus improving shipments as confirmation; pricing weakness or inventory accumulation is a thesis warning.
- Reassess or exit the bullish bias if management signals materially weaker pricing or demand, or if competitor capacity additions lead to sustained industry price declines. Also watch for signs that AI infrastructure spending is slowing.
- Avoid treating customer agreements as proof of structurally de-cyclic earnings until their duration, pricing formula, and volume flexibility are verified.
More News
- How the S&P 500 can be at record highs, while the market remains oversold
- Netlist stock: why Micron will pay NLST $30M a quarter for 5 years
- Unsure how long this AI bull has? Bonds now offer a cushion at the best values in years
- Samsung, SK Hynix shares drop as Q3 earnings loom
- Netlist and Micron Enter Patent License and Settlement Agreements
- Micron Technology: Not At Its Peak, At Least Not Yet