
CordenPharma Boosts Aseptic Fill-Finish Capacity to 500 Million Sterile Injectable Units Per Year
Source: PR Newswire
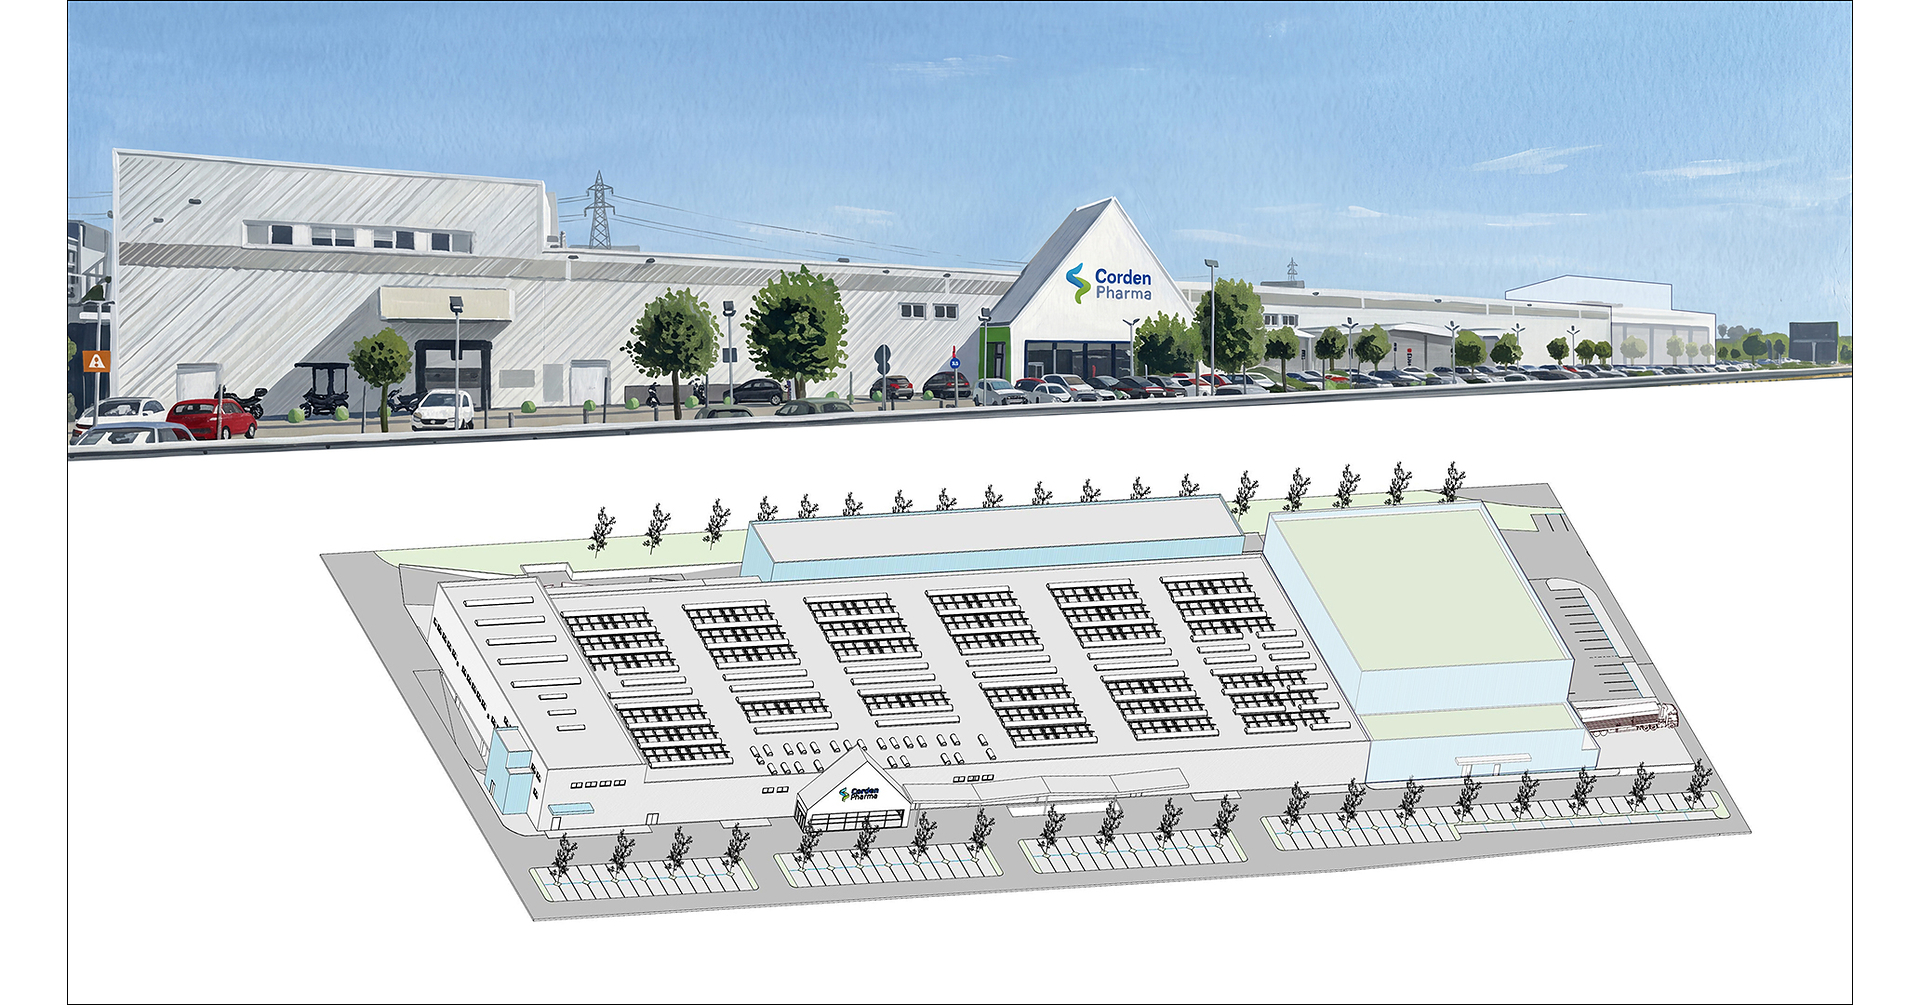
CordenPharma is committing €80 million to expand sterile-injectable manufacturing at its Caponago, Italy site, including a €13 million acquisition of an 11,000 m² building and 26,000 m² of adjacent land that increases the site footprint by more than 50%. The expansion, including two new aseptic isolator lines scheduled for completion in mid-2027 and 2028, is projected to lift capacity to as much as 500 million sterile injectable units annually. The investment targets rising outsourced demand for complex injectable therapies, including GLP-1 peptides, LNPs, oligonucleotides, biosimilars and biologics.
Analysis
The investable implication is less about a single private operator and more about where the injectable bottleneck migrates. Incremental outsourced fill-finish capacity should reduce execution risk for emerging peptide, oligonucleotide and LNP programs, but it does not create demand; utilization and customer commitments—not nameplate units—will determine whether this is pricing-accretive or dilutive for the CDMO complex. Because sterile lines require product-specific validation, the relevant competitive effect should emerge over 12-24 months rather than immediately.
Public CDMO peers with meaningful sterile-drug-product exposure—Lonza (LONN.SW), Thermo Fisher (TMO) and Siegfried (SFZN.SW)—face modest long-duration pricing pressure in European small- to mid-scale injectables if capacity is commissioned on schedule. Conversely, packaging and delivery-system suppliers such as West Pharmaceutical (WST), Stevanato (STVN) and Gerresheimer (GXI.DE) can benefit if more outsourced programs advance from clinical batches into commercial prefilled-syringe and auto-injector formats; their revenue sensitivity is to qualified unit volumes, not the CDMO's share.
Consensus may overstate the read-through to obesity-drug supply. Large GLP-1 franchises are constrained by API, device-component qualification, payer access and sponsor-owned capacity as much as filling capacity; flexible third-party lines are more likely to serve second-wave entrants, biosimilars and regional launches. The key falsifier is disclosed multi-year take-or-pay business or unusually rapid line utilization: absent that evidence by 2027, this should be treated as capacity supply rather than evidence of an industry demand inflection.
Near term, the announcement is not a stand-alone catalyst for listed equities. Over the next 1-3 months, monitor WST/STVN order commentary and LONN.SW/TMO sterile-services backlog language; over 6-18 months, watch for price concessions, lower utilization, or elevated capex across European CDMOs, which would signal a more material supply response.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No immediate directional trade: the operator is private and the commissioning horizon is too distant for a reliable public-equity earnings revision.
- Add WST and STVN to a 6-18 month watchlist for a long basket if management reports accelerating high-value product-component orders or raised biologics/GLP-1 delivery guidance; target a 15-20% upside from commercial-program conversion, with thesis invalidated by backlog deceleration or customer inventory correction.
- Use LONN.SW as the cleaner relative-risk monitor versus diversified TMO: consider a 2027 long TMO / short LONN.SW pair only if European sterile-fill capacity additions coincide with Lonza reporting lower drug-product utilization or weaker pricing. Avoid initiating before utilization data, since Lonza's modality mix and contract structure can offset isolated Italian capacity.
- Set an alert for disclosed anchor contracts, take-or-pay commitments, or commissioning slippage. Anchor contracts would strengthen the WST/STVN volume thesis; slippage or uncontracted capacity would instead increase the probability of CDMO price competition and favor avoiding pure-play sterile-services exposure.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI for Sell-Side Models, Estimates, and Internal Data
- How to Write an Investment Memo with AI: A Decision-Record Template