
FRANK BRIEGMANN PROMOTED TO CHAIRMAN & CEO OF UNIVERSAL MUSIC EUROPE, AUSTRALIA, NEW ZEALAND, CANADA & DEUTSCHE GRAMMOPHON
Source: PR Newswire
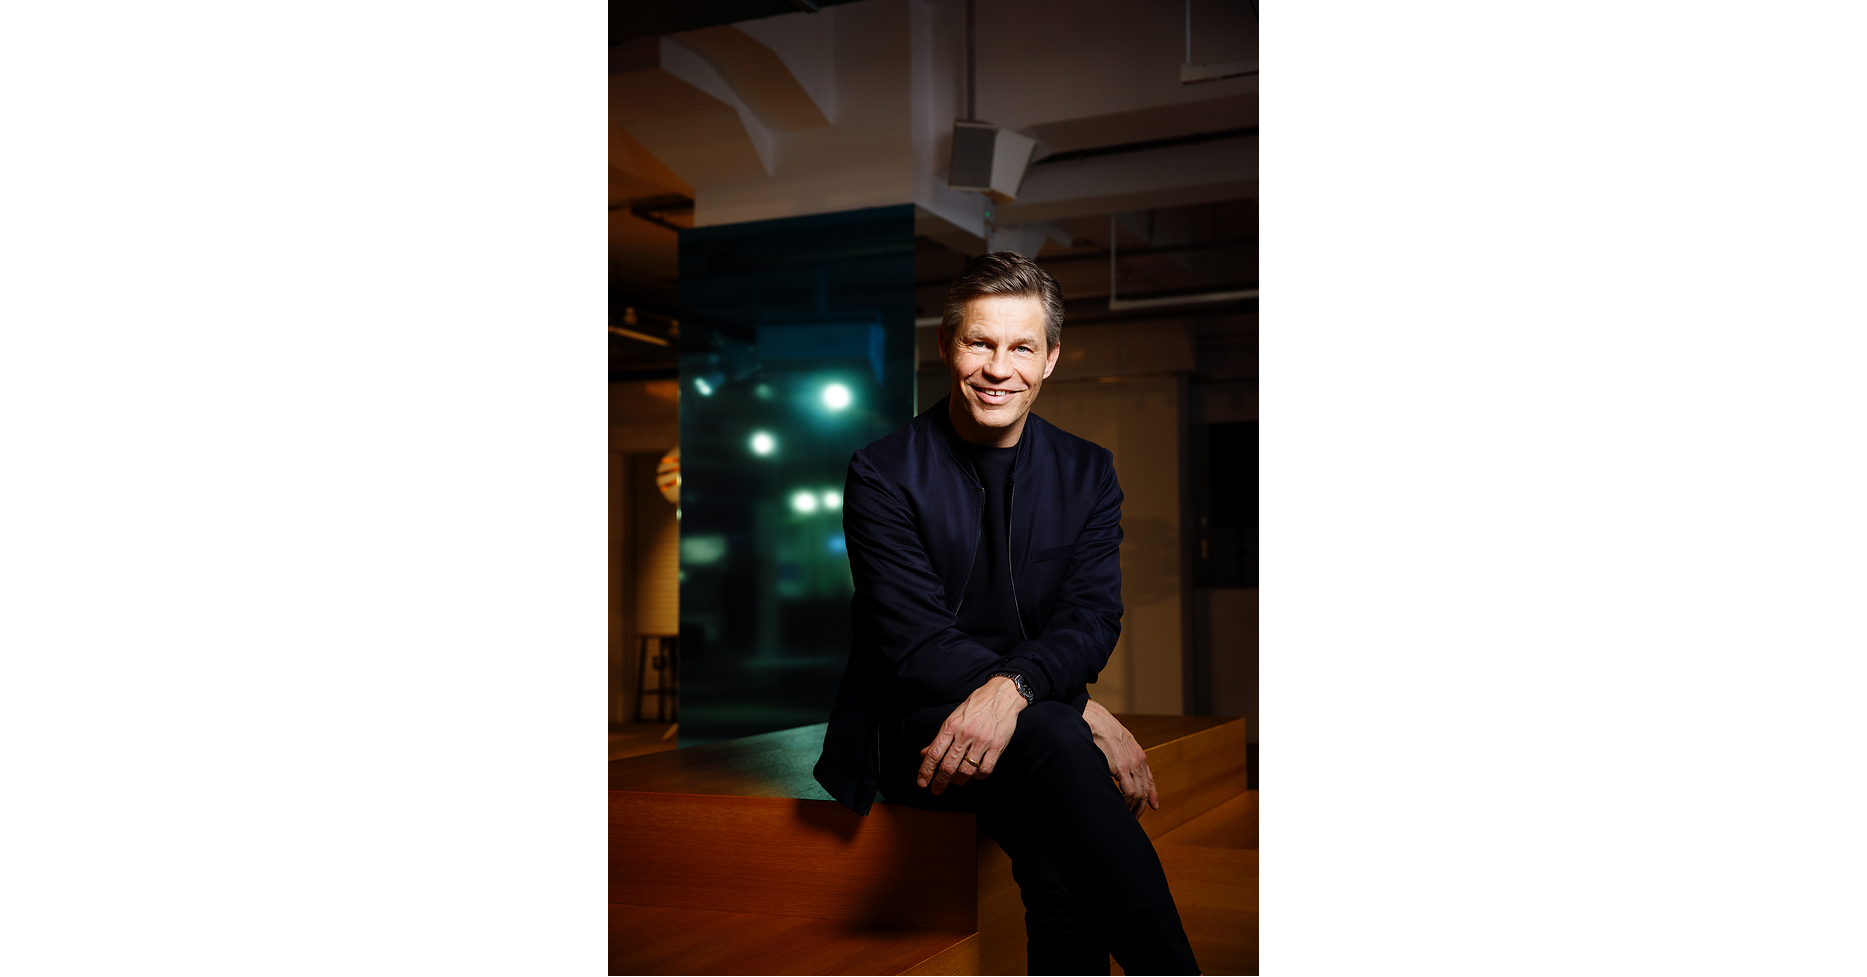
Universal Music Group promoted Frank Briegmann to Chairman & CEO of Universal Music Europe, Australia, New Zealand, Canada and Deutsche Grammophon, consolidating leadership across major international markets. The restructuring is intended to increase cross-border agility, use technology and data more effectively, and expand opportunities to develop local artists into regional and global acts. Existing country leadership remains in place, limiting near-term operational disruption.
Analysis
This is not, by itself, an earnings catalyst for UMG: it preserves country-level operating leadership while adding a regional coordination layer, so near-term P&L impact should be negligible. The investable question is whether the expanded remit produces measurable improvements in cross-market artist monetization and marketing efficiency rather than simply incremental central overhead. Evidence would be faster international streaming adoption for locally signed repertoire, lower artist-and-repertoire expense growth relative to recorded-music revenue, and sustained market-share gains in Europe and ANZ over the next 2-4 reporting periods.
The strategic upside is most credible in the mid-tier local repertoire category, where better data, release coordination, and licensing execution can lift lifetime catalog value without the acquisition costs associated with global superstar deals. Conversely, excessive regional standardization could weaken local A&R autonomy, creating an opening for Warner Music Group (WMG) and independents to sign culturally specific talent. The announced scope also signals technology-enabled execution is becoming a management priority; investors should separate genuine margin leverage from vague AI/data language by tracking adjusted EBITDA margin, digital revenue growth versus industry streaming growth, and artist-advance expense.
Consensus should treat this as governance housekeeping, not a reason to revise estimates. A positive re-rating would require proof that coordination raises organic revenue growth or margins while retaining local market share; absent that proof, UMG remains primarily exposed to streaming-price realization, DSP bargaining power, FX, and the pace of subscription growth. DB has no identifiable earnings linkage to this development despite the executive's external advisory role.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade in UMG on the appointment alone; wait for the next two earnings updates for disclosure of Europe/ANZ recorded-music growth, market-share trends, and adjusted EBITDA-margin progression.
- Maintain a relative-value watch: long UMG / short WMG only if UMG demonstrates at least two consecutive reporting periods of superior organic recorded-music growth without a material increase in artist-and-repertoire expense. The thesis is operational leverage from repertoire portability; exit if UMG underperforms WMG on revenue growth or loses European share.
- For existing UMG longs, treat any margin deterioration accompanied by elevated artist advances or restructuring costs as falsification of the efficiency thesis; reduce exposure rather than underwriting an unquantified regional-integration payoff.
- Take no action in DB: the disclosed external affiliation does not establish a revenue, capital, governance-control, or transaction linkage.
More News
- Visa and Mastercard handle nearly half of Europe’s card payments. The digital euro aims to change that
- What Twin Peaks and Coyote vs. Acme teach us about the value of what companies abandon
- Bargain Britain lures foreign buyers as hostile takeovers surge
- Cantor Fitzgerald reiterates Micron stock rating on supply outlook
- Can Trump Oust Powell From the Fed Board? What to Know
- Nvidia Faces Questions Over China AI Chip Smuggling Cases