
Top Seedz Wins Fans Nationwide with Crackers That Put Seeds in First Place
Source: PR Newswire
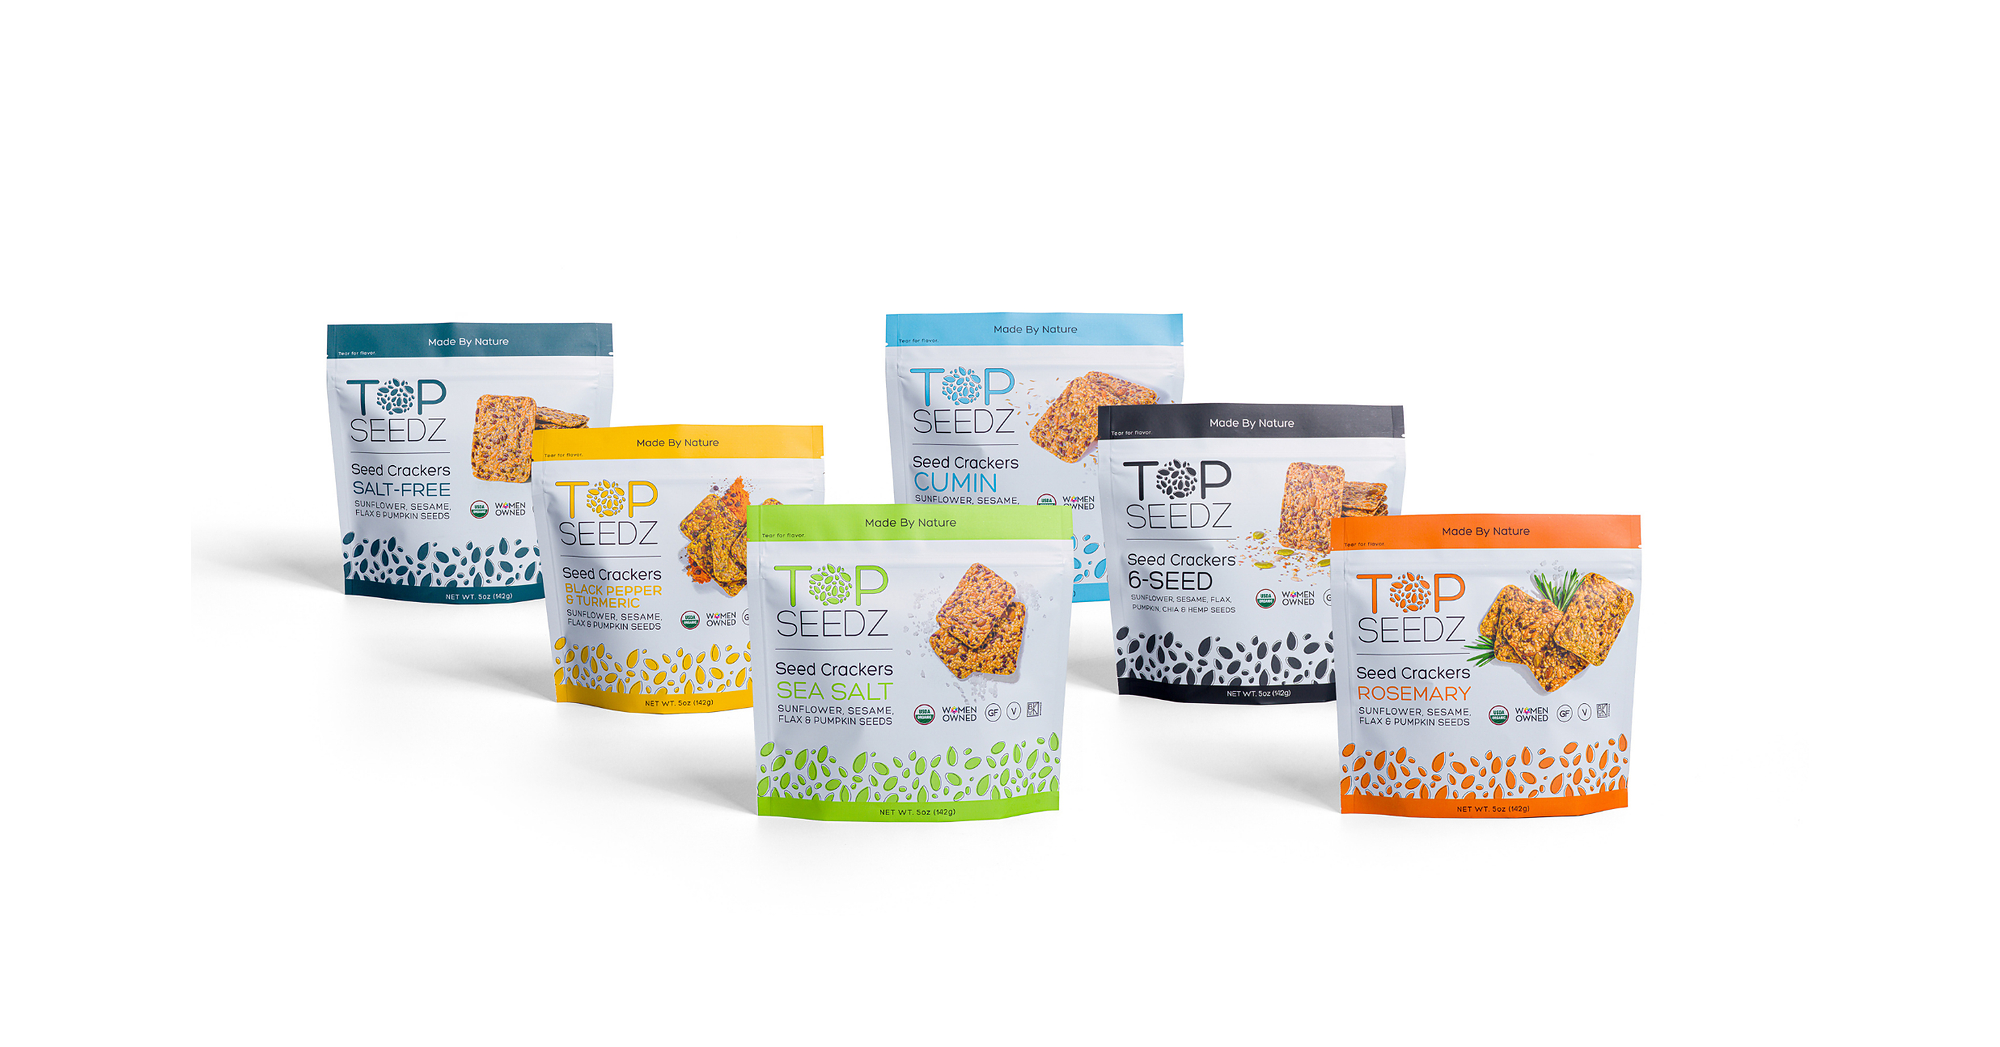
Top Seedz has brought its new 35,000-square-foot Buffalo manufacturing facility fully online as of June 2026 to meet demand, with capacity to produce 32,000 products per day. The woman-owned snack company sells in more than 3,000 stores and has a 90-person workforce, 77% of whom are minorities.
Analysis
The investable signal is not the brand’s expansion itself, but whether specialty, diet-conscious products can sustain shelf velocity after a capacity step-up. The new plant may ease a prior supply constraint, yet added capacity only creates value if sell-through, utilization, and unit economics hold; none is disclosed. Retailers such as Costco (COST) and Sprouts Farmers Market (SFM) could gain a differentiated product and incremental basket interest, but one small supplier is unlikely to move consolidated results. At the margin, successful distribution could intensify competition for shelf space among premium cracker and snack brands and retailer private labels.
Over the next 1–3 months, watch for repeat orders, store-count expansion, and evidence that production is translating into sustained velocity rather than channel fill. Over 6–18 months, utilization, ingredient procurement, labor retention, and quality consistency determine whether scale improves economics or adds fixed-cost and execution risk. The press release is promotional; store presence and stated daily capacity do not establish profitable demand. A reversal would be retailer delistings, weak repeat purchase, or inability to keep the facility utilized. There is no clear public-equity catalyst here: the company is private, and the potential sales impact is immaterial to the named retailers absent broader evidence of category growth.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No trade on this announcement alone. Do not infer meaningful earnings sensitivity for COST or SFM from a single private-label supplier’s expansion.
- Treat the brand as a channel-check watch item: verify SKU count and placement, reorder cadence, and whether distribution is expanding beyond current retailers before assigning category-share implications.
- For COST and SFM, the thesis becomes relevant only if multiple premium/natural snack suppliers show improving shelf velocity or the retailers disclose broader category momentum; otherwise the likely effect is assortment-level, not financial.
- Falsification/watch signals: product removals or shrinking placement, limited repeat orders after initial stocking, or evidence that added capacity is not matched by demand. No price target or options position is justified by the available information.
More News
- Expanding AI trade is turning safety stocks into a 'Texas hedge'
- The U.S. market has never been more focused on one single bet—but AI’s payoff will likely take decades
- Meta put out an ambitious roadmap to Muse monetization after strong quarter and guide
- CoreWeave’s market confidence erodes as bond yields spike and stock sinks
- Why is Tesla stock falling after-hours today?
- Meta ordered to pay $25 billion in case related to Cambridge Analytica scandal