
YFORE, Pionier im Bereich digitaler Spiegel, stellt in Nordamerika sein komplettes Sortiment an intelligenten Spiegeln vor
Source: PR Newswire
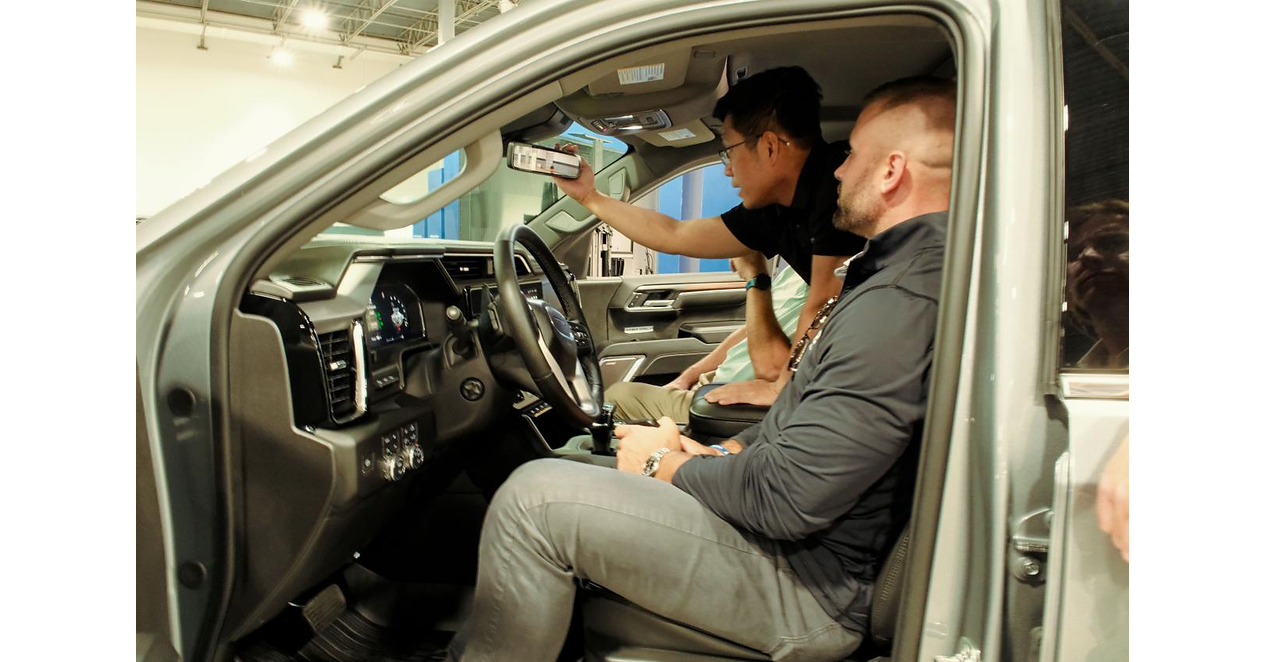
YFORE Technology began operations at a new U.S. production facility near Atlanta, Georgia, and simultaneously launched its full North America lineup of intelligent digital mirrors, including the newly premiered multifunction cockpit mirror combining DMS (driver monitoring) and OMS (occupant monitoring). The system supports inputs up to 8MP with ultra-low latency of ≤25 ms and brightness above 2,250 cd/m², using proprietary liquid-crystal technology designed to improve optical clarity and anti-glare performance. The rollout is positioned to strengthen North America’s supply chain and support OEM integrations for driver/occupant safety compliance (Euro-NCAP five-star).
Analysis
The economically relevant signal is not the product launch itself, but the attempt to move intelligent mirrors from a feature add-on to a localized platform component. That tends to favor OEMs and Tier-1s that can bundle camera, software, and validation into one integration cycle, while pressuring pure-play mirror hardware vendors whose value proposition is mostly mechanical. In the near term, the market should view this as a capability-expansion story, not an earnings event; revenue impact likely lags by 2-4 quarters until design wins convert into SOP volumes.
The second-order winner is anyone exposed to North American content localization and ADAS integration. Public comps most likely to benefit are Gentex and, to a lesser extent, Magna/Forvia if they can attach similar cockpit modules into platform programs; the loser set is lower-value mirror assemblers and standalone DMS/OMS module vendors that can be disintermediated by an integrated unit. The real margin question is whether this raises ASPs or simply compresses supplier margins as OEMs demand more functionality per kilogram and per wiring harness.
Catalyst path is mostly months, not days: watch for OEM nomination disclosures, plant utilization, and whether the US footprint wins programs tied to domestic-content requirements or tariff hedging. The contrarian view is that multifunction claims can be more marketing than monetization; the integration burden, validation load, and warranty risk may slow adoption, especially if OEMs already have validated camera/DMS stacks. If gross margins do not improve within 2-3 reporting cycles, the thesis shifts from growth catalyst to capacity overhang.
The cleanest trade is to stay selective: own the scale platform winners on pullbacks, but avoid chasing a generic 'smart cockpit' basket until real award data appears. The event is directionally positive for content growth, but too small and too uncertain to justify aggressive factor exposure today.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- Watchlist, not immediate trade: GNTX on any post-news weakness; thesis only works if North American content wins translate into visible unit growth and margin stability over the next 2-3 quarters.
- Relative-value idea: long GNTX / short a basket of lower-quality auto-electronics or mirror-adjacent suppliers with weaker software integration and higher tariff exposure; target a 6-12 month horizon, but only after evidence of OEM nominations.
- Set an alert on YFORE’s North American OEM award cadence: if there are 2+ disclosed platform wins in 1H27, that is the point to add exposure to cockpit-content beneficiaries.
- Do not short the category outright on the announcement; the near-term risk is a valuation knee-jerk in a narrow supplier group, but the fundamental impact is too small without proof of utilization and pricing.
- Falsifier: if the US plant remains underutilized or if disclosed ASPs/margins are flat on the next two earnings cycles, fade the 'localization winner' narrative and rotate out of the trade.
More News
- The IEA wants to empty its oil reserves faster. A federal watchdog says the US isn’t ready for what comes next
- ‘If nothing is done, it’s almost inevitable’: Ukraine’s Yuriy Ryzhenkov on why steelmaking is on the brink of collapse as Russian bombing intensifies
- Why is LG Innotek stock plunging today?
- UK Chancellor Healey Must Find £35B Ahead of Budget, IFS Warns
- TotalEnergies, KKR expand U.S. solar venture with 700 MW addition
- Why is SK Hynix stock sliding today?
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Introducing AllMind: A New Data & AI Workspace for Institutional Investors
- AI Tools for Private Equity Due Diligence: A Buyer Workflow