
Valtra präsentiert die 6. Generation der T-Serie
Source: PR Newswire
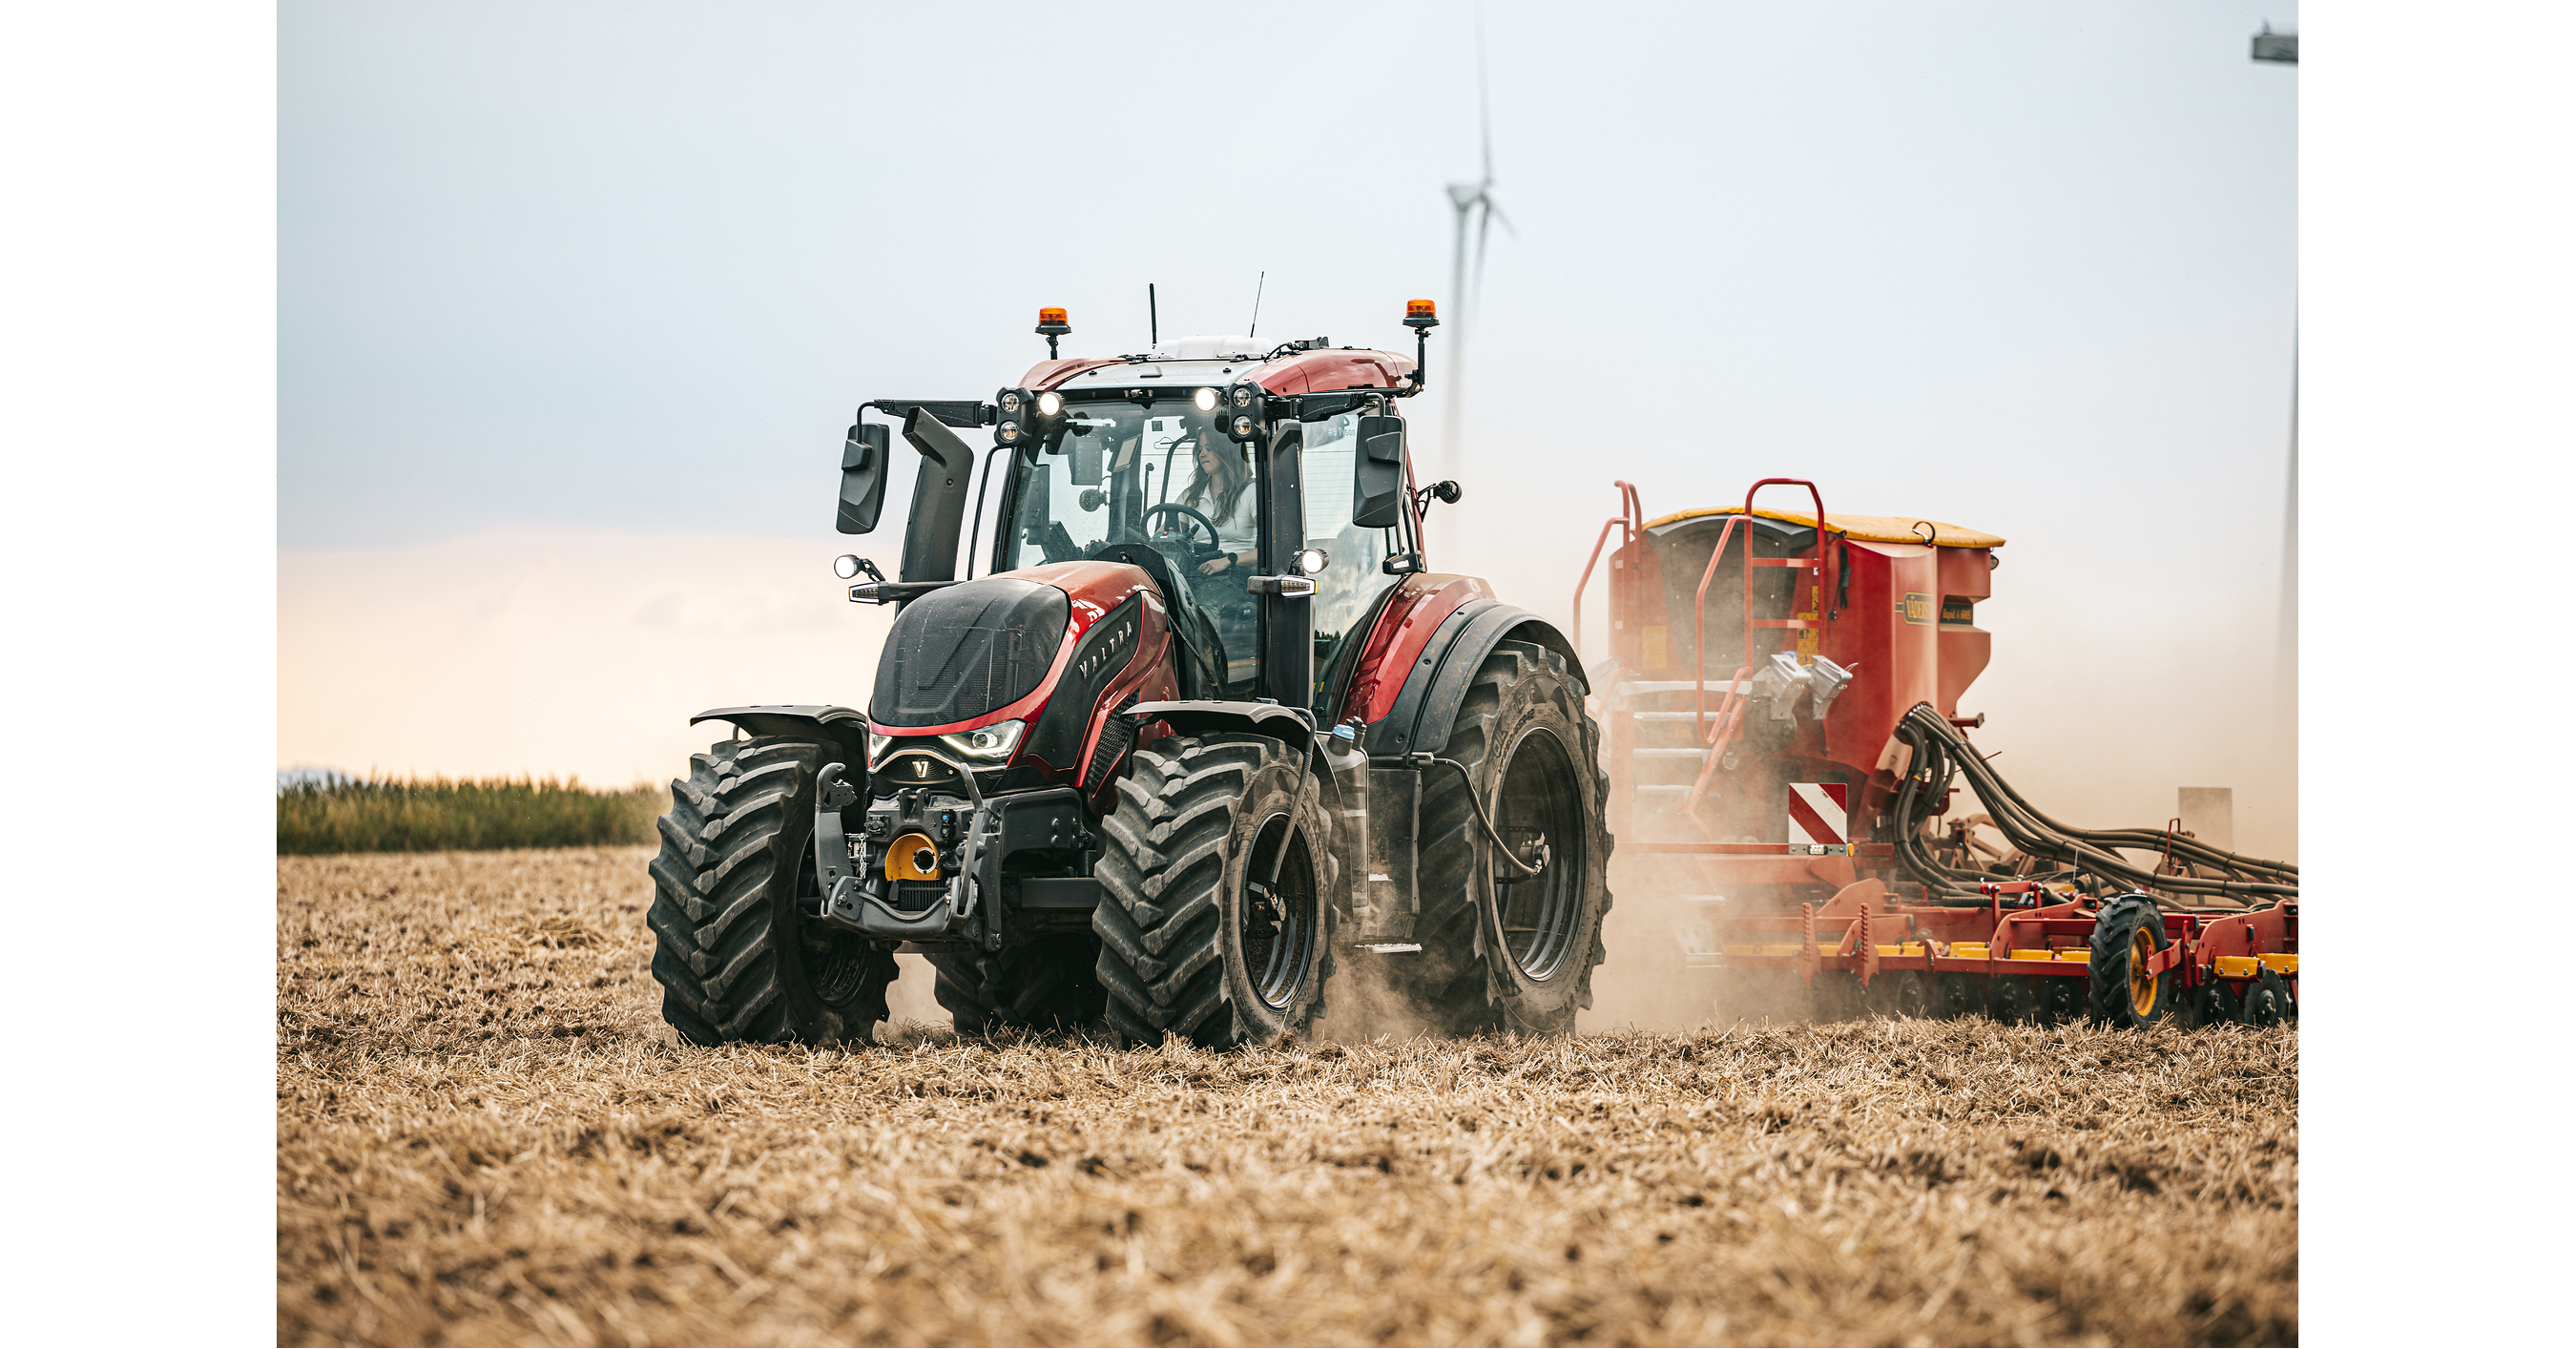
Valtra, an AGCO brand, launched the sixth-generation T-Series tractor range, offering 170-245 horsepower and customer deliveries expected by year-end. The flagship T236 uses a 7.5-liter AGCO Power CORE75 engine producing up to 245 hp and 1,184 Nm of torque, with fuel consumption claimed to be up to 5% lower than the prior 74HD engine. The product adds SmartTouch Gen2 controls, automated implement and hydraulic functions, and factory-installed PTx FarmENGAGE connectivity, supporting AGCO's precision-agriculture product offering.
Analysis
The investable implication is less the unit launch than whether Valtra can convert its Northern Europe and Latin America dealer footprint into higher-content, higher-margin configurations. Digital controls, implement automation and mixed-fleet connectivity can lift attachment revenue and reduce warranty/service friction, but the near-term P&L benefit depends on paid software adoption rather than factory-fit hardware penetration. For AGCO, a successful rollout would support mix and parts/service margins in 2027; it is unlikely to offset a broader downturn in large-equipment replacement demand over the next one to three quarters.
Competitive pressure should fall most directly on CNH Industrial (CNH) and Deere (DE), where operator-interface and precision-ag features are important retention tools in professional-farmer accounts. Valtra's customization capability is potentially more valuable for contractors than the stated fuel-efficiency gain: fleet operators monetize lower training time and more consistent implement settings across seasonal labor. The second-order risk is that interoperability makes it easier for customers to retain non-AGCO implements and software, limiting the usual proprietary-data moat unless PTx FarmENGAGE proves materially better at workflow integration.
Consensus should not treat this as a discrete earnings catalyst. Machinery purchases are credit- and farm-income-sensitive, and launch-year production often carries supplier qualification, dealer training and inventory risks before volume benefits emerge. The key falsification points are weak initial order intake or elevated dealer inventories by the next two earnings reports, which would turn a product-cycle narrative into a working-capital drag; conversely, evidence of premium-spec mix, software attach rates and stable gross margin would justify a more constructive 6-18 month view.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade on the release alone: wait for AGCO's next two earnings calls for Valtra order intake, dealer inventory and precision-ag/software attachment disclosures. A position without those data is primarily a macro farm-income bet, not a product-launch trade.
- Set a 1-3 month alert to accumulate AGCO only if management confirms launch orders are incremental rather than replacement demand and maintains segment-margin guidance; size modestly, with thesis invalidated by a guidance cut tied to Europe/Latin America inventories or adverse working-capital commentary.
- For investors seeking relative exposure after confirmation, consider long AGCO / short CNH over a 6-12 month horizon. The thesis is superior premium mix and digital attachment at AGCO versus a more challenged competitive pricing backdrop at CNH; exit if AGCO's margin trend fails to outperform CNH by the following two reported quarters.
- Avoid using DE as the primary short leg: Deere's precision-ag franchise, financing arm and scale make it a poor clean hedge to a Valtra-specific rollout. DE is better viewed as a read-through on whether the feature set is genuinely differentiated or merely closing an industry-standard capability gap.
More News
- Nvidia Faces Questions Over China AI Chip Smuggling Cases
- $8.2B acquisition validates AI-picked chip stock: +20% since June
- Nike Warns Sales Slump Will Worsen This Fiscal Year
- Nuveen CEO on Schroders Deal, Plans for Combined Company
- Broadcom to lend Anthropic up to $42 billion to lease its chips, filing says
- New Mexico wants Meta to pay up to $40 billion in penalties after data privacy trial
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- Alternative Data Due Diligence for Institutional Investors