
Sun Auto Tire & Service Expands Arizona Footprint with Acquisition of Klipper Automotive
Source: PR Newswire
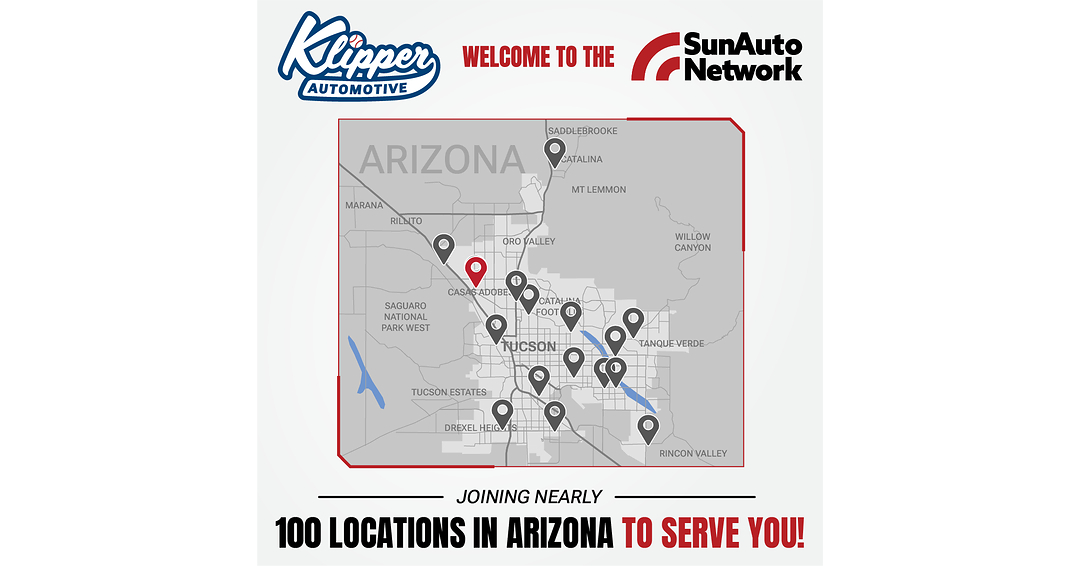
Sun Auto Tire & Service announced the acquisition of Klipper Automotive to expand its Arizona footprint to nearly 100 locations statewide across a portfolio of trusted local brands. The deal is positioned to add scale and resources (training, technology, and operational support) while preserving Klipper’s local brand and customer experience in the greater Tucson market. Overall, it signals continued strategic growth, though it’s not detailed as a financial-material earnings catalyst.
Analysis
This reads as a classic fragmented-service roll-up where the value creation is less about headline market share and more about route density, labor utilization, and procurement leverage. The biggest economic winner is the acquirer’s own margin stack if it can spread call-center, digital booking, and technician scheduling across a tighter metro footprint; if not, the deal is just revenue bought at mediocre returns. The market should also infer that subscale independents in the Southwest lose pricing power fastest when a chain can cross-sell warranties, offer longer hours, and funnel customers between nearby bays.
Public comps most exposed are weaker regional auto-service operators rather than parts retailers. A name like MNRO is more vulnerable to share loss and labor poaching because these tuck-ins raise the bar on customer experience and technician retention, while ORLY/AZO are only indirect beneficiaries via a slightly larger professional-install ecosystem. The second-order effect is supply-chain discipline: larger networks can centralize parts procurement and reduce working capital, which is quietly accretive in a high-rate environment.
Near term, I would not expect this to move public equities by itself; the real catalyst is whether this is one of several acquisitions in the next 1-3 months. The contrarian risk is that investors overrate the moat from “local brand preservation” — brand continuity does not protect against margin pressure if wage inflation or rent resets outpace same-store sales. Over 6-18 months, the key falsifier is whether acquired-store EBITDA margins expand; if they don’t, the roll-up story becomes leverage expansion, not durable compounding.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade on the headline; treat this as a sector-read-through, not a catalyst for a directional position in public equities.
- If you want a public-market expression, use a small pair trade: long DRVN / short MNRO over 1-3 months. Thesis: scale leaders with acquisition capacity should outperform weaker regional operators if consolidation accelerates; stop out if MNRO shows positive same-store-sales inflection.
- Bias long ORLY or AZO only on pullbacks as low-beta indirect beneficiaries of a larger professional-install base; this is a 6-18 month structural tailwind, not a day-trade catalyst.
- Set an alert on private-credit and leveraged-loan spreads for auto-service roll-ups. If financing costs widen materially, acquisition cadence slows and the consolidation premium in the group should compress.
- Watch for a second Arizona tuck-in or any disclosure on acquired-store margin expansion; that would confirm the roll-up thesis and justify a larger long exposure to the scale winners.
More News
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
- OpenAI projected to bring in $20bn less in revenue than expected
- Soitec climbs 7% as BofA turns bullish on silicon photonics demand
- Schott Pharma drops after Deutsche Bank downgrades on demanding valuation